


Happy Monday, everyone!
So, you remember when we discussed the need for oil to head south to the $70s to really push our bullish thesis? Well apparently, $100 oil is the new cheap oil.
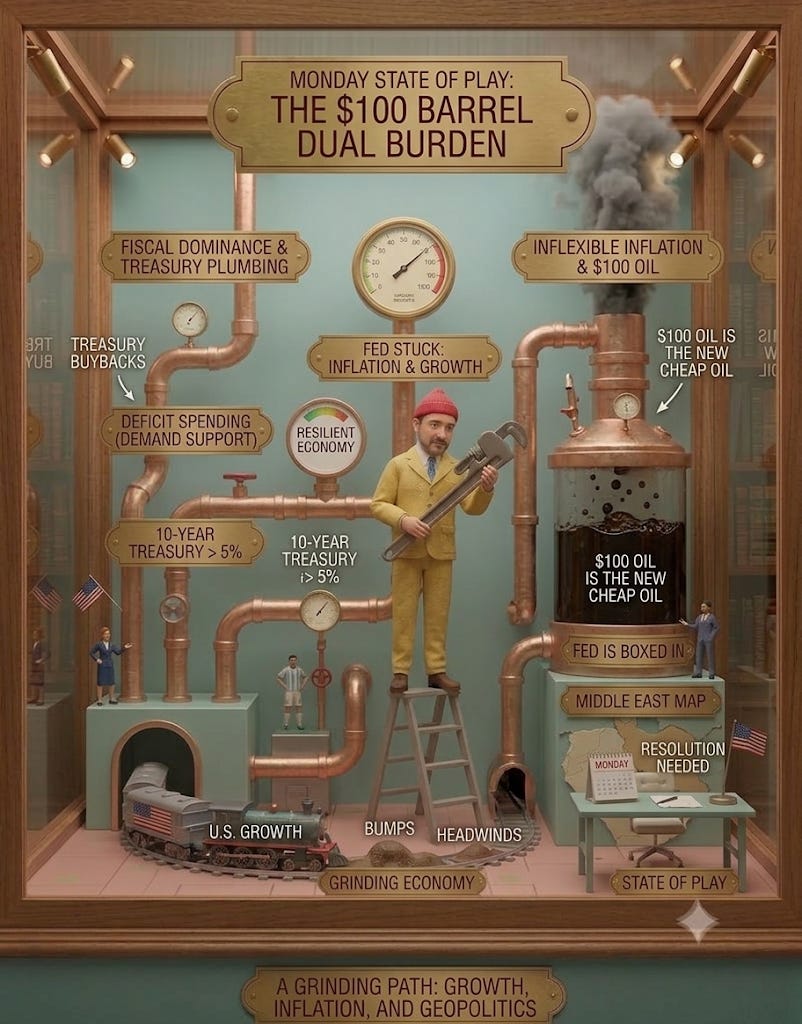
Last week gave us the first Fed rate hike in three years, a 10-year Treasury above 5% and oil north of $100. Yet underneath all of that, the economy continues to hold together surprisingly well. The Fed itself raised its 2026 growth forecast while acknowledging that inflation is proving considerably harder to kill.
That fits what we’ve been expecting:
Growth isn’t rolling over
Inflation isn’t going quietly
The Fed is now stuck dealing with both.
Fiscal dominance and some helpful Treasury plumbing, including expanded buybacks at the long end, are a big reason $100 oil hasn’t derailed things. Deficit spending keeps demand supported while the buybacks help liquidity in the long end of the Treasury market, but neither one fixes inflation. Until oil comes down and inflation starts to moderate, the Fed stays boxed in.
Our expectation is that the economy continues to grind higher, but the path stays bumpy, and we still need resolution in the Middle East to really push forward. Elevated energy prices and higher rates remain the biggest headwinds against otherwise solid investment, fiscal support and a still-resilient consumer.
Week Ahead
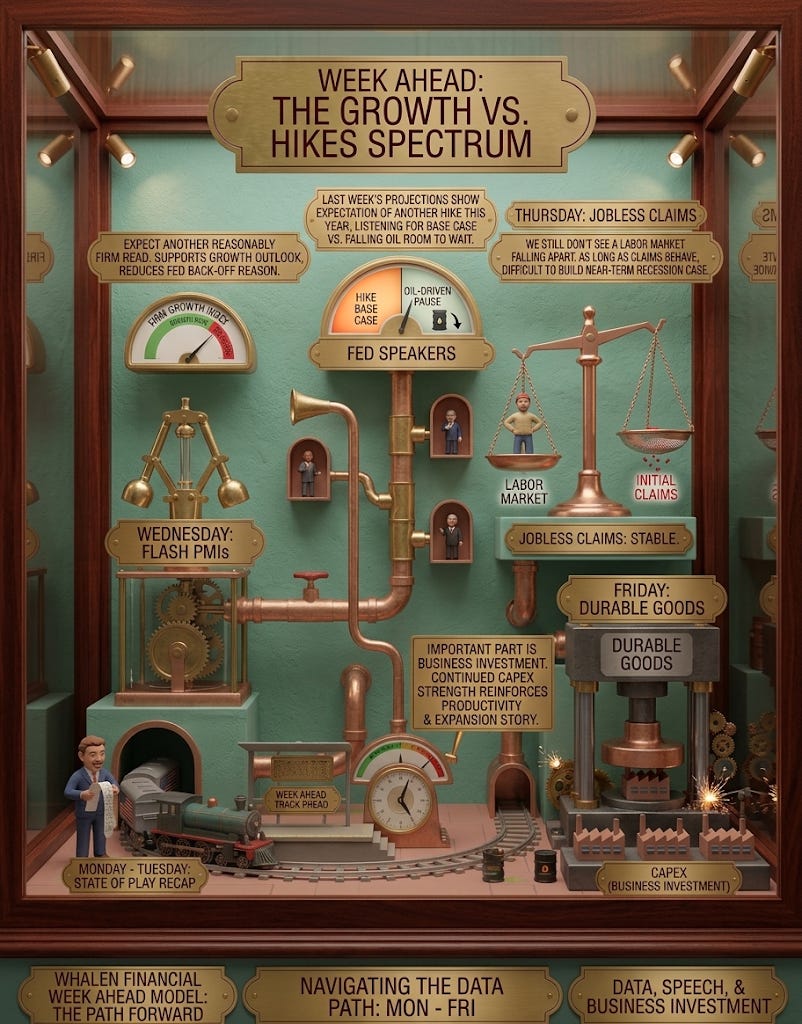
Flash PMIs — Wednesday: We expect another reasonably firm read. That would support the growth side of our outlook, but it also gives the Fed less reason to back away from another hike.
Fed Speakers: Last week’s projections showed policymakers expecting another hike this year. We’ll be listening for whether that’s becoming the base case or whether falling oil gives them some room to wait.
Jobless Claims — Thursday: We still don’t see a labor market falling apart. As long as claims behave, it’s difficult to build a near-term recession case.
Durable Goods — Friday: The important part is business investment. Continued capex strength would reinforce the productivity and expansion story we’ve been talking about.
Earnings
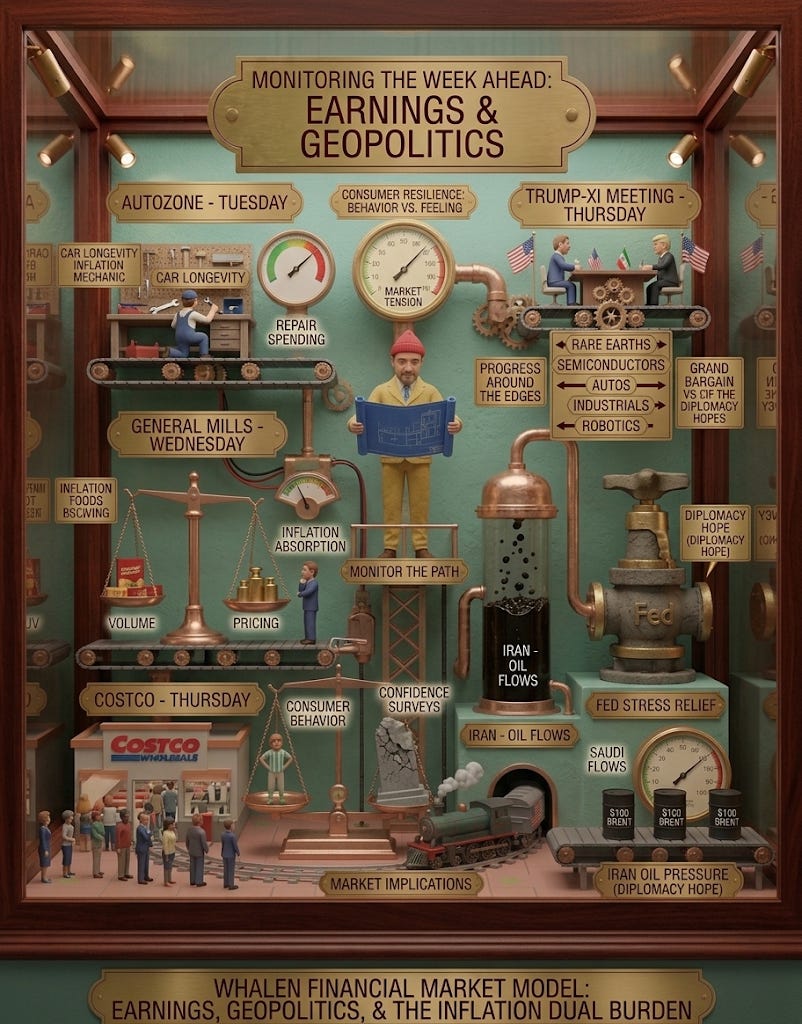
AutoZone — Tuesday: Watch repair spending. Consumers keeping cars longer would fit a consumer that’s becoming more selective, not necessarily one that has stopped spending.
General Mills — Wednesday: Pricing versus volume is the story. We want to know how much inflation consumers are still willing to absorb.
Costco — Thursday: Probably our best consumer check this week. Confidence surveys look awful. Costco helps tell us whether actual behavior looks nearly as bad.
Events
Trump-Xi — Thursday: We’re expecting progress around the edges, not a grand bargain. Extending the trade truce or improving access to rare earths would matter for semiconductors, autos, industrials and robotics.
Iran: This may actually be the bigger market story. Hopes for diplomacy and improving Saudi flows helped push Brent back toward $100 Monday. If that continues, it takes some pressure off inflation and, importantly, the Fed.
Global Macro
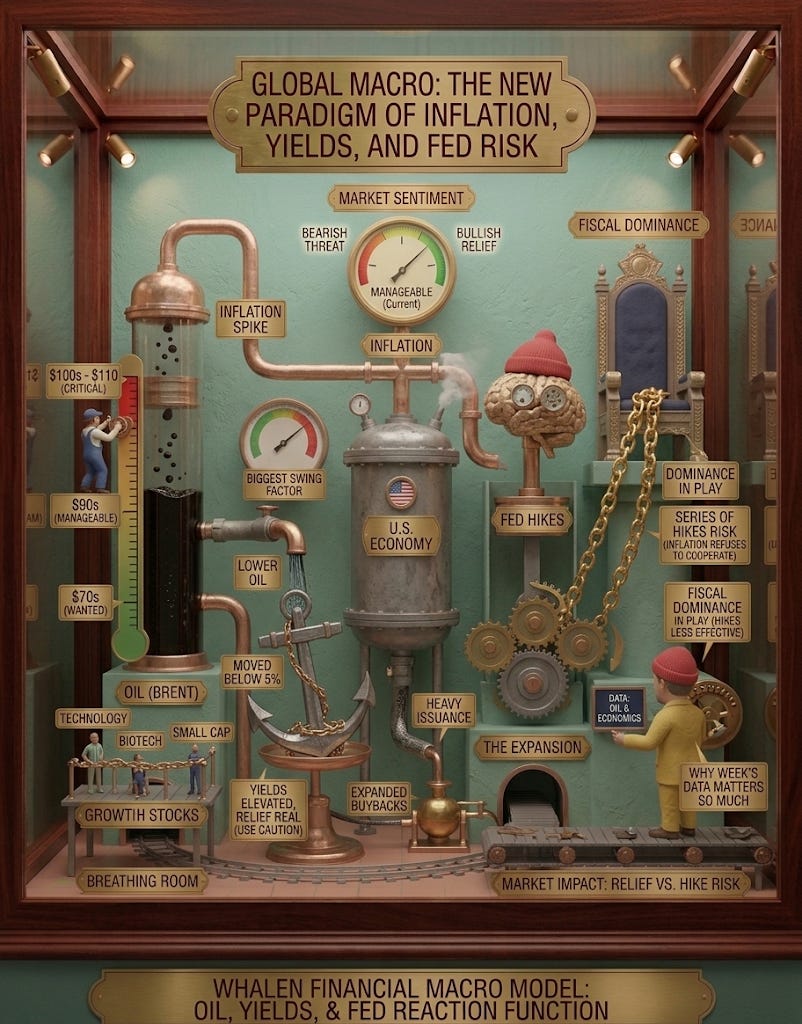
Oil: This is still our biggest swing factor. Brent around $100 is manageable. Another run toward $110 puts inflation, yields and Fed hikes right back at the center of the market.
10-Year Treasury: The move back below 5% is important. Lower oil is helping, and that gives technology, biotech and other rate-sensitive areas some breathing room. Heavy Treasury issuance is still keeping yields elevated, though expanded buybacks at the long end are helping market liquidity at the margin, so we’d treat the relief as real but not something to lean on too hard.
Fed: We don’t think one hike suddenly kills the expansion. The bigger risk is a series of hikes because inflation refuses to cooperate. With fiscal dominance in play, hikes do less to cool things than usual, which is part of why the Fed may have to do more. That’s why oil and this week’s economic data matter so much.
State of Play
So the story really hasn’t changed as much as last week made it feel. We still see an economy moving through a reflationary expansion, supported by investment, productivity and fiscal spending. But inflation is running hotter than we’d like, and the Fed has finally decided it can’t just watch from the sidelines.
This week gives us a little more data to work with, and the setup we’re looking for is a pretty favorable combination of firm growth and falling oil. This lets the economy keep moving while taking some pressure off inflation and rates.
However, firm growth and another surge in oil is a very different story.
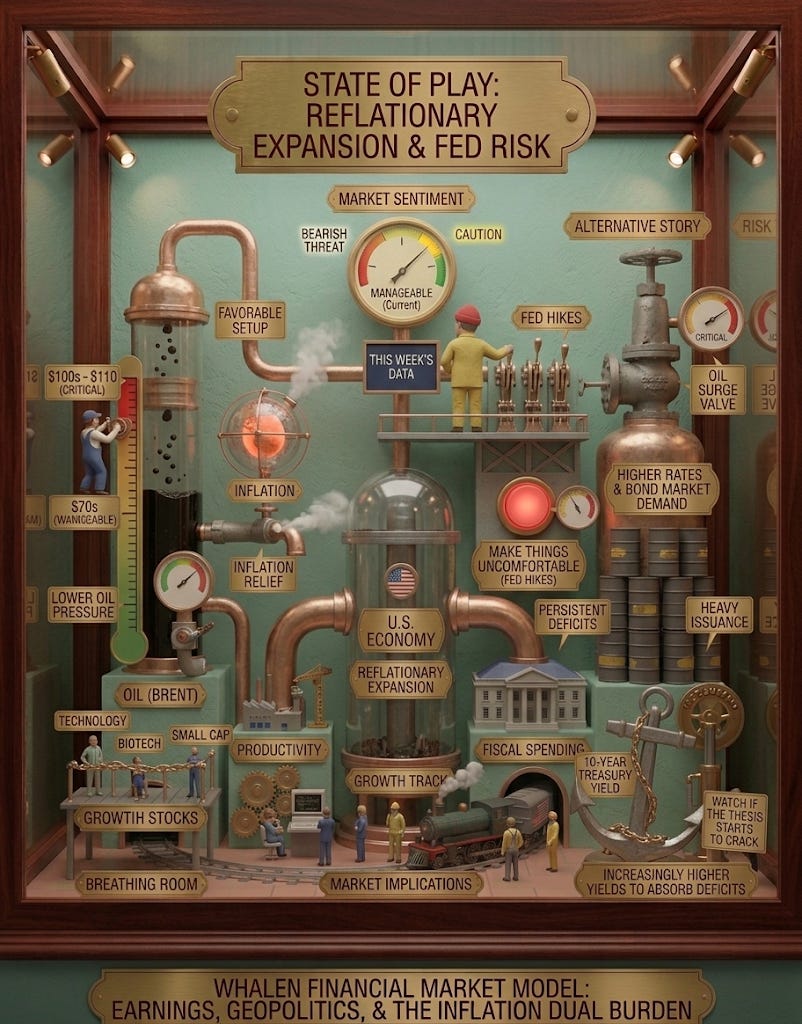
For now, we think the economy keeps grinding along and oil remains the variable that determines just how uncomfortable the Fed has to make things. The risk beyond oil is the bond market demanding increasingly higher yields to absorb persistent deficits, and that’s the one we’d watch if the thesis starts to crack.
$100 oil never looked so good.
$100 oil as the new cheap oil only works if growth keeps eating the inflation. I am watching whether Brent toward $110 shows up in the same week as firm PMIs. If Wednesday PMIs soften while oil stays sticky, does the boxed-in Fed frame flip to a growth scare?