


Happy Monday, everyone! So, if you’re one of those hoping for a nice quiet dog-days of August week where everyone sneaks out early and pretends Labor Day has already started, I have some bad news.
Wednesday’s PCE print is just the thing to ruin that.
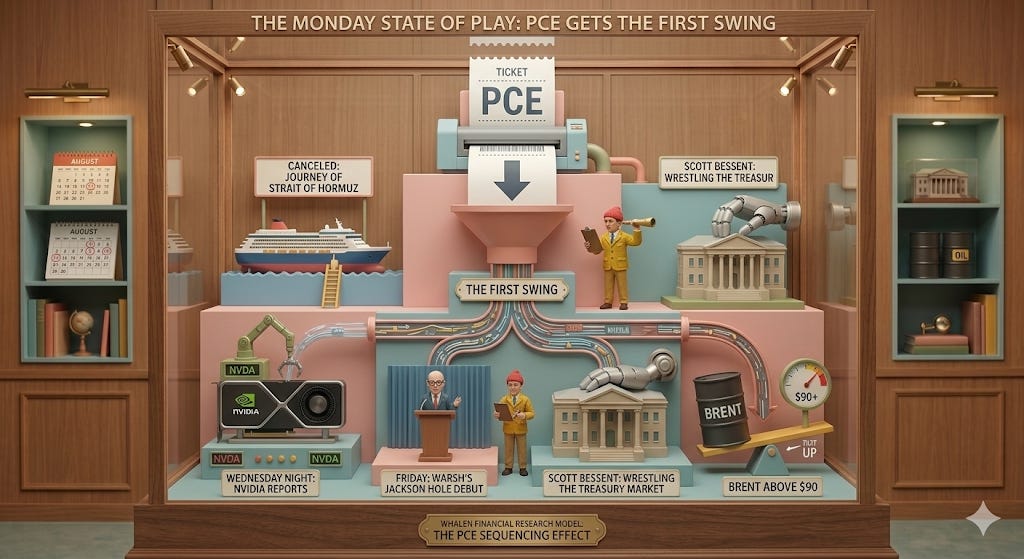
So yes, Nvidia reports Wednesday night and yes, Kevin Warsh makes his Jackson Hole debut Friday and I get that Scott Bessent is still trying to wrestle the long end of the Treasury market back into its cage, while Brent is hanging out above $90 and my tickets to the Journey of Strait of Hormuz cruise are still canceled. But PCE comes first, and more importantly, it changes how we’re going to interpret almost everything that follows it.
Wednesday Comes First
So the Fed’s traditional inflation gauge arrives Wednesday morning alongside revised second-quarter GDP and durable goods. We’ll find out how much the market still cares about PCE under Warsh at 8:30 a.m., and then Warsh gets his chance to tell us what he thinks on Friday.
June core PCE rose just 0.1% for the month, but that still left the year-over-year rate at 3.3%. Headline PCE actually fell 0.1% in June, largely because energy prices were coming down at the time. The market is looking for core PCE to move back toward roughly 0.2% in July, which would leave underlying inflation sticky but not necessarily accelerating and that may be all we need.
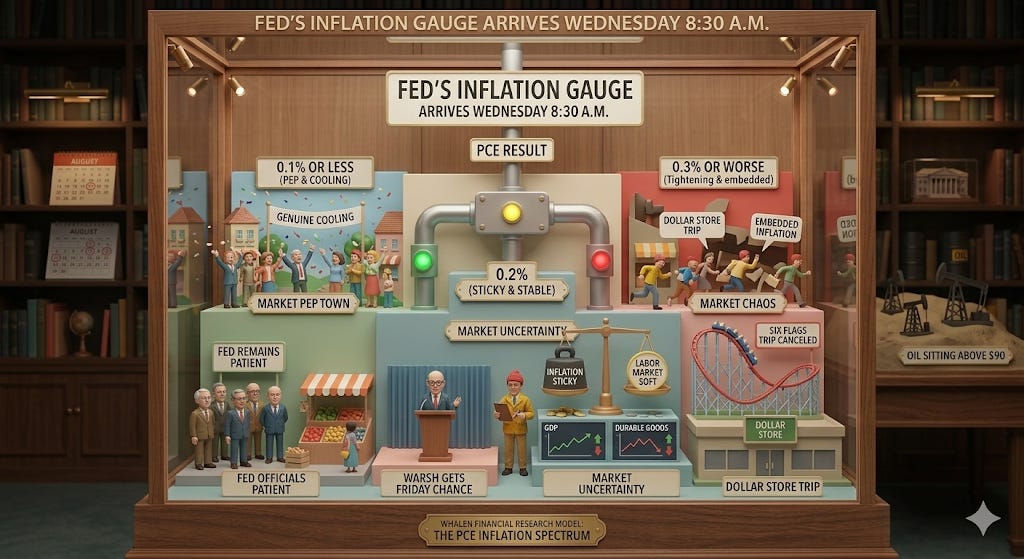
A 0.2% core print probably doesn’t give Warsh a reason to start hiking rates in September, but it doesn’t exactly give him permission to claim the coast is clear. Now what it does do is allow the Fed to remain patient, Bessent gets some room to keep working the long end and we get to keep talking higher vs. lower rates.
But what will really put some pep into the back half of your week is if we get 0.1% or less. Then you’ve got CPI, PPI and PCE all pointing toward some genuine cooling in underlying inflation, which would make it increasingly difficult for the Fed to justify tightening into a softer labor market and hard to put a lid on the market.
Print 0.3% or worse and your family trip to Six Flags could become a trip to the dollar store. Suddenly the market has to reconsider the possibility that inflation really is becoming embedded, particularly with oil sitting where it is, and Warsh gets to really show his chops.
The Catch Is Oil
So the problem with Wednesday’s inflation report is that it’s July data while oil is real-time over $90.
Brent is still trading around $93 even after pulling back Monday, and the underlying supply situation around Hormuz hasn’t exactly improved. Vessel traffic through the Strait remains dramatically below pre-war levels, emergency reserves have already absorbed a huge part of the initial supply shock and inventories are being drawn down as the market continues to compensate for disrupted Middle Eastern flows. Reuters estimates roughly 290 million barrels of the 400 million barrels of emergency reserves committed earlier this year had already been released by July.
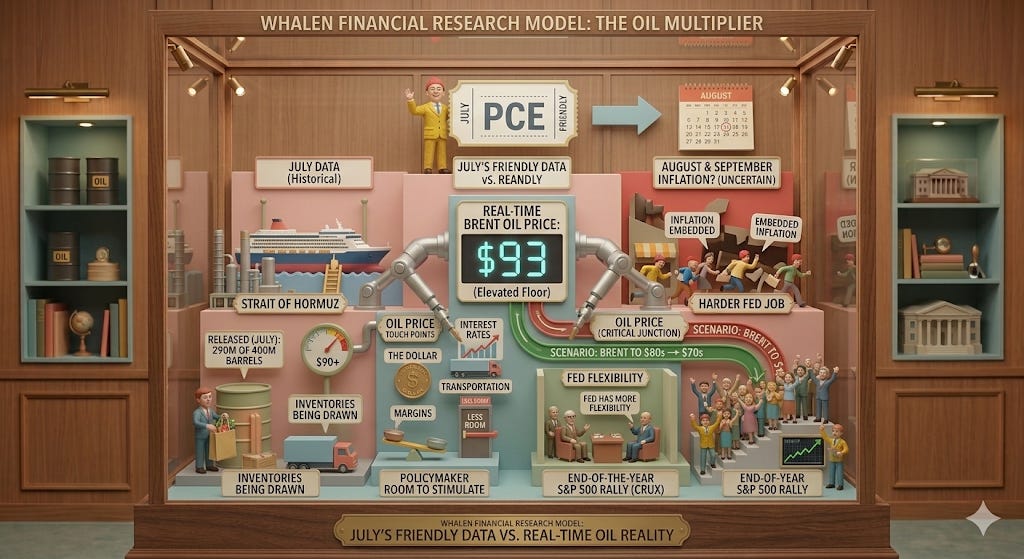
And so a friendly July number tells us that underlying inflation was behaving before the latest oil move. It doesn’t however tell us what August or September inflation is going to look like if Brent stays above $90, gasoline remains elevated and refined-product shortages continue.
If Brent starts working its way back toward $80 and eventually into the $70s, the inflation story gets much easier and the Fed has considerably more flexibility. If Brent decides $92 is the new floor and starts taking another run at $100, the Fed’s job gets harder no matter what Wednesday’s PCE print says.
This is why I continue to think oil is one of the most important macro variables on the board. It touches inflation, consumer spending, interest rates, the dollar, transportation, margins and ultimately the amount of room policymakers have to stimulate the economy.
In addition, lower oil prices happen to be the crux of our end-of-the-year S&P 500 rally.
The Bond Market Gets a Vote
PCE is pretty important, but what happens after the PCE number is really gonna be interesting.
See, PCE is still officially the Fed’s inflation yardstick, but Warsh has been pretty clear that his lens is broader and he doesn’t want to rely on any single measure to tell him what underlying inflation is doing.
If PCE comes in soft and the two-year, 10-year and 30-year all move lower, great, Bob’s your uncle and away we go.
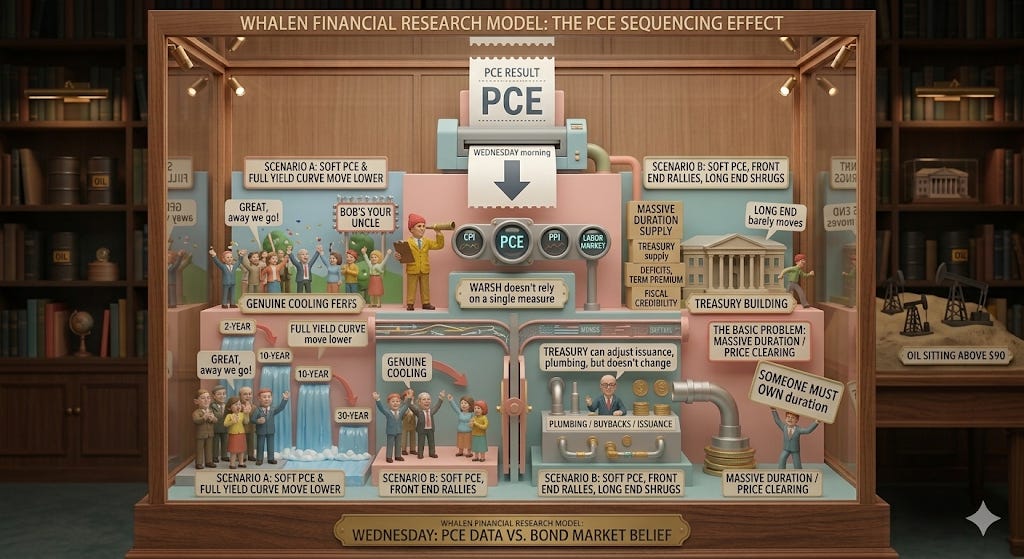
But if PCE comes in soft, the front end rallies and the 10-year and 30-year barely move, that’s a different message. Then the long end may not care much about one inflation print because it’s more worried about deficits, Treasury supply, term premium and fiscal credibility.
We could get the front end rally while the long end shrugs.
Treasury can improve market plumbing, conduct buybacks and adjust issuance, but none of that changes the basic problem: someone still has to own a massive amount of duration, and eventually the price is gonna have to clear the market.
So Wednesday isn’t just about what PCE says, it’s about what the bond market believes.
Nvidia Gets the Night Shift
And if things weren’t exciting enough Wednesday morning, Nvidia reports after the closing bell.
I believe this one matters for reasons that go well beyond whether Nvidia beats earnings by a few billion dollars again. The makeup of the AI trade has changed.
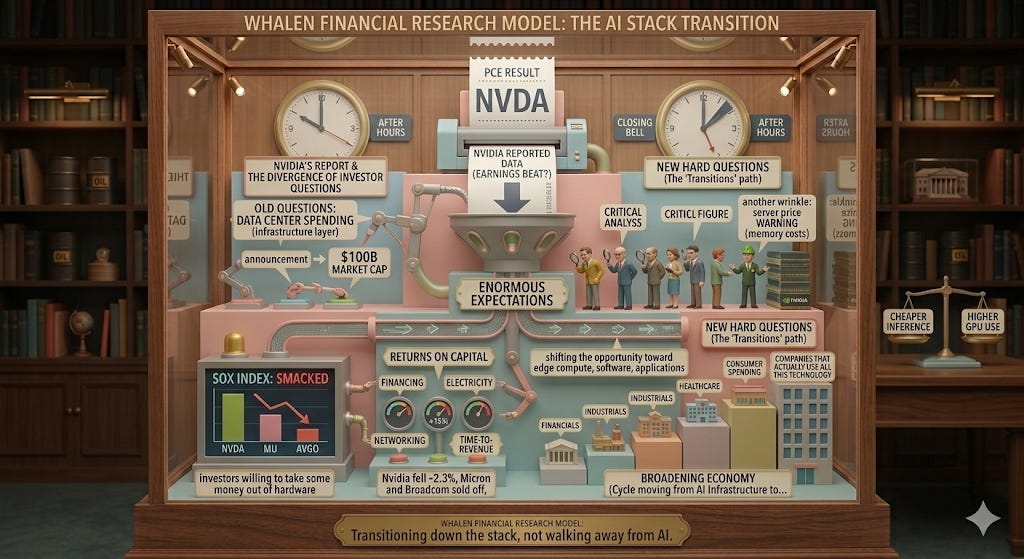
Remember those days where all it took was the announcement of another giant data center and boom, $100 billion to everyone’s market cap. Investors are beginning to ask harder questions about returns on capital, financing, electricity, memory, networking, utilization and how quickly all this spending actually turns into revenue.
This is a good thing, but it’s also exactly what we’ve been talking about with the transition from spending to proof as we move through the AI stack.
Nvidia enters the report with expectations still enormous, while the semiconductor complex got smacked again today. Nvidia fell roughly 2.3%, Micron and Broadcom also sold off and the Philadelphia Semiconductor Index dropped sharply, helping pull the Nasdaq down about 0.8%.
I wouldn’t read too much into one trading session, but I do find the divergence interesting.
For most of this cycle, if semiconductors sneezed the whole market caught pneumonia. Today looked more like investors were willing to take some money out of AI hardware while still buying other parts of the economy.
That doesn’t mean hardware demand is cooling. It means the opportunity is broadening.
That’s exactly the type of broadening we’ve been expecting if this cycle begins moving from AI infrastructure toward financials, industrials, healthcare, consumer spending and eventually the companies that actually use all this technology.
So the question Wednesday night isn’t whether AI spending is disappearing. I don’t think it is. The question is whether the rate of spending can remain high enough, financing available enough and returns visible enough to justify the valuations that have already been placed on the infrastructure layer.
There’s also another wrinkle. Nvidia has reportedly been warning customers that some AI server prices could rise more than 15% next year as memory costs increase. That’s not telling us hardware demand is cooling. If anything, it says the opposite.
What’s changing is where the value is moving inside the AI stack.
As inference gets cheaper, AI becomes economical to deploy across far more workloads, devices and industries. The cheaper each inference becomes, the more inference gets used. That keeps demand for GPUs, memory, networking and power strong, but it also starts shifting the opportunity toward edge compute, software, applications and the companies that can actually monetize all that cheaper intelligence.
That’s why we’ve been moving down the stack rather than walking away from AI.
And Then There’s Warsh
Finally, Kevin Warsh gets the mic Friday at Jackson Hole. This will be his first Jackson Hole address as Fed Chair, and he walks into Wyoming with a queasy bond market, inflation still above target, oil above $90, Treasury actively intervening in the long end and markets trying to figure out whether the Fed’s next move is a hike, a hold or eventually a cut.
Don’t split town just yet, this could get interesting.
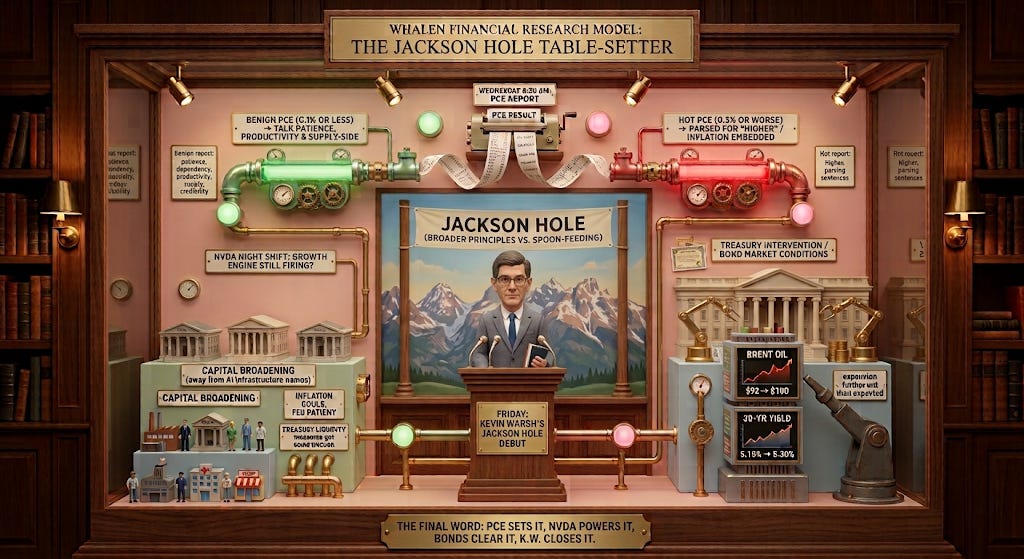
Warsh has intentionally avoided giving the market much forward guidance since taking over, preferring to talk about broader policy principles rather than spoon-feed investors the next three FOMC decisions. I approve personally, but that doesn’t mean a market starved for clues does.
Give him a benign inflation report Wednesday and he can talk about patience, data dependency, productivity, supply-side improvements and the importance of maintaining credibility without sounding like a hike is coming next month.
Give him a hot PCE print and suddenly every sentence gets parsed for the word “higher.”
And this is why Wednesday’s PCE sets the table. Nvidia tells us whether the biggest growth engine in the market is still firing. The bond market tells us whether financial conditions are cooperating. Oil tells us whether the inflation relief can last. And Warsh gets the final word on Friday.
What Luke Needs
From my perspective, I don’t think we need perfection this week, but I do think we need confirmation.
The best outcome would be core PCE around 0.1% to 0.2%, the two-year moving lower, the 10-year finally pushing convincingly back toward or below 4.60%, the 30-year moving toward 5.10%, the dollar remaining contained and Brent beginning to lose its grip on the $90s.
That’s my list to Santa anyways and this combination tells us the transmission mechanism is starting to work.
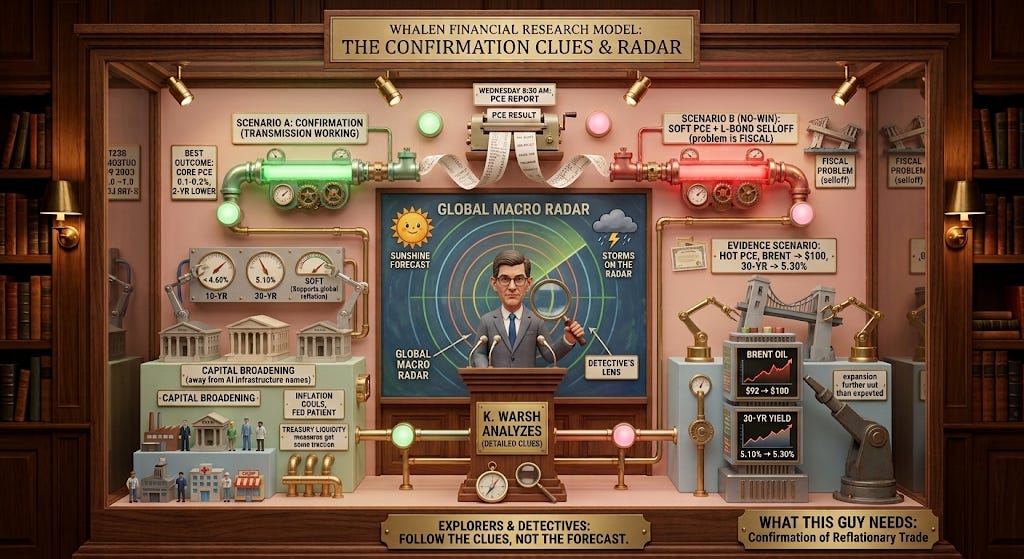
Inflation cools enough to keep the Fed patient, long rates begin cooperating, Treasury liquidity measures get some traction, the dollar stays soft enough to support the global reflation trade and capital can continue broadening away from the handful of AI infrastructure names that carried the first phase of this cycle.
The scenario I don’t want is a soft PCE print followed by another long-bond selloff. That would tell us the problem isn’t monetary policy anymore but more fiscal.
And, if we get hot PCE, Brent pushing toward $100 and the 30-year heading back through 5.30% all at the same time, then I’ve got enough evidence to start questioning whether the reflationary expansion is again further out than I expected.
So this isn’t my base case, but explorers and detectives don’t marry the forecast, they follow the clues.
And this week is going to give us a whole bunch of them.
So if you’re planning to sneak out early, keep one eye on the sky. I’m still calling for sunshine, but there are definitely a few storms sitting on the radar.