


Howdy everyone, and happy Friday. So am I alone or is anyone else feeling some of the shifts taking place just below the surface of the economy? Now maybe this is just a bad case of indigestion, but I think the rest of 2026 and early 2027 are starting to take shape.
So grab your Tums and I’ll explain.
Everyone seems determined to turn Kevin Warsh into Paul Volcker, and if they’re not doing that they’re screaming about credibility. So let’s try to figure out what he’s actually telling us and, more importantly, what he can realistically do over the next six to nine months.

Today’s data showed America lost 23,000 jobs in July. May and June were revised lower by another 103,000 jobs combined, labor-force participation has fallen 0.7 percentage point since January and the unemployment rate ticked down to 4.1% from 4.2%, partly because fewer people are participating in the labor force. Now here’s the part that cuts against me, and I’d rather just say it out loud than have you find it yourself. Private payrolls actually rose 30,000 in July, while the entire negative headline came from a 53,000 decline in government jobs, with almost 50,000 of that coming from local government education. Those numbers can get pretty messy around the summer seasonal adjustments, so I’m not going to pretend one payroll report suddenly proves my entire argument.
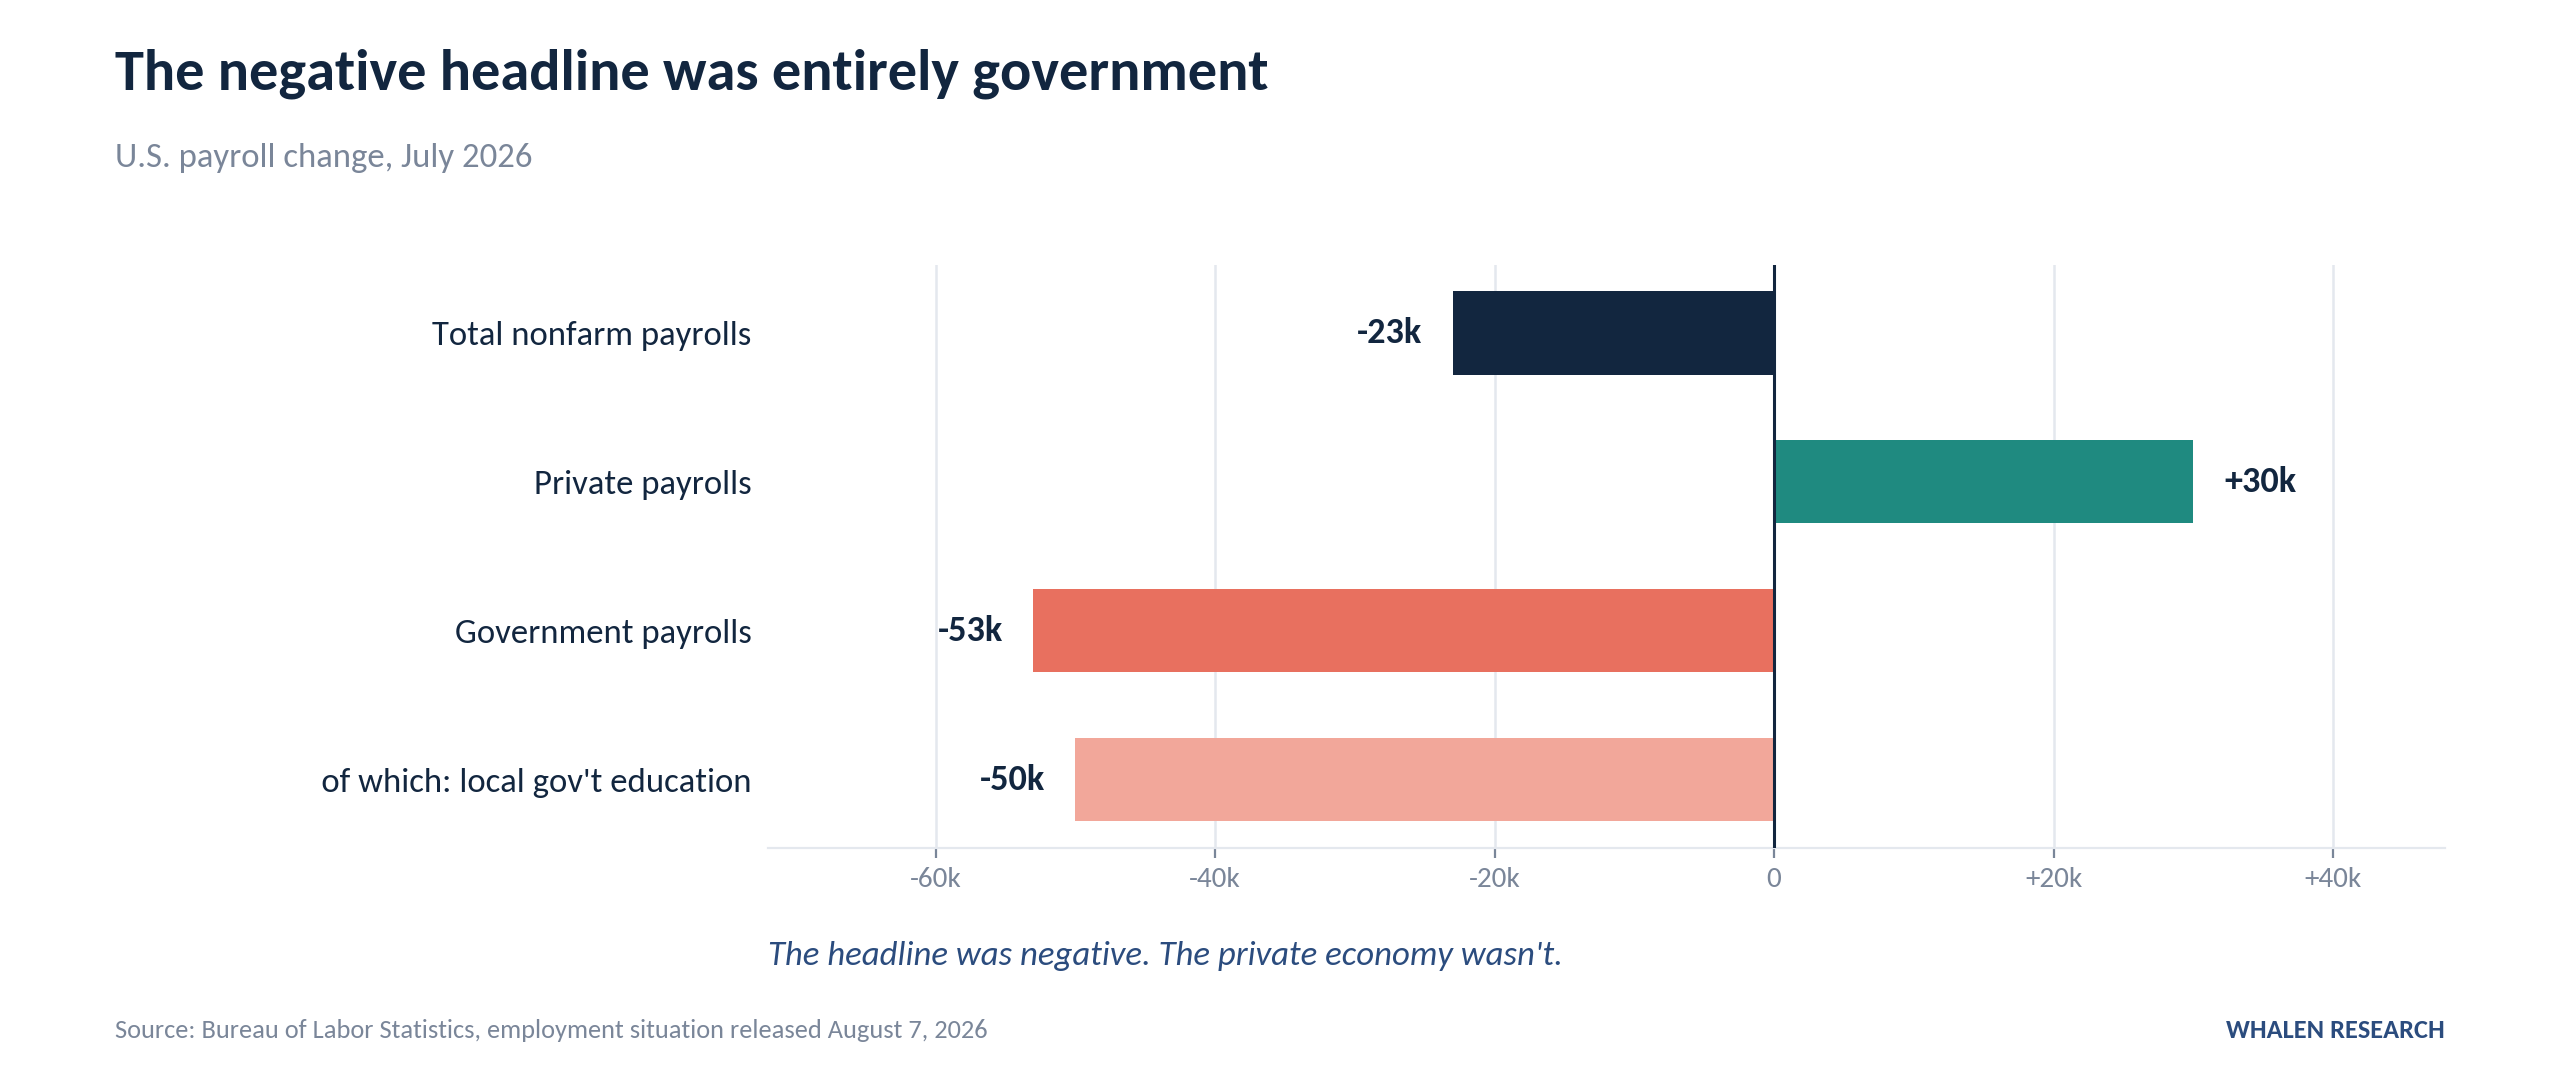
Now this doesn’t mean the economy is falling apart, but it does mean the idea that Warsh can simply march on into September, hike rates, drain liquidity and begin dismantling the post-2008 monetary system looks a little more complicated or, frankly, impossible at this time. We also get another employment report eleven days before the September meeting, so this story still has another chapter before Warsh actually has to make the call.
However, I don’t think tightening everything at once was ever the plan, at least for the next six to nine months. I don’t think Warsh is preparing to slam the brakes on the entire economy. I actually think he’s trying to build a bridge between the financial system we have today and the one he eventually wants, and that’s a pretty big difference for us as investors because if I’m right, the next phase of this market shouldn’t simply be another round how high will AI fly. Leadership should broaden toward the banks, industrial infrastructure, automation, strategic materials, quality smaller companies, selected consumer names and overseas markets.
So in other words, that’s from Wall Street toward Main Street.
The economy has to hum first
I don’t think Donald Trump is trying to cool the economy. In fact, I think it’s quite the opposite.
He believes America can grow its way through a good portion of its fiscal, political and affordability problems. He wants factories built, housing restarted, defense capacity expanded, energy produced, infrastructure upgraded and private capital pushed further into the physical economy, and that’s the Wall Street to Main Street agenda I’ve been talking about.
Warsh, on the other hand, appears to have a very different problem to solve. His longer-term intentions are becoming increasingly clear because he wants less dependence on the Federal Reserve, less forward guidance, more market price discovery and eventually a smaller Fed footprint. This man is doing some serious thinking about the architecture.
I believe he ultimately wants a Fed that acts more like the backstop and less like the star of every financial-market production, and while I agree much of Warsh’s sentiment, I simply don’t think he can get there yet.
You can’t remove the scaffolding before the building can stand. More importantly, you probably can’t ask the private sector to finance a massive industrial buildout while simultaneously raising rates, restricting credit, shrinking liquidity and forcing banks to absorb more Treasury issuance. The economy has to hum first, and today’s jobs report made that argument considerably more interesting.
Three FOMC members voted to raise rates by 25 basis points at the July meeting, while Warsh held the line and kept the federal funds rate at 3.50% to 3.75%. After this morning’s payroll report, the market cut the probability of a September hike pretty sharply, but I think the more interesting part is what the market is still pricing. Investors are basically arguing about whether Warsh hikes or holds, while I’m sitting over here telling you I think the next move eventually goes the other direction.
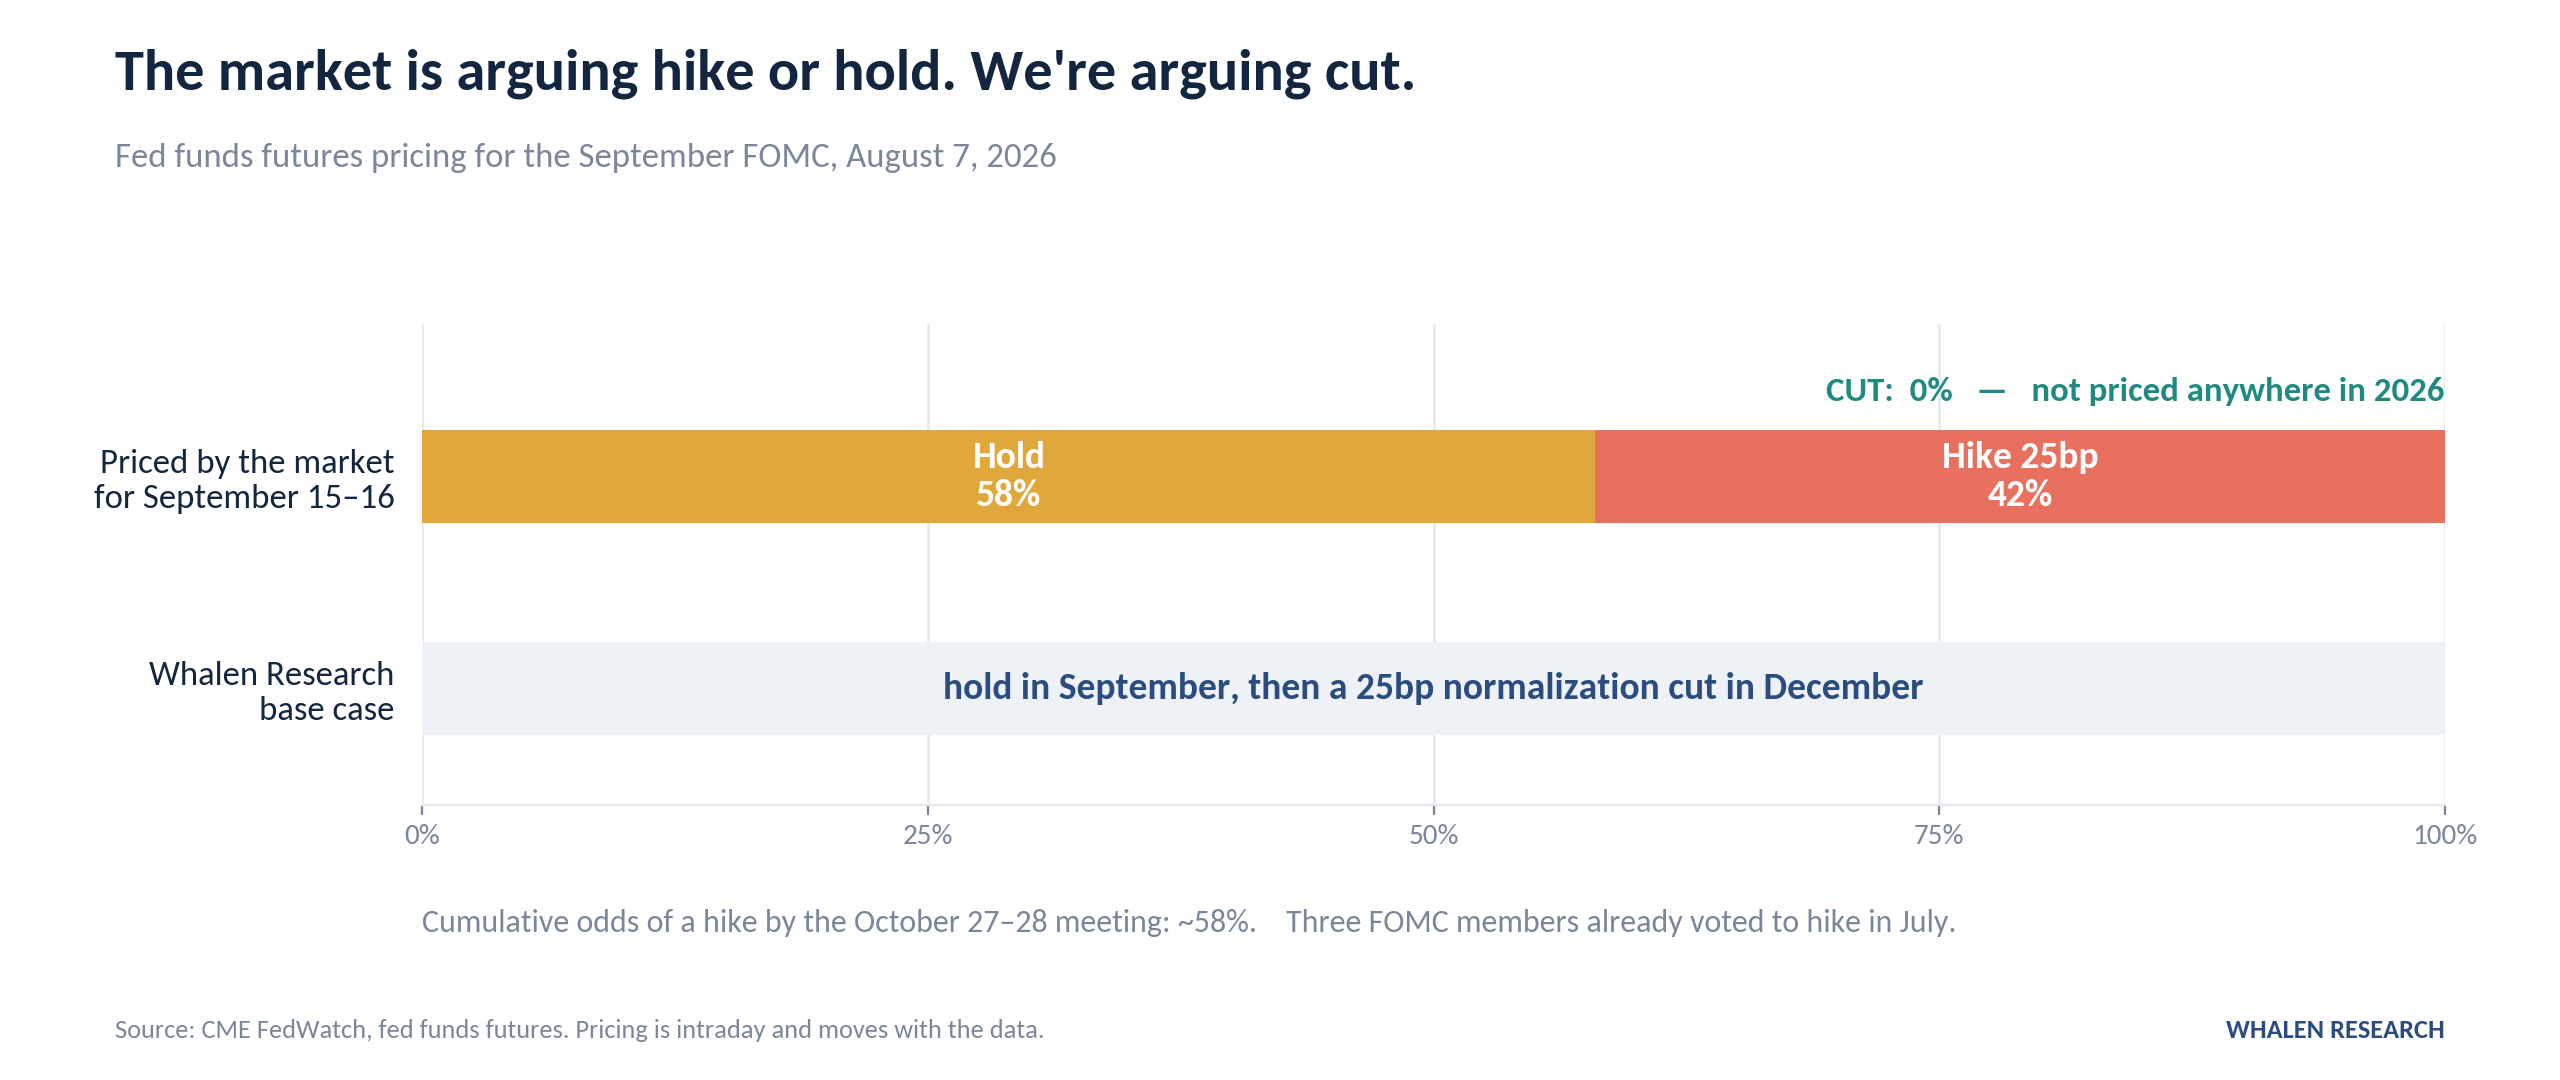
So I’m not shading consensus by 25 basis points. I’m standing on the other side and I’m not changing. My base case remains no September hike.
Oil is the bridge
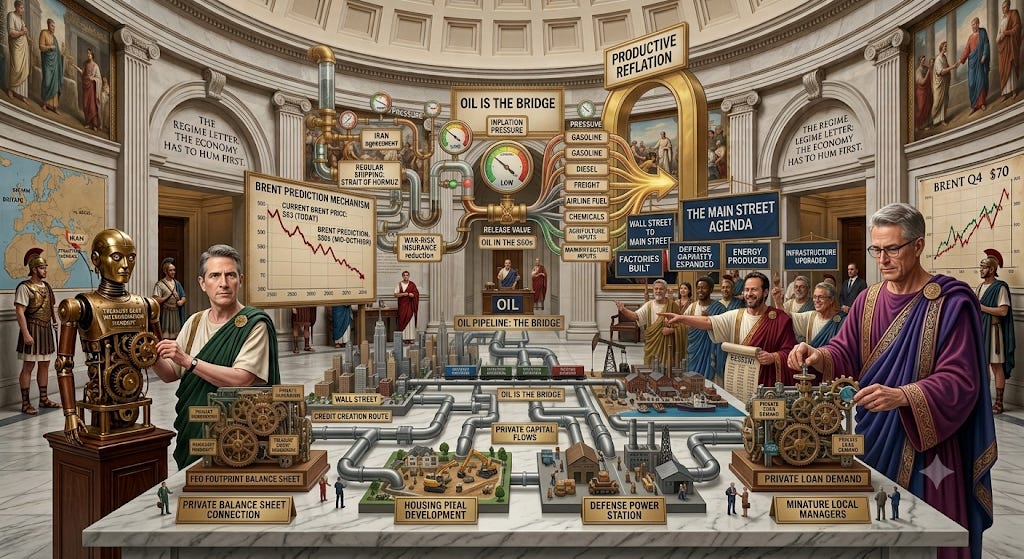
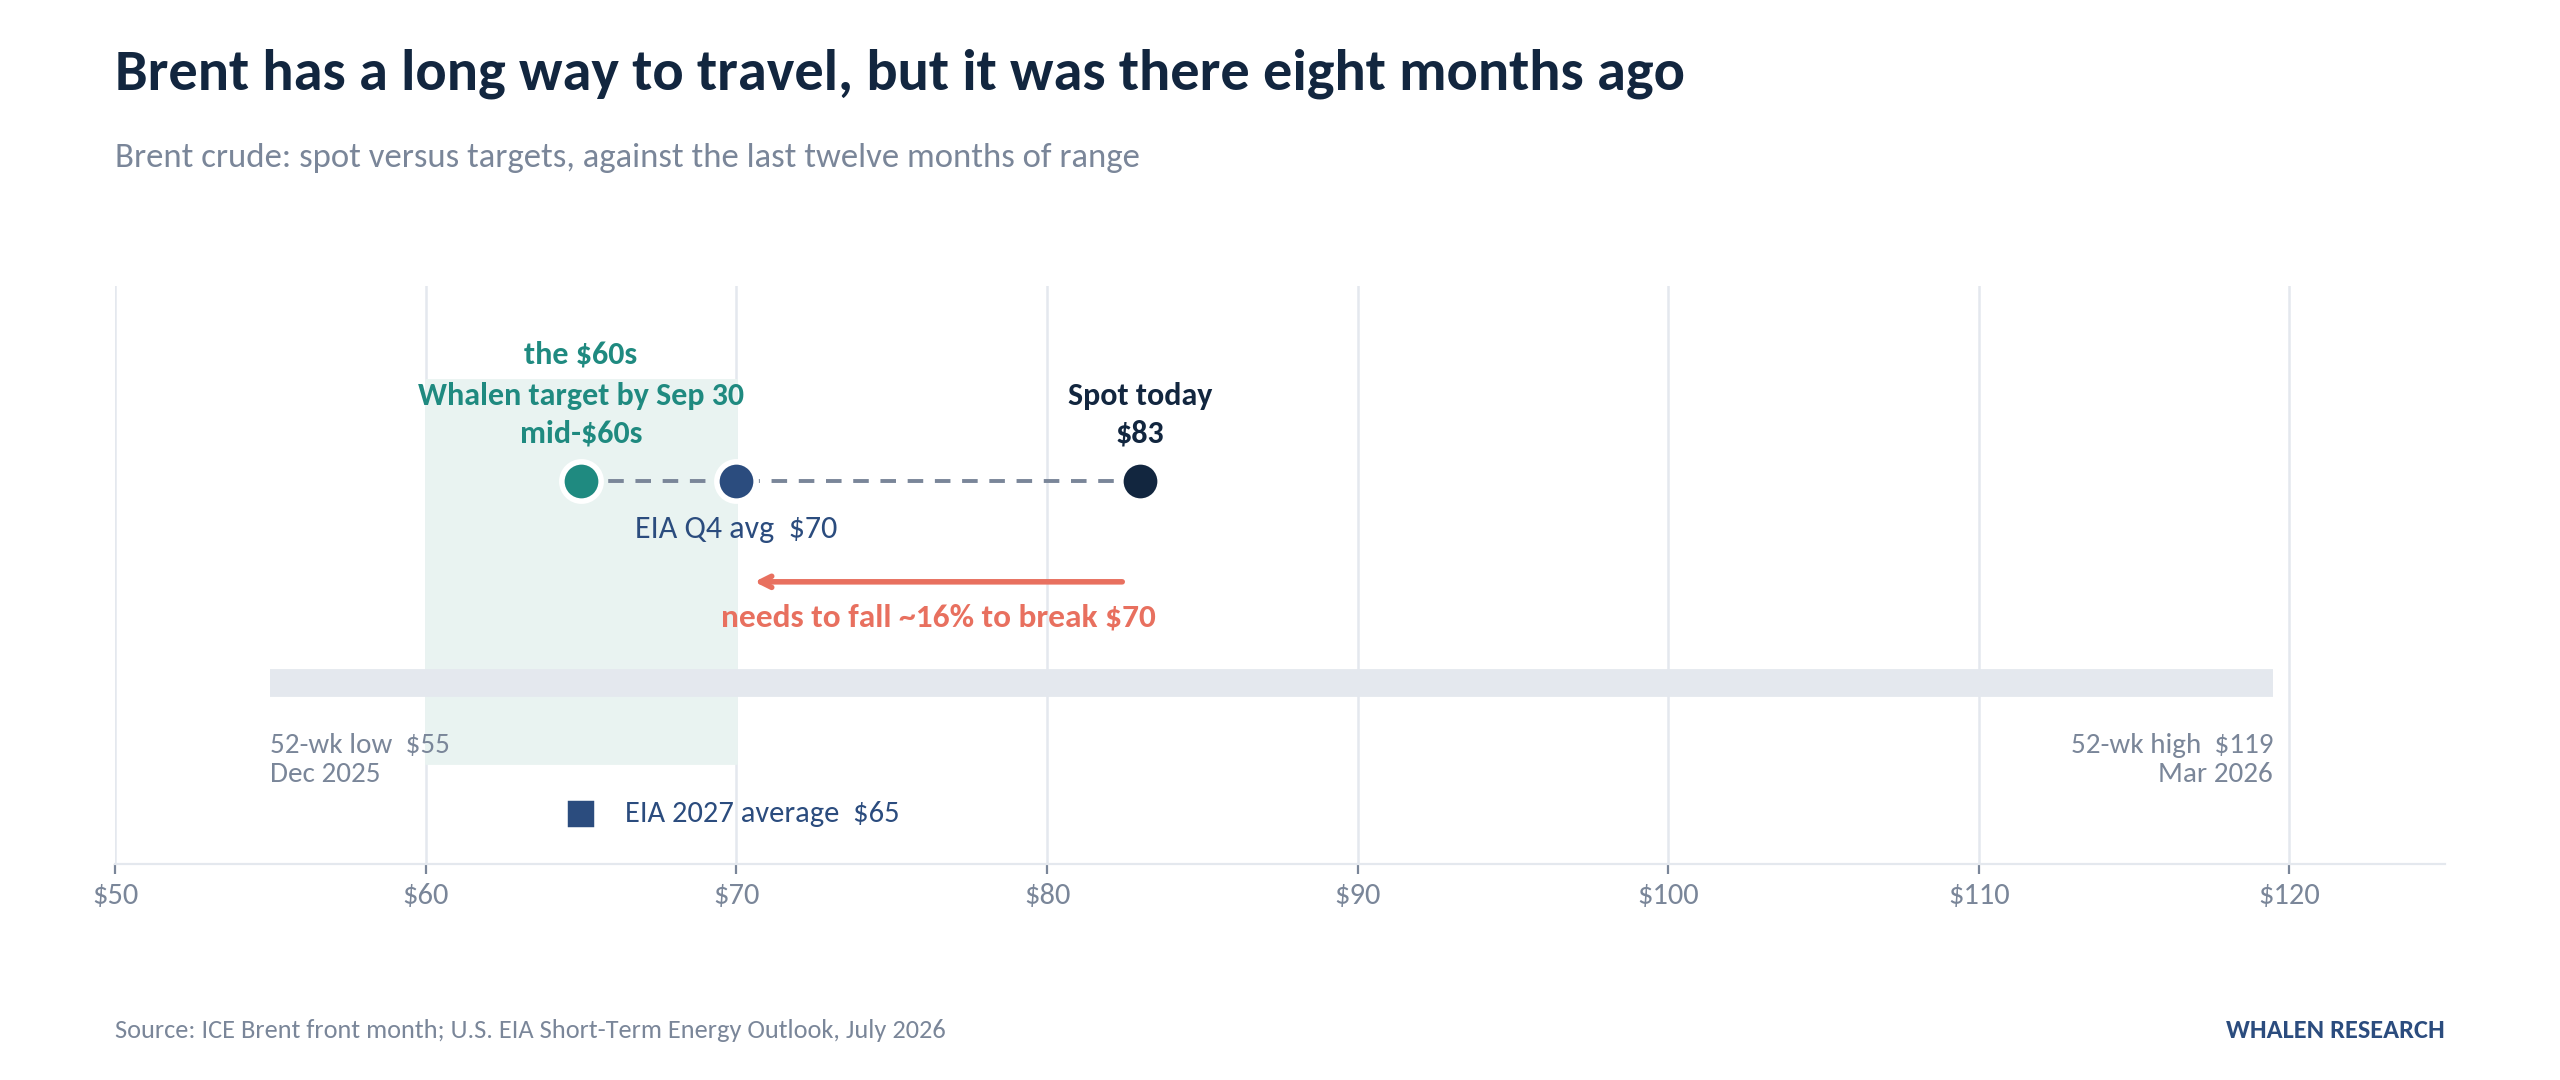
Brent is back around $83 as I write this, which makes my call look a little more obnoxious than it did three days ago and that’s fine. If crude were already trading at $68, there wouldn’t be much of a call left to make.
My base case remains that Brent reaches the mid-$60s by September 30, with October as the fallback. From roughly $83 today, it needs to fall about 16% just to sneak underneath $70, and I get it, that’s a serious move, but I also believe it’s entirely possible if we get a credible Iran agreement, regular shipping through the Strait of Hormuz and a meaningful reduction in war-risk insurance. And yes, I did say this a few months ago, but this time….
We’ve already seen what happens when the market smells peace. Crude dropped sharply Monday after Trump backed away from additional strikes and hopes for an agreement increased, then came roaring back as those negotiations became less certain and Iran considered restrictions on U.S. and Israeli vessels moving through Hormuz. That little round trip tells us there’s still a hell of a geopolitical premium sitting in this oil price.
I’m not the only one seeing the same directional setup. The EIA expects Brent to average roughly $70 during Q4 and $65 during 2027 as production normalizes and inventories rebuild. My disagreement isn’t really about where oil ultimately goes, it’s more about timing because I believe a credible agreement can pull some of that decline forward.
And this is where oil becomes about much more than just oil. Reshoring, defense spending, infrastructure, AI, housing and power investment all create the same annoying timing problem because demand arrives first while productivity arrives later. You gotta have workers, electricity, copper, aluminum, steel, concrete, trucks, financing and equipment before the shiny new factory produces its first widget, and that can create inflation before it creates additional supply.
Oil in the $60s becomes the release valve as lower crude feeds into gasoline, diesel, freight, airline fuel, chemicals, agriculture and manufacturing inputs. It relieves pressure on headline inflation and eventually inflation expectations while reducing costs throughout the physical economy, and that gives the investment cycle time to breathe.
Why Las Vegas matters
Trump was just down the road from me in Las Vegas on Wednesday selling the economic agenda and particularly the tax relief aimed at working Americans, including no tax on tips. I don’t think that trip was just another political speech, I think it was a preview of the midterm campaign.
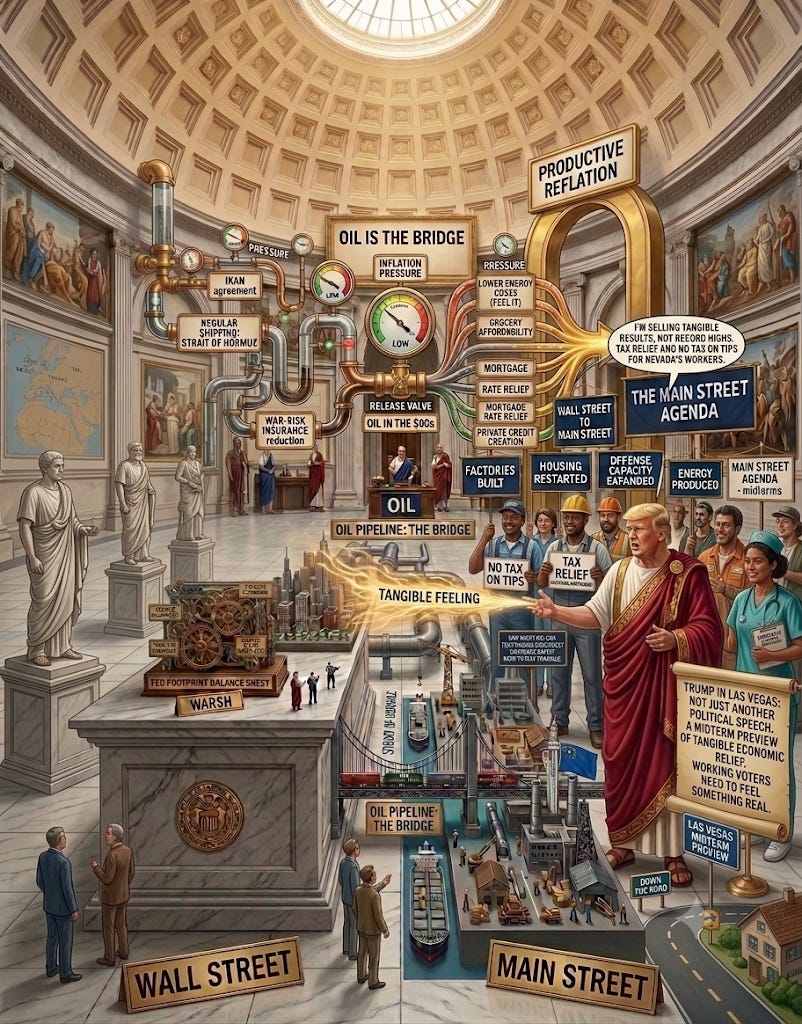
Trump knows that telling someone the S&P 500 is at a record high doesn’t help much when they’re financing groceries on a credit card or trying to buy a house with a mortgage rate starting with a six or seven. What Trump needs is working voters to feel something tangible.
Tax relief helps, and here in Nevada no tax on tips is particularly easy to sell, but tax policy is complicated, comes through a tax return and isn’t something most people see every morning on their way to work. Gasoline is, and the price is sitting right in front of them on a big sign every day, which makes lower energy especially powerful politically.
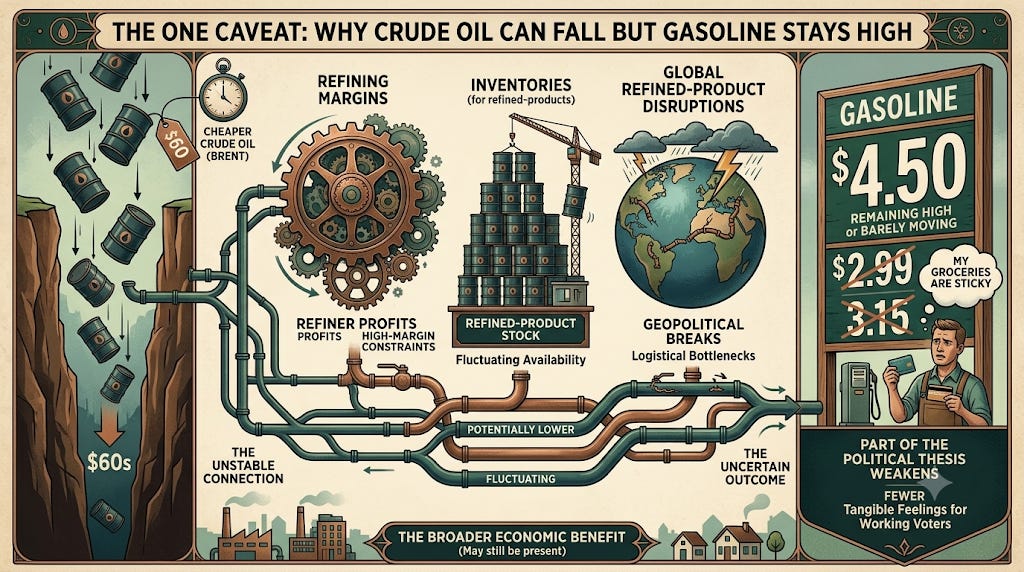
There is one caveat here that’s worth watching because cheaper crude doesn’t always flow directly into cheaper gasoline as quickly as we’d like. Refining margins, inventories and disruptions in the global refined-products market can keep gasoline elevated even when Brent starts falling, so I’m not just watching crude. If Brent falls into the $60s but the number on the sign at the gas station barely moves, part of my political thesis gets weaker even if the broader economic benefit from cheaper energy is still there.
Here is my interpretation of Trump’s desired sequence:
End or de-escalate the Iran conflict
Get shipping moving through Hormuz
Push oil and gasoline lower
Sell tax relief alongside falling household energy costs
Then make the argument that America can afford to invest, build and grow again
That’s a considerably stronger midterm message than asking voters to admire their 401(k).
The Warsh contradiction
Ok, so here is where things get a little more interesting, and where I think you need to read between the lines because Warsh’s destination may indeed be normalization, but his current job may be preparing the economy and financial system to survive it. And that, is two entirely different things.
On one hand, you’ve got the Fed still operating inside an ample-reserves framework and thinking seriously about what a smaller footprint could eventually look like. And the people closest to it don’t sound like they’re expecting anything fast, because at the Treasury borrowing committee meeting this week primary dealers said they expect the ample-reserves regime to stick around and specifically cited uncertainty about where Warsh’s balance sheet task force lands as a reason to wait. That task force was given six months, with preliminary findings expected as early as September and final recommendations by year-end, which means the review of the architecture isn’t even finished until roughly the moment I’m expecting him to cut.
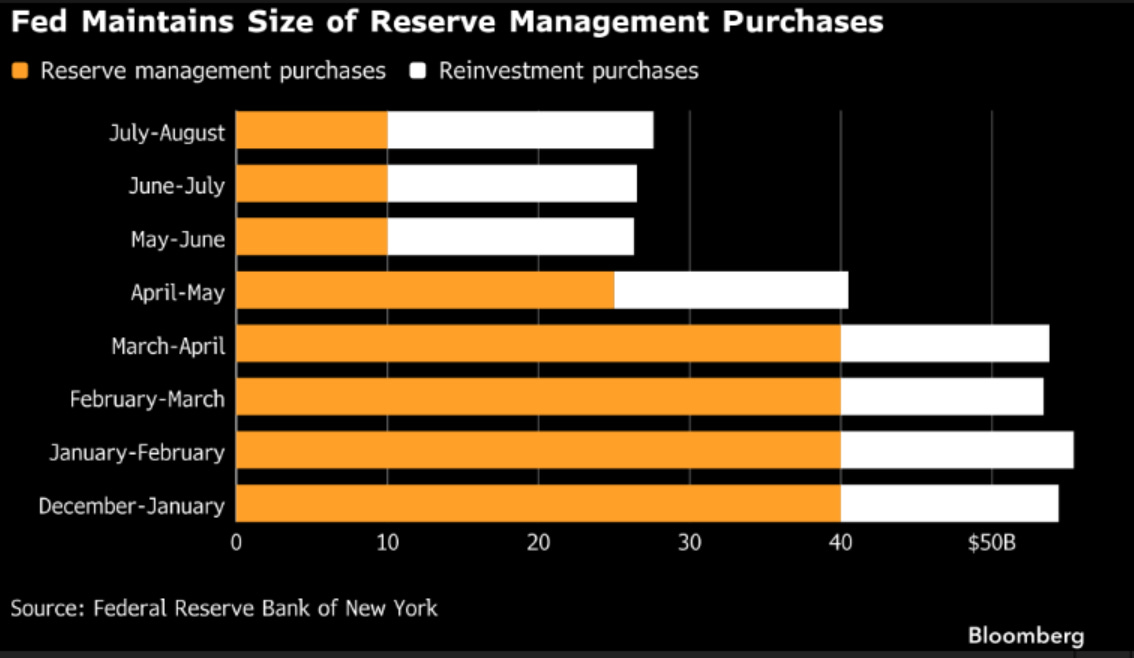
So what this means is there’s a huge difference between Warsh believing the Fed is too big and Warsh believing it needs to become smaller immediately. He can believe in a smaller Fed without believing it should happen next Thursday, and if he tries to force that transition before private lending strengthens and Treasury markets gain enough balance-sheet capacity, he risks creating almost everything Trump doesn’t want heading into 2027:
Higher long-term yields
Tighter credit
A stronger dollar
Weaker housing
Slower capital investment
A Treasury or repo incident
That’s why I’m less interested in what Warsh says the finished house should look like and more interested in watching how he builds it. Jackson Hole later this month becomes another important checkpoint because Warsh has deliberately reduced the amount of forward guidance coming from the Fed, so anything he gives us there about the balance sheet, liquidity or the broader framework is going to be worth reading pretty carefully.
Follow the money
This may be the most important part of my thesis because the regulatory groundwork is being laid for the large banks to carry more of the financial plumbing. Changes to the enhanced supplementary leverage ratio were designed to reduce the capital penalty large banks face when conducting lower-risk balance-sheet activities such as Treasury-market intermediation, and regulators estimated the rule could materially reduce Tier 1 capital requirements inside GSIB bank subsidiaries.
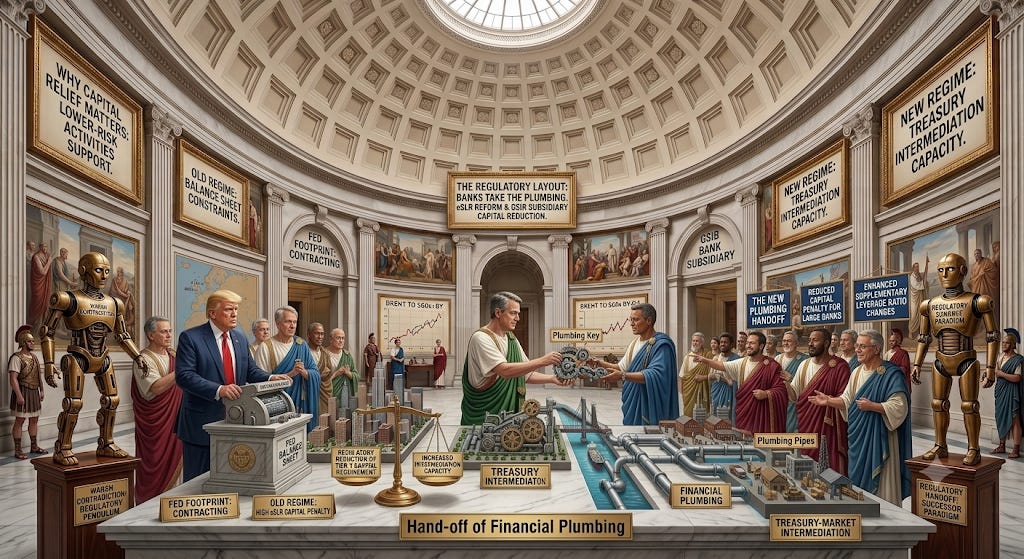
That doesn’t mean the banks suddenly found hundreds of billions of dollars, but it does create more balance-sheet flexibility. In May, Treasury’s borrowing advisory committee reported that dealers believed the changes had already allowed greater intermediation and that additional capital reforms could free more capacity for Treasuries and repo.
So that’s clue number one. Next, the Fed’s March survey of the largest U.S. banks showed 75% expected the eSLR changes to have no effect on their repo activity this year, while only 25% expected an increase, and that’s clue number two.
Now here’s where I think we need to be careful with clue number two because that 75% sounds a lot more dramatic than it really is. The question only went to eight U.S. GSIB respondents, which means I’m talking about six banks saying they expected no change, and the survey was taken before the new rule had even had much time to work. That doesn’t mean the reform is going to transform the system, but it also means I’m not ready to declare it a failure based on six banks filling out a survey before we even get started!
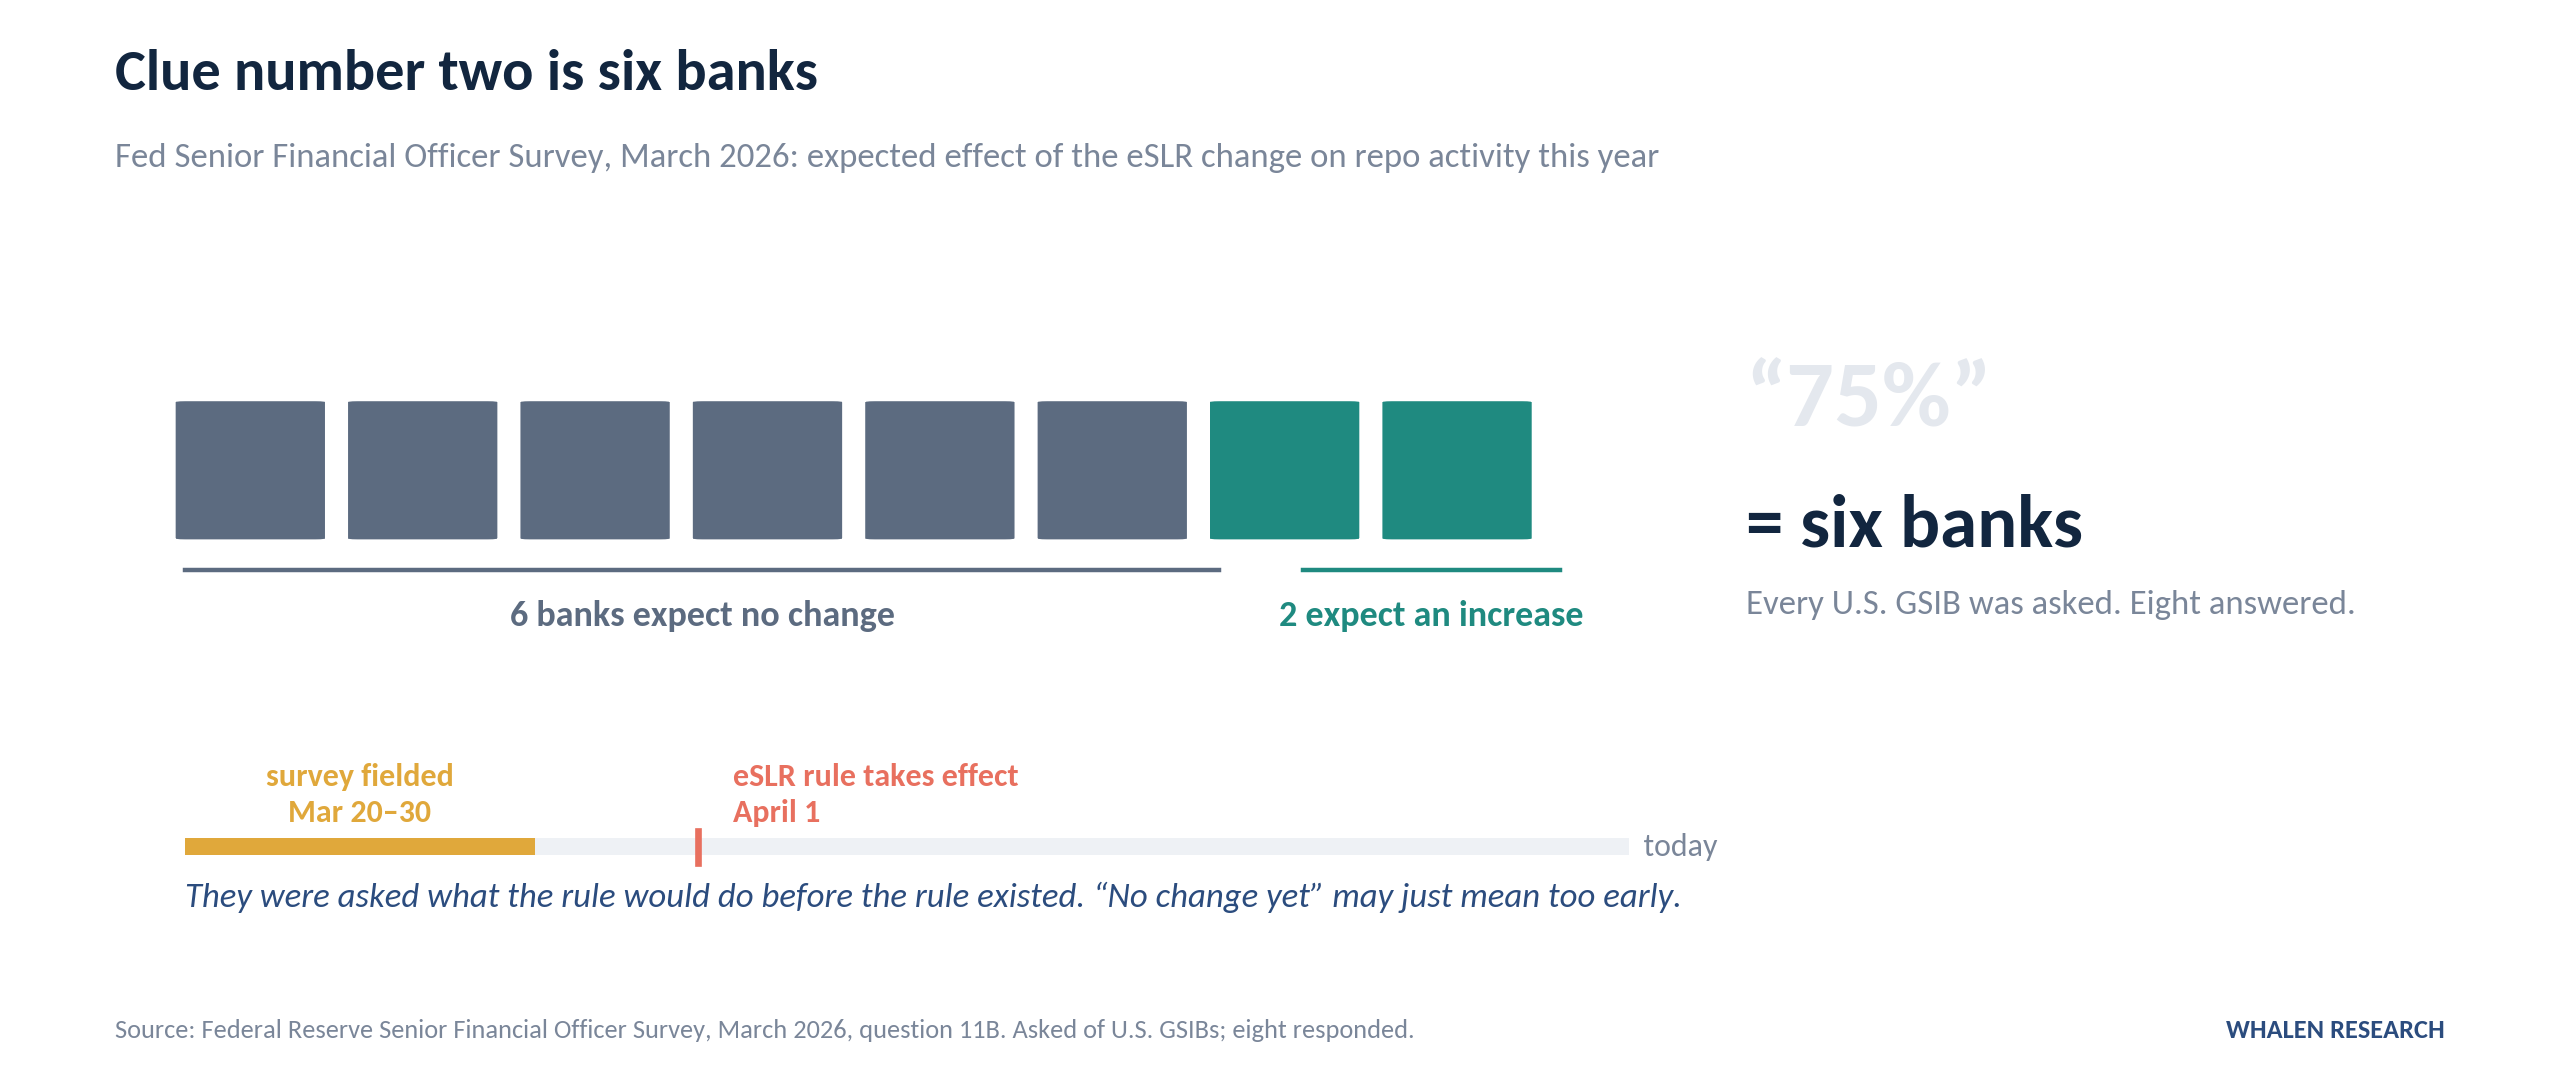
What we have right now isn’t proof of a completed liquidity handoff, but rather the beginnings of one. The regulatory capacity is appearing, Treasury dealers believe it should help, and now we need to see whether the banks actually use it.
The system Warsh may be trying to build looks like this:
The Fed provides the backstop
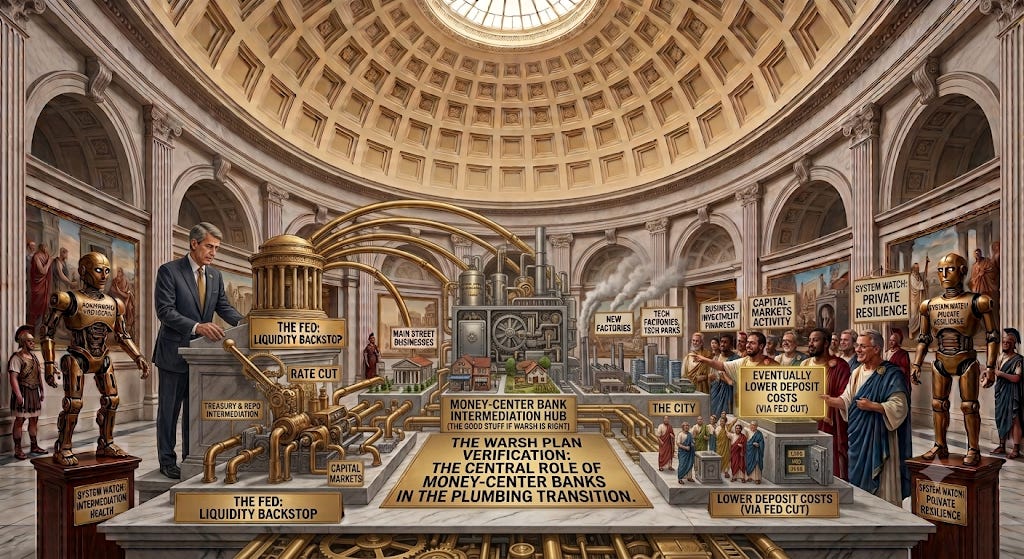
Money-center banks handle more Treasury, repo, underwriting and capital-market intermediation
Regional and community banks provide more local credit
Private credit and capital markets finance more business investment
Eventually the Fed can occupy less of the financial system because the private system is strong enough to carry more of the load
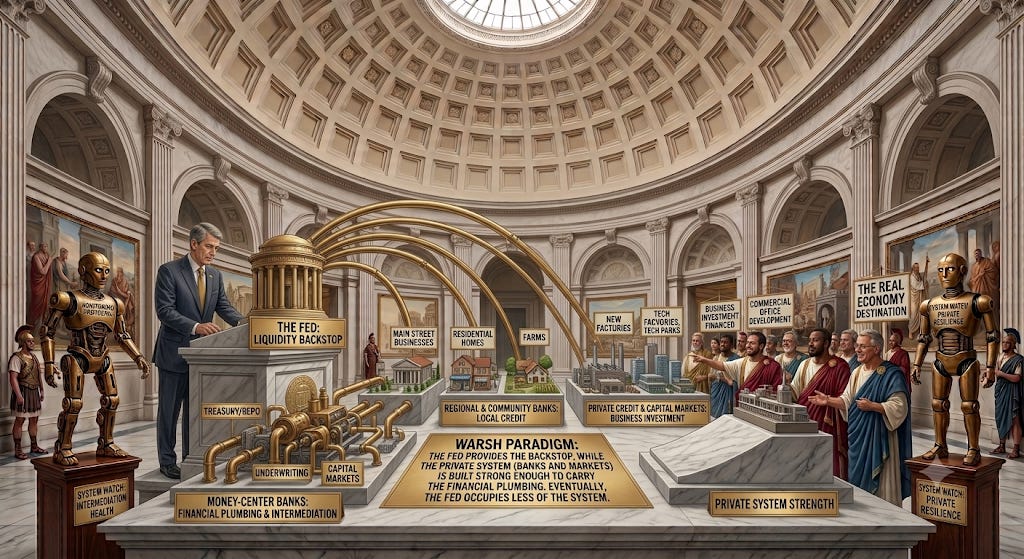
That’s my theory at least, but here comes the important part. Does the money leave Wall Street?
Because increasing JPMorgan’s ability to warehouse Treasuries isn’t the same thing as financing a machine shop in Ohio or an apartment project here in Vegas. The thesis becomes truly important when additional balance-sheet capacity turns into private credit creation and starts reaching factories, housing, infrastructure and smaller businesses, and that’s what I’m watching for next.
The Fed’s H.8 release gives us bank credit and commercial and industrial loan growth every Friday, and the Senior Loan Officer Survey gives us lending standards and actual loan demand every quarter, with the next one landing in October. If balance-sheet capacity is genuinely turning into private credit creation, it shows up in those two places before it shows up anywhere else. If those series stay flat while the Treasury market quietly gets healthier, then I got the plumbing right and the destination wrong.
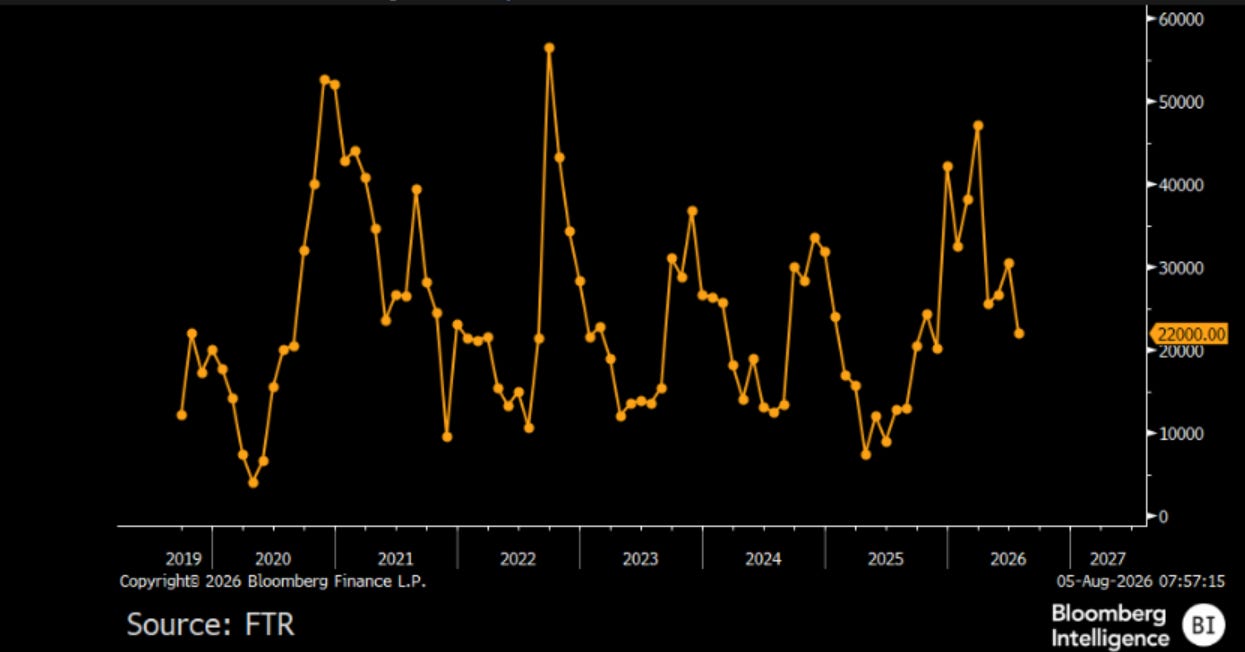
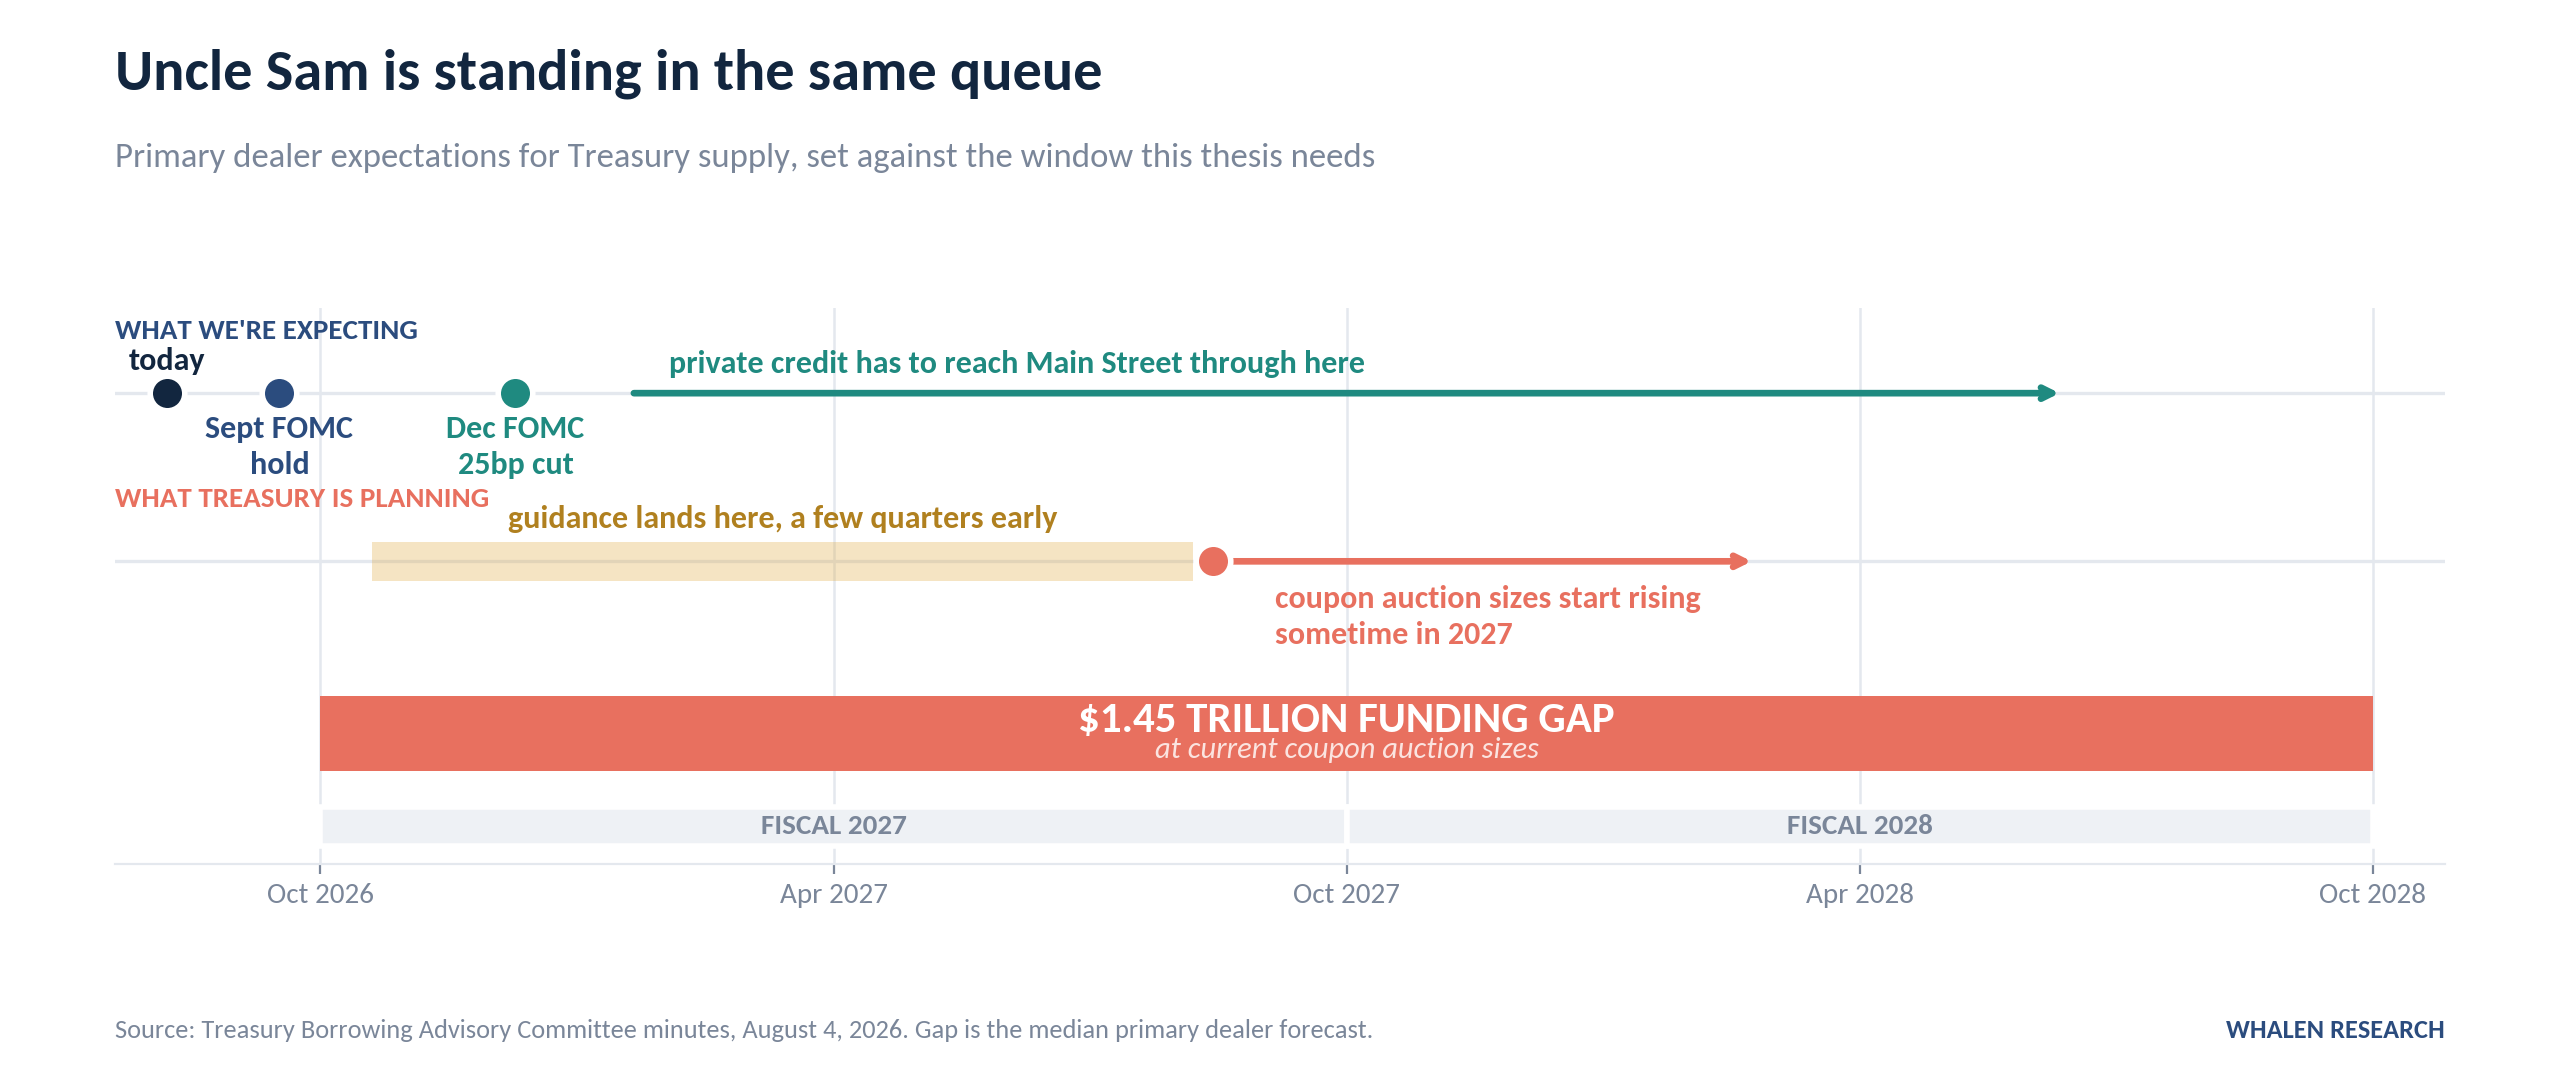
There’s also a pretty obvious risk here because Uncle Sam wants access to the same balance sheet. Treasury’s borrowing committee met Tuesday and the minutes came out Wednesday, and the median primary dealer forecast implies a $1.45 trillion funding gap across fiscal 2027 and 2028 at current coupon auction sizes, which means the additional capacity I’m hoping eventually reaches Main Street may get swallowed up by Treasury issuance first. Those same dealers expect Treasury to start raising coupon auction sizes sometime in 2027, with the forward guidance about it probably showing up a few quarters ahead of the actual increase, so this isn’t some vague worry sitting way out on the horizon. It’s on the calendar, and the announcement likely lands while this thesis is still trying to work.
One more thing before I move on, because I think I’ve been sloppy about this in previous letters. The oil call and the plumbing call are two completely different trades running on two completely different clocks, and I shouldn’t be presenting them like they rise and fall together. Brent in the mid-$60s by September 30 is a 54-day, 16% move that depends on Iran, Hormuz and war-risk insurance, and I have no particular edge on Middle Eastern diplomacy, so that one carries a lot of variance and you should treat it that way. The liquidity handoff is a two to three year structural story built out of capital rules, dealer balance sheets and whether private credit actually shows up, and it’s the part where I think the work I’m doing is worth something.
So if Brent is still sitting at $80 in the middle of October, the oil call is wrong. The plumbing call isn’t, it just gets slower and the December cut probably becomes a March cut. So please, don’t grade those two on the same scorecard, because I’m not gonna.
Why I still expect a Q4 cut
Hopefully I’m not getting too far out there, but I’m still expecting a rate cut in Q4 2026. I’m not forecasting a cut because I think the economy is entering recession, I’m forecasting the possibility of a normalization cut because if energy inflation falls quickly enough while the nominal policy rate remains unchanged, the real policy rate rises and monetary policy effectively becomes more restrictive without Warsh doing a thing.
Warsh wouldn’t necessarily be stimulating the economy, he could simply be preventing falling inflation from tightening real policy at exactly the moment private investment needs room to expand.
The clean sequence still looks like this:
September should be a hold, particularly after today’s jobs report, although the inflation data and the next payroll report still matter enormously
Late September into October is the window where I think Brent can enter the $60s if we get an enforceable Iran agreement and regular shipping through Hormuz
October becomes interesting, although with the meeting sitting only days before the November election, Warsh has every reason to avoid doing anything that looks political unless the data forces him
That leaves December as the cleanest window for a 25-basis-point normalization cut
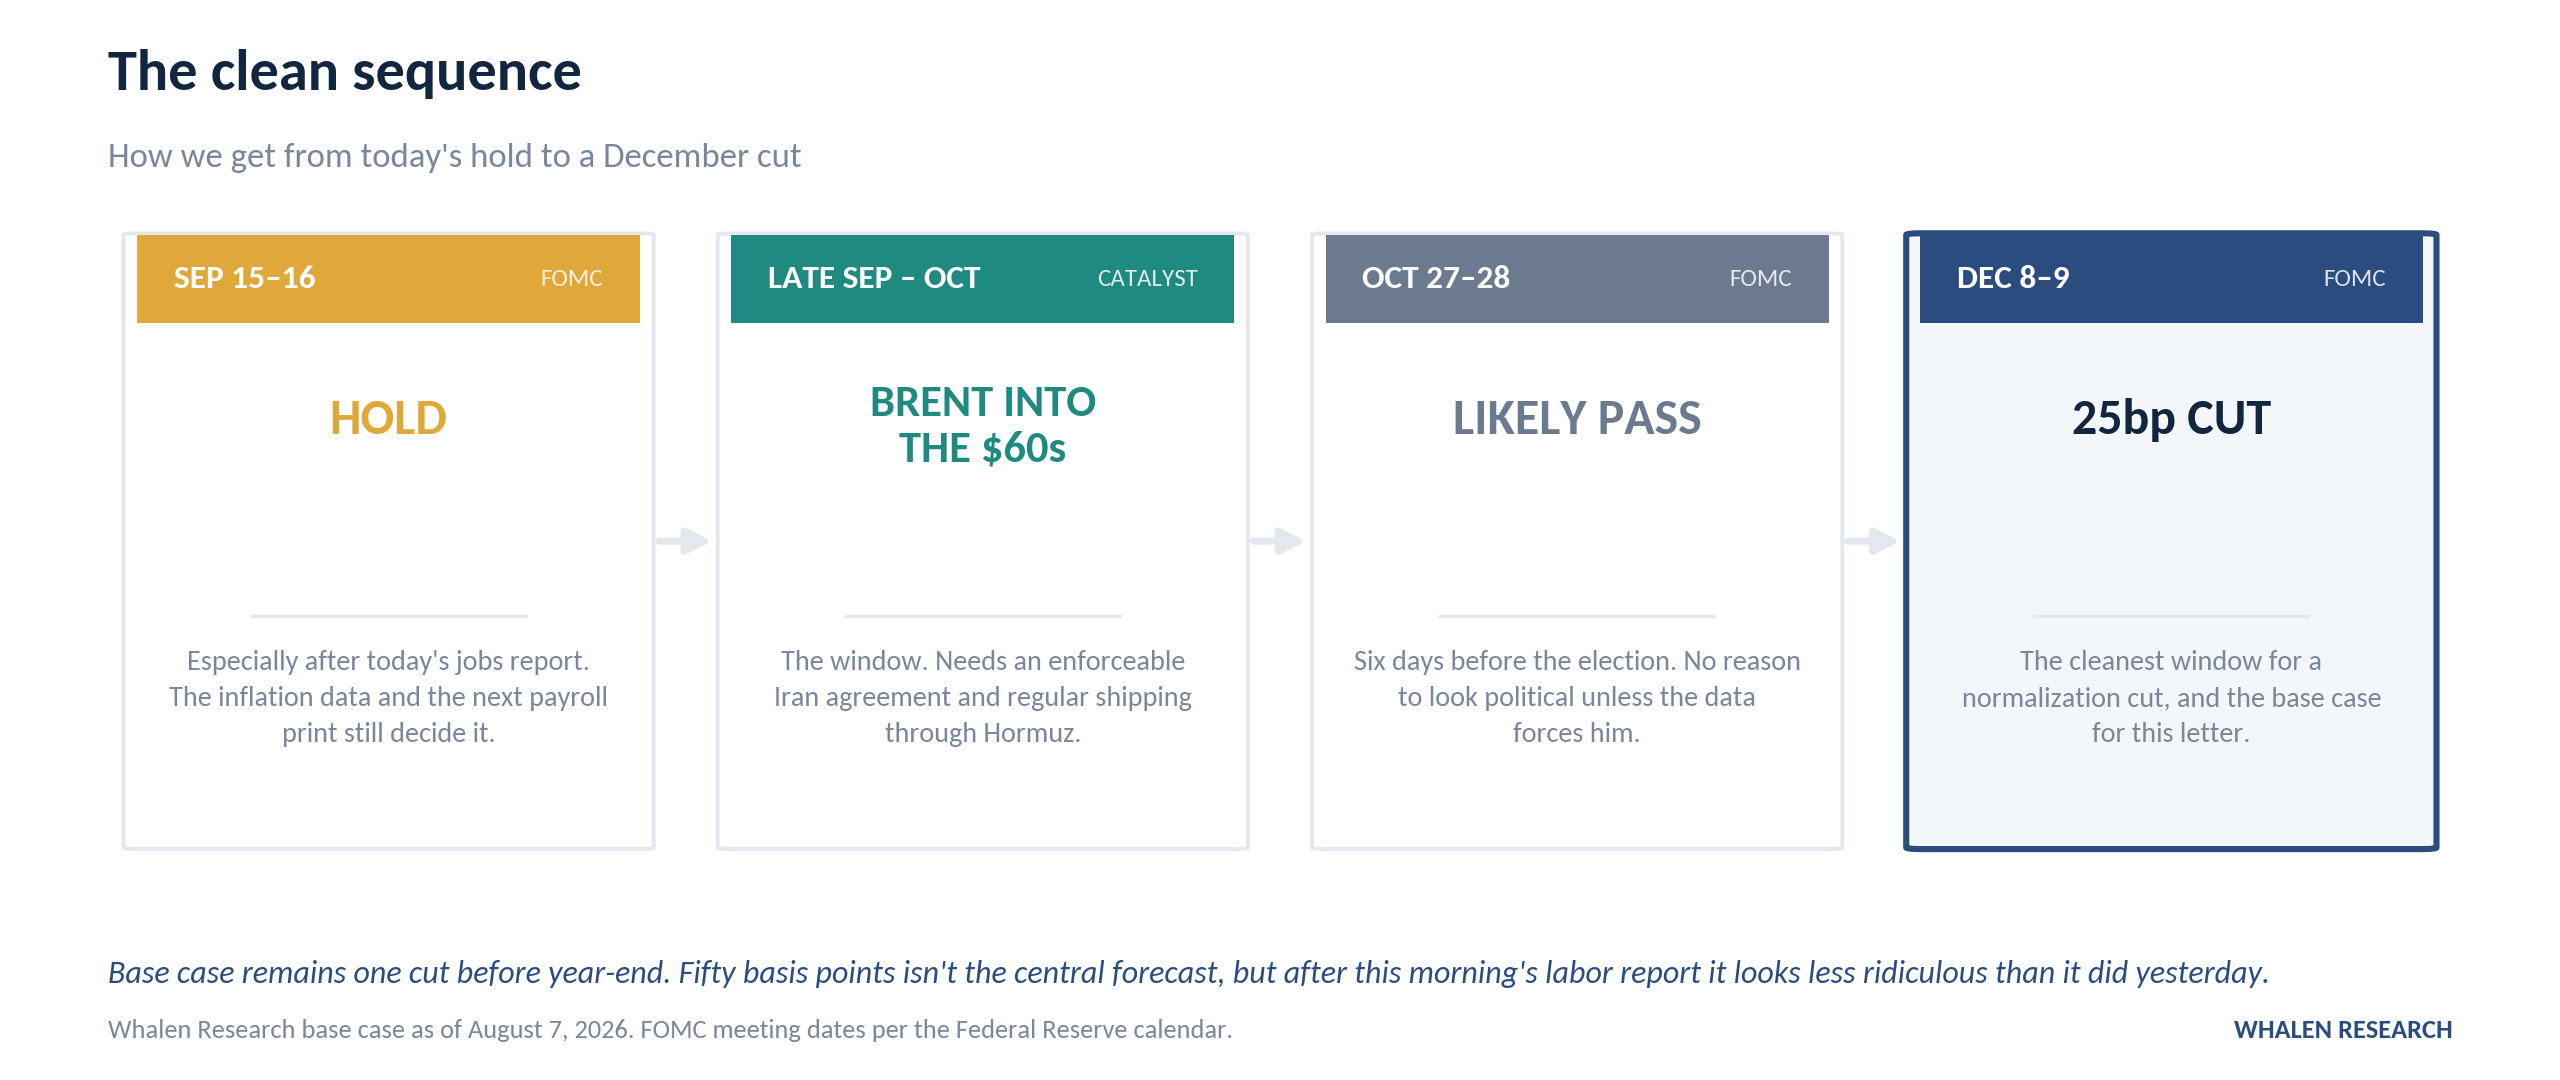
My base case remains one cut before year-end. Fifty basis points isn’t my central forecast, but after this morning’s labor report it certainly looks less ridiculous than it did yesterday.
I should also put the boring outcome on the table, because I don’t think enough people are talking about it and it might be the single most likely path. Warsh could just simply jsut sit there. No hike, no cut, 3.50% to 3.75% straight through into 2027, which is the baseline for a decent number of forecasters right now and would leave both the hawks and me looking a little silly. If that’s how it goes I don’t get my December victory lap, but most of this regime call still survives, because cheaper energy still helps households, the capital rules still free up bank balance sheet and the broadening still happens. It just happens slower and without any help from the Fed.
To get two cuts, though, we need more than cheap oil. We’d need several benign inflation reports, softer employment data, a declining two-year Treasury yield, a cooperative 10-year Treasury market and no renewed tariff or energy shock.
There are three meetings remaining this year: September 15 and 16, October 27 and 28, and December 8 and 9, so we have plenty of data between here and there to either confirm this thesis or make me eat it.
What works if I’m right
This is the good stuff if I'm right. The money-center banks remain one of my favorite expressions because they potentially sit directly in the middle of the plumbing transition and benefit from Treasury and repo intermediation, underwriting, corporate credit, capital-markets activity and eventually lower deposit costs if Warsh cuts.
Grid and power infrastructure still look appealing because reshoring doesn’t happen without electricity. I think they had front run much of the excitement, but factories, data centers, defense plants, robotics, housing and automation all need transformers, switchgear, transmission, cooling, power management, gas infrastructure and grid controls.
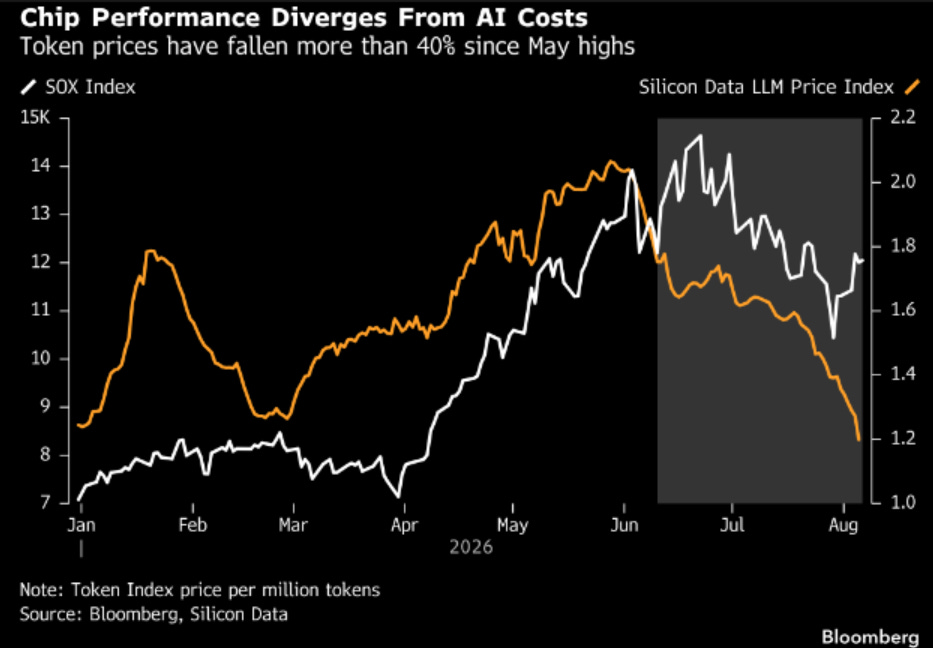
Software, industrial automation and edge computing are the next extension because the first phase of AI was about building the brain, while the next one increasingly becomes about putting that intelligence to work and actually producing an ROI in factories, vehicles, equipment, robots and supply chains. That should favor sensors, analog chips, connectivity, testing, motion control, factory software, productivity software and robotics rather than remaining completely dependent on hyperscaler capital spending.
Strategic materials remain essential because you can’t build a strong economy on intent alone. It takes copper, aluminum, steel, aggregates, specialty alloys and critical minerals, and lower oil helps many of those businesses by reducing diesel, transportation and processing expenses.
The consumer reacceleration trade should benefit too because lower gasoline functions like a small tax cut, particularly for lower and middle-income households, with airlines, restaurants, hotels, travel, entertainment, apparel and experiential spending among the areas I’m watching. I’d still stay selective because cheaper gasoline doesn’t magically erase rent, insurance or credit-card bills.
Quality small and mid-caps may ultimately be the purest stock-market expression of the Main Street thesis because lower financing costs, easier credit, domestic capital spending and stronger household demand all matter more to these businesses than they do to Microsoft.
Europe and emerging markets also become more interesting because lower oil is a terms-of-trade improvement for energy importers, while a softer dollar and less aggressive Fed reduce pressure on foreign currencies and dollar funding. That supports European industrials, emerging-market equities, selected Asian manufacturers and local-currency emerging-market debt.
And I still have a sweet spot for natural gas and midstream better than broad crude exposure because lower oil doesn’t change the structural demand for electricity, LNG exports, data centers, grid reliability and industrial gas infrastructure.
I also think high-quality gold miners may be more interesting than bullion if this sequence plays out because an Iran agreement can remove part of gold’s geopolitical premium, but if it also produces lower oil, lower yields and a weaker dollar, gold doesn’t necessarily have to fall.
The miners get another benefit because energy is a major input cost, which means a company can theoretically receive a still-supportive gold price while diesel, transportation and processing expenses move lower, creating operating leverage.
What probably doesn’t lead
Crude-oil producers and oilfield services become much less interesting if Brent really does move into the $60s because marginal producers lose economics, drilling budgets come under pressure and service pricing becomes harder.
Long-dollar trades also become less attractive if U.S. rates fall while international growth improves, while I’m not particularly interested in blindly loading up on 30-year bonds either because a Fed cut doesn’t guarantee the long end rallies when Treasury issuance and deficits remain enormous.
AI isn’t dead either, and obviously that’s not even close. If this thesis works, AI leadership should broaden from simply financing bigger data centers toward producing measurable productivity throughout the real economy, which means the next great AI trade may be what AI does rather than how much somebody spends building it.
Where I’m wrong
So what happens if I’m wrong and how will we know?
First, oil can reach the $60s for the wrong reason. Oil falling because Iran de-escalates and supply normalizes is bullish, but oil falling because global demand falls through the floor is not.
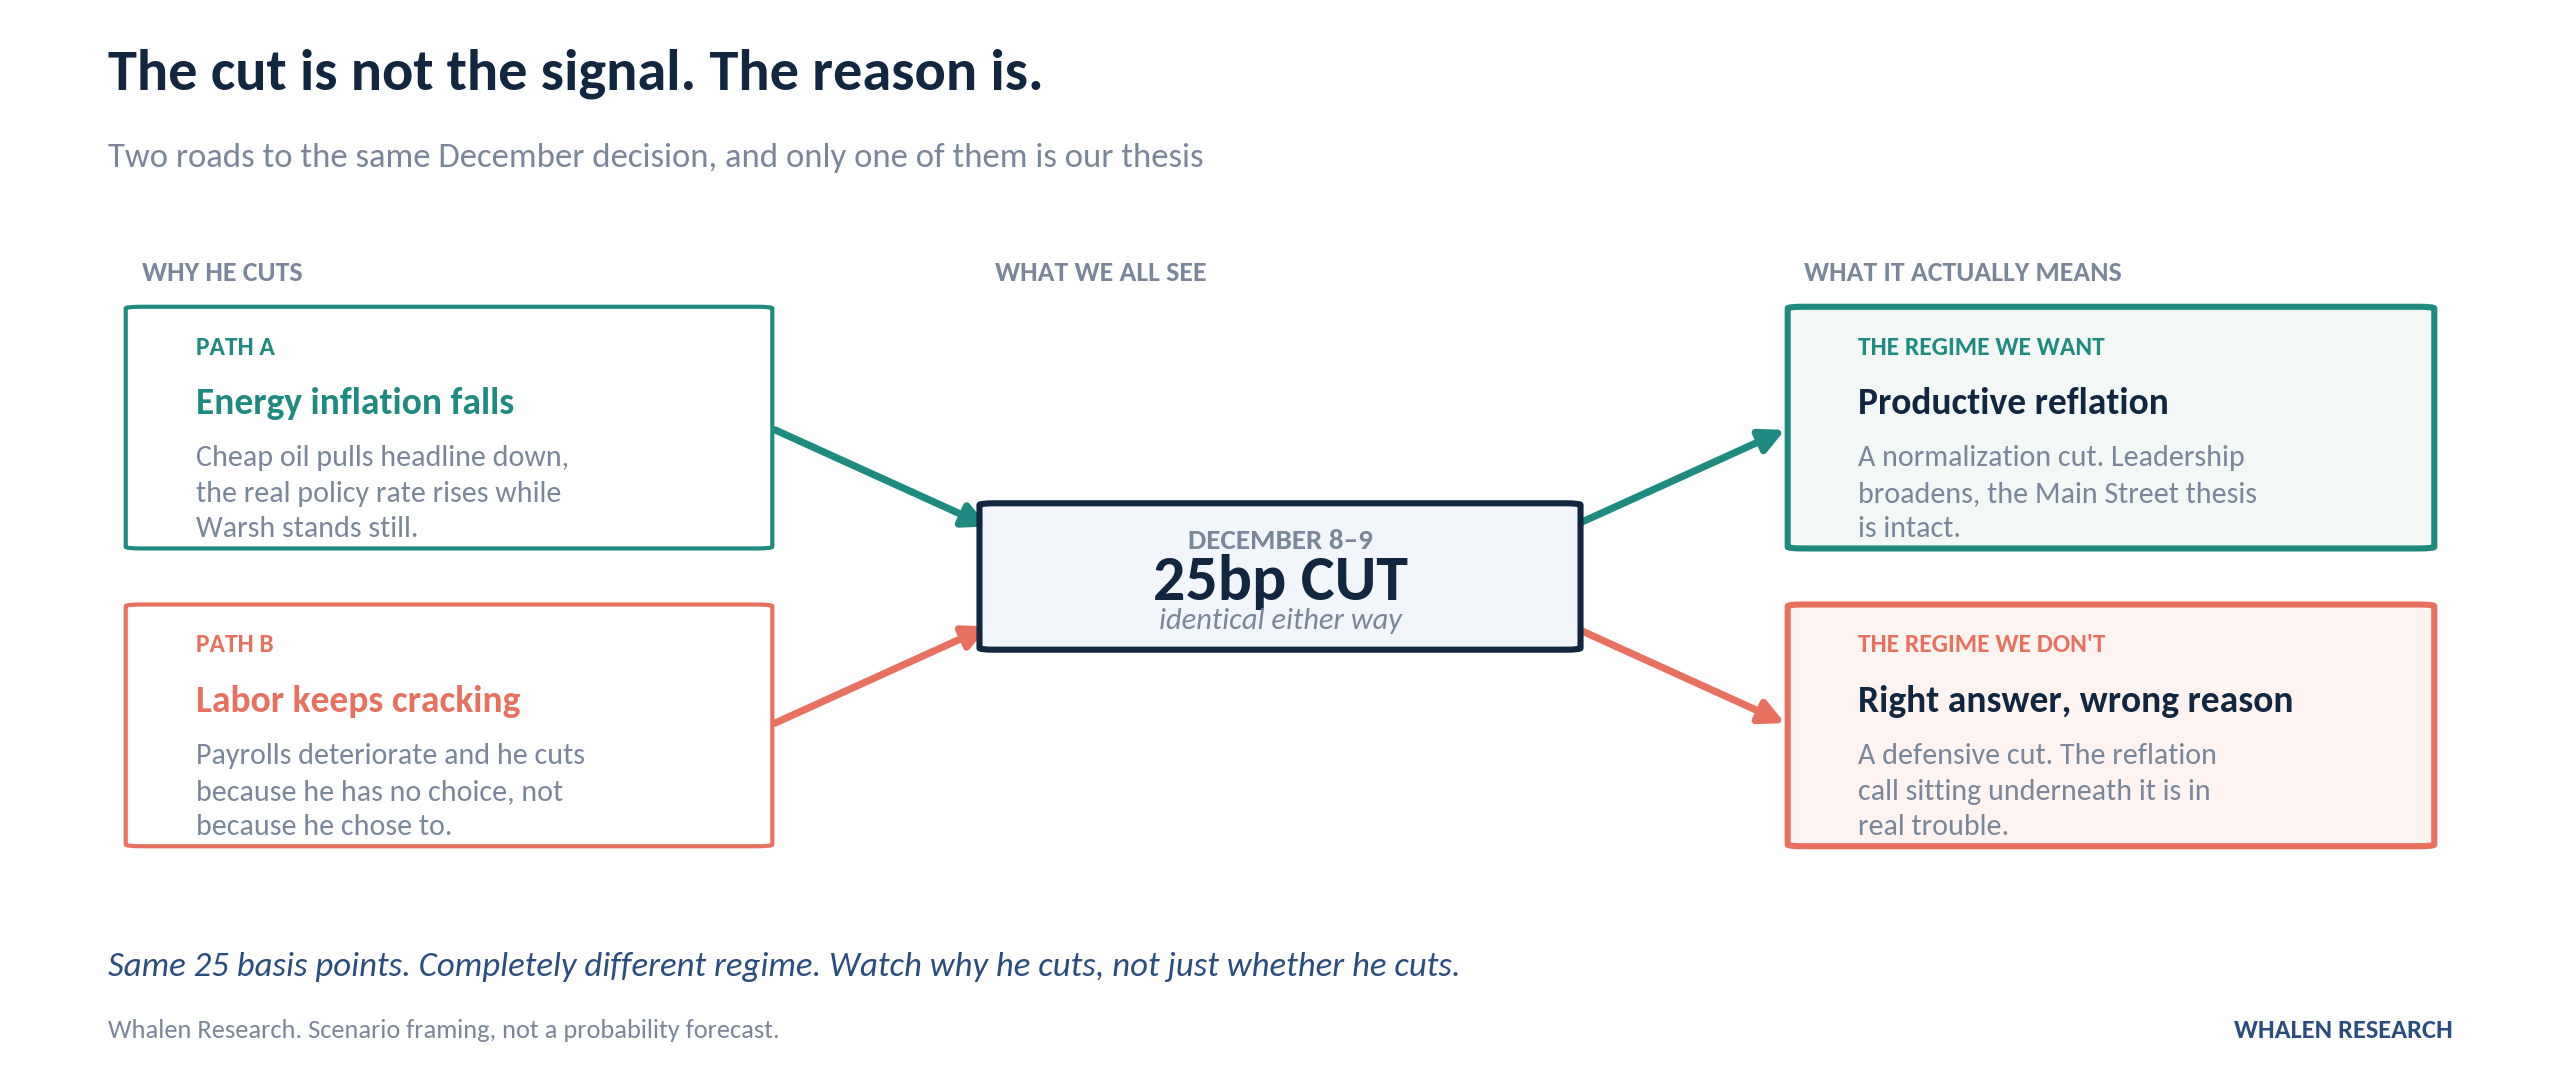
There’s also a version where I get the cut and still get the thesis wrong, and honestly it might be the more likely version of the two. I’ve been telling you Warsh cuts because falling energy inflation raises the real policy rate while he’s standing still, which is a tidy piece of arithmetic and makes me sound clever. The messier path is that he cuts because the labor market keeps deteriorating and he has no choice, and if that’s what gets us there then I got the right answer for the wrong reason and the reflation call sitting underneath it is in real trouble. Same 25 basis points, completely different regime. So watch why he cuts, not just whether he cuts.
There’s also the gasoline problem I mentioned earlier because Brent in the $60s doesn’t automatically mean pump prices fall as quickly as I want them to. If refining margins remain elevated, gasoline inventories stay tight or refined-product supply gets disrupted, crude can fall while consumers don’t feel the full benefit. The economic thesis would still work to some degree, but the political side gets weaker if the voter never actually sees cheaper gasoline.
Sticky core-services inflation could wreck the story too, as could another tariff-driven goods shock, renewed Iranian escalation, weak private loan demand or a failure of reshoring announcements to ever become actual equipment orders and hiring. Unfortunately, all of these are entirely possible.
The banking handoff could disappoint as well because it’s entirely possible Washington frees a bunch of bank balance-sheet capacity and Treasury issuance proceeds to devour everything in sight before Main Street gets there, which would leave us with a healthier Treasury market but not necessarily the private-credit expansion this thesis ultimately requires.
But there’s one signal I care about more than any other and that’s this: oil falls, Warsh stays put, and the 10-year Treasury rises.
If Brent moves toward $65, the Fed stays unchanged and the 10-year still pushes materially higher, that’s a warning that the long end isn’t validating the benign version of this thesis. Something else is overpowering the disinflationary benefit of cheaper energy, whether that’s fiscal concerns, too much Treasury supply, a rising term premium or renewed inflation expectations. That would weaken housing, pressure long-duration assets and interrupt the transmission mechanism I’m counting on.
And we actually got a small reminder of that this morning. The two-year fell about five basis points to 4.20% after the weak payroll report, while the 10-year fell only about two basis points to 4.64% and the 30-year was back around 5.21% after an initial rally. In other words, the front end responded much more aggressively than the long end. That isn’t my failure signal, not even close, but it’s exactly why I’m watching the long end so carefully.
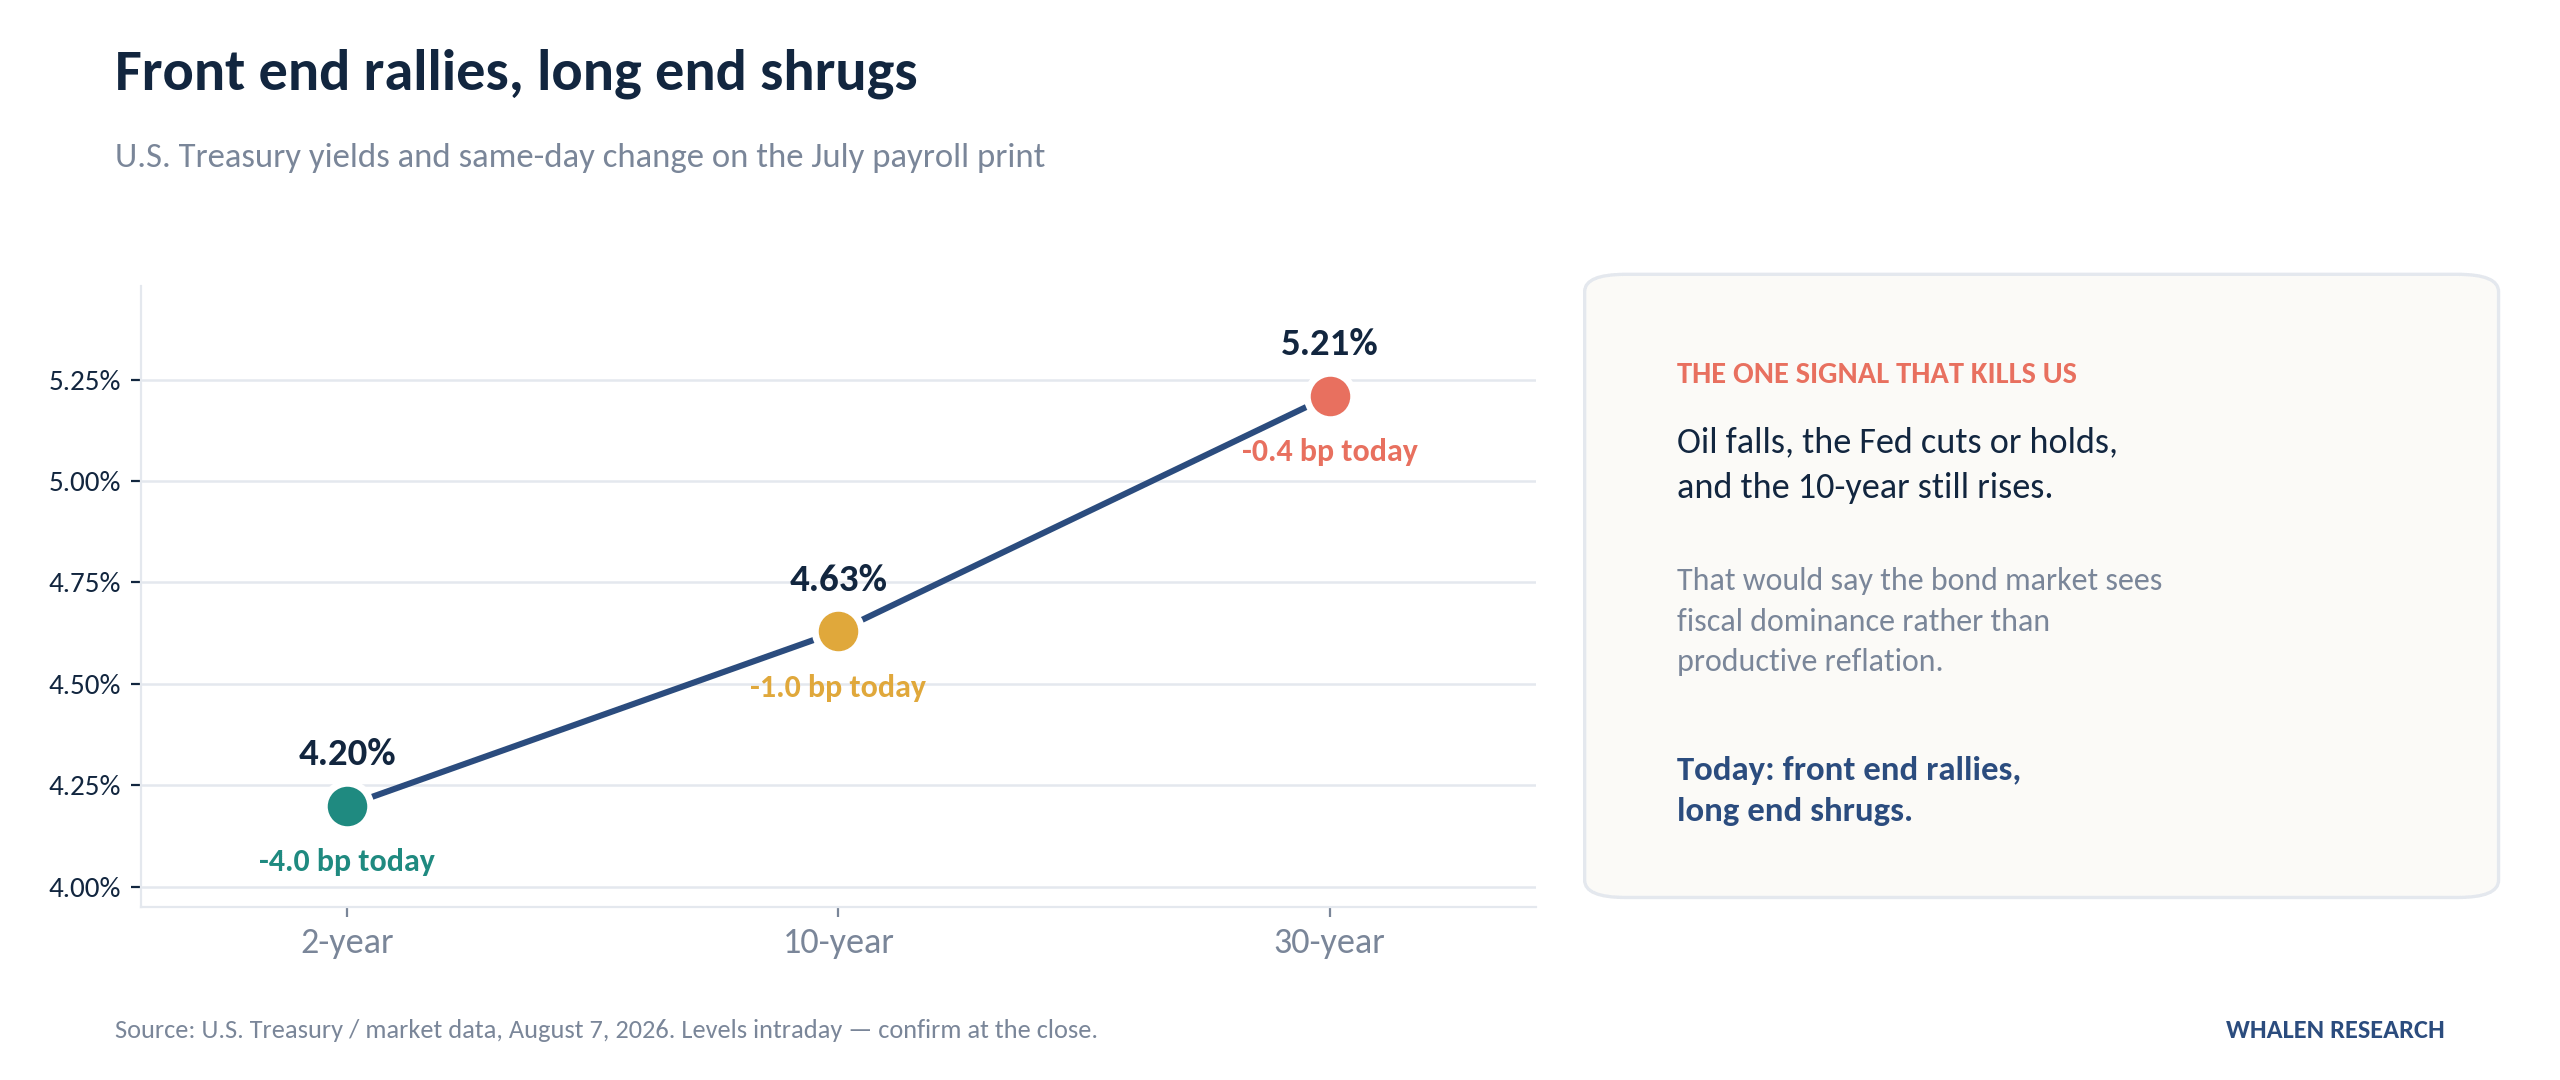
One session doesn’t prove anything and I’m not going to pretend it does, but that’s the shape of the thing I just told you would prove me wrong, and I’d rather point at it here in August than try to explain it away in December.
If that happens, I’m gonna change my mind and fast, but hey, that’s investing. Hey, I’m an investigator, not the defense attorney for my thesis.
What I’m watching now
By the end of September, I want Brent below $70, regular shipping through Hormuz, falling war-risk insurance and lower gasoline. I want the Fed to avoid a September hike, I want the two-year Treasury moving lower and, just as importantly, I don’t want to see the long end of the curve blowing out while all of that happens.
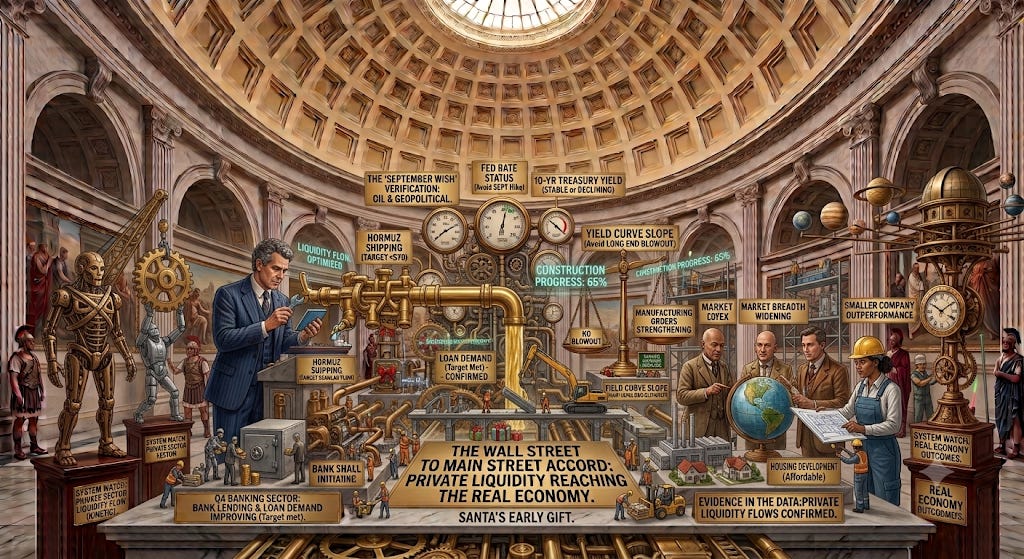
During Q4, I want the 10-year stable or declining, bank lending and loan demand improving, manufacturing orders strengthening, market breadth continuing to widen and smaller companies beginning to outperform. Most importantly, I want evidence that private liquidity is actually reaching the real economy because that’s when the Wall Street to Main Street thesis goes from something that sounds nice in a speech to something we can actually see in the data.
If Santa can bring me an early gift, Happy New Year!
The bottom line
My belief remains that Trump is trying to build a domestically focused, investment-led expansion and sell it directly to working Americans, and to do this he needs cheaper energy because it lowers inflation pressure, improves household purchasing power and gives businesses some room to absorb the enormous upfront costs of reshoring and investment.
Warsh ultimately appears to want a smaller Federal Reserve footprint and a more market-driven financial system, but I don’t believe he can normalize into weakness. He first needs growth, productivity and private credit creation strong enough to replace part of the role the Fed currently plays, and the money-center banks are being given more capacity to handle the financial plumbing.
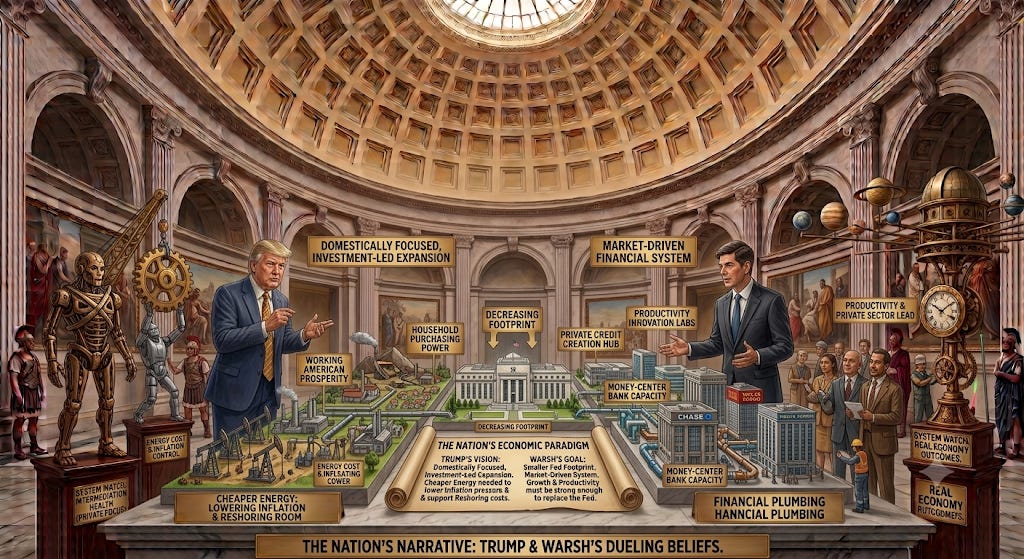
Now let’s find out whether the water actually reaches Main Street.
An Iran agreement and oil in the $60s could provide the window because lower energy reduces inflation pressure, lowers business expenses and potentially gives Warsh room to normalize rates without surrendering inflation credibility.
So that’s the plan:
Lower oil gives Trump political ammunition
A normalization cut gives the economy breathing room
Private banks take more responsibility for the plumbing
Reshoring and investment move capital further into the physical economy
Then, once the economy is humming, Warsh has a much better chance of normalizing the Fed from strength rather than trying to normalize it into weakness.
This is a call for productive reflation, falling energy inflation and a much broader economic expansion, and remember what the market is actually debating today because investors are still arguing about whether Warsh hikes in September while I’m arguing that by December he cuts. If I’m right, that isn’t a small difference in opinion, it’s a completely different regime.
Now if only I can just get the clues to start cooperating.
Luke Perry
Portfolio Manager, Whalen Financial