


Happy Monday, everyone.
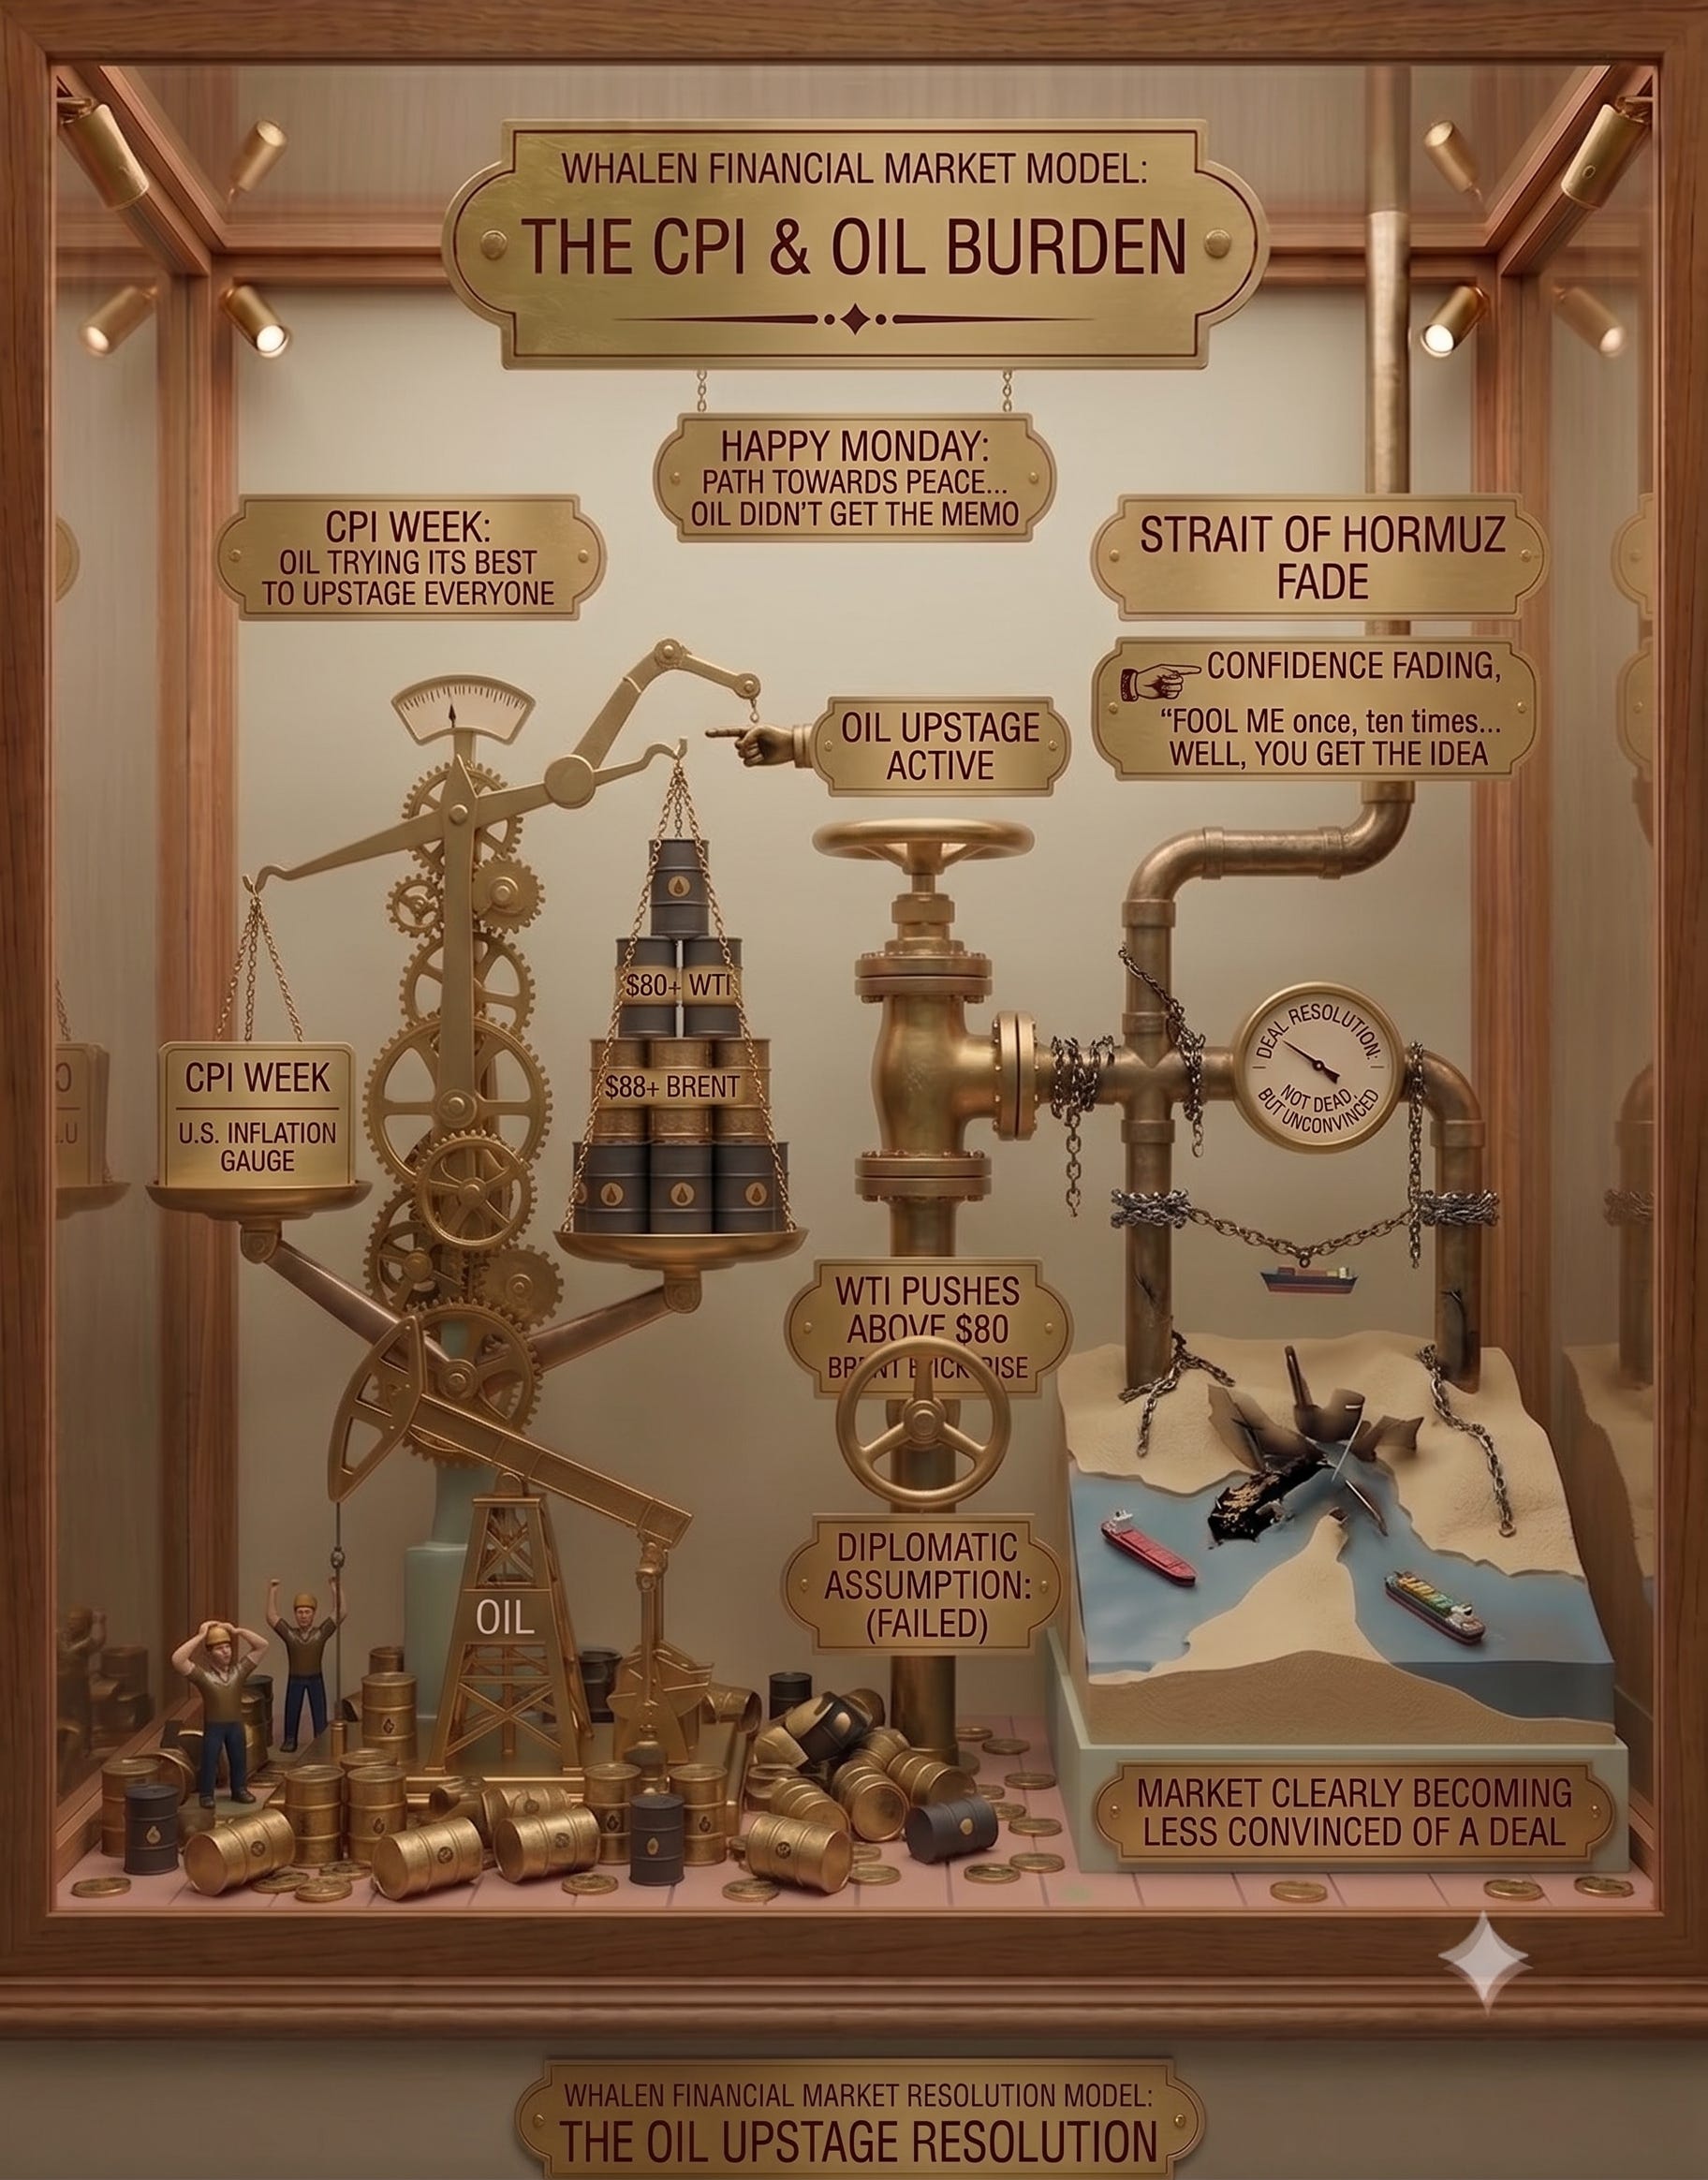
Ok, so if you read my piece from Friday, you know I was looking for a path toward peace and lower oil. Apparently oil didn’t get the memo, at least not yet. It’s CPI week and oil is trying its best to upstage everyone.
WTI pushed above $80 this morning and Brent is back near $88 as confidence in a quick reopening of the Strait of Hormuz continues to fade. Fool me once, shame on you. Fool me ten times... well, you get the idea.
The negotiations aren’t dead, but the market is clearly becoming less convinced that a deal is right around the corner.
For investors, this isn’t just about oil. If oil settles back down, great. I can go back to talking up our 2026/2027 base case with sugar plum fairies and oil eventually heading toward $65.
If Brent starts moving toward $95 or $100, the conversation changes quickly. Higher gasoline prices hit consumers, inflation expectations rise, the Fed has less room to ease and long-term interest rates become even harder to bring down, complicating the curve-normalization thesis we’ve been discussing.
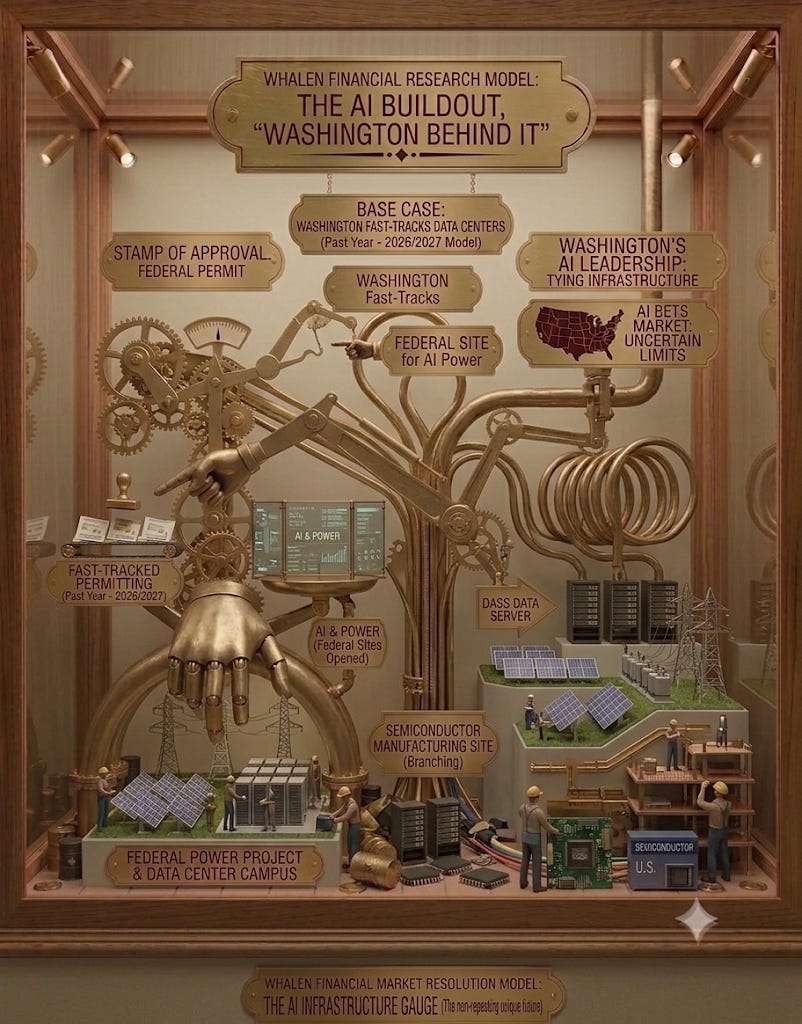
One other thing worth remembering is that the AI buildout increasingly has Washington behind it. Over the past year, the Trump administration has fast-tracked data-center permitting, opened federal sites for AI and power projects, pushed semiconductor manufacturing back toward the U.S. and tied new energy infrastructure directly to AI leadership.
Now how far this can go is anyone’s guess and many folks are trying their best to price their bets accordingly.
The Week Ahead
This week really does come down to oil and CPI.
The July CPI report arrives Wednesday morning after a surprisingly weak jobs report and right as energy prices are moving higher again.
So the weak employment numbers gave the Fed a little reason to pause, while oil is applying pressure from the other direction.
This week, CPI gets to be the referee.
CPI, Wednesday: A cooler number keeps the disinflation story alive and takes some pressure off rates. A hot services number puts higher-for-longer right back on the table.
PPI, Thursday: This tells us whether inflation pressure is rebuilding further up the supply chain. With oil moving higher, it matters a little more than usual.
Retail Sales, Friday: The consumer doesn’t need to be booming. I just need evidence that households are still spending and the weak jobs report isn’t turning into something bigger.
Michigan Sentiment, Friday: I care more about inflation expectations than the headline confidence number.
Oil and Hormuz: Probably the most important unscheduled “economic release” of the week. Brent moving toward $95 starts changing the whole conversation.
Earnings
A few reports matter for the bigger themes I’m watching:
Cisco: Another look at whether AI spending is spreading beyond hyperscalers and into broader enterprise networking.
Coherent: A useful read on optical demand and whether the AI infrastructure build is still pushing through the component layer.
Applied Materials: Probably the big one for me. I want to know whether semiconductor manufacturers are still spending aggressively on equipment or whether the stocks have started running ahead of the actual capex.
Around the World
Japan: The yen still hasn’t given me the clean strengthening signal I’d like, but Japan continues moving away from the ultra-easy monetary policy that defined it for decades. If Japanese capital eventually starts coming home in size, that matters for U.S. bonds and global liquidity.
Germany: Fiscal spending on defense, infrastructure and industrial capacity continues to support our European industrial thesis. The catch is that all that spending can also keep European interest rates higher.
China: Manufacturing slipped back into contraction in July, which matters for copper and strategic materials. Supply constraints are important, but eventually somebody still has to use the stuff.
What I’m Watching for Clients
Rates: I don’t want another sustained push higher in the long end. That would hit housing, growth stocks and the broader economic transmission story.
The consumer: I still think the consumer can improve later this year, but oil is now another hurdle. Higher gasoline prices will act like a tax nobody asked for.
AI infrastructure: I still like the structural story, but I’m becoming more selective. I want companies with real bottlenecks, earnings and pricing power.
New themes: Robotics, strategic materials, healthcare and parts of the consumer economy remain areas where I’m seeing potential opportunity.
So Where Does That Leave Us?
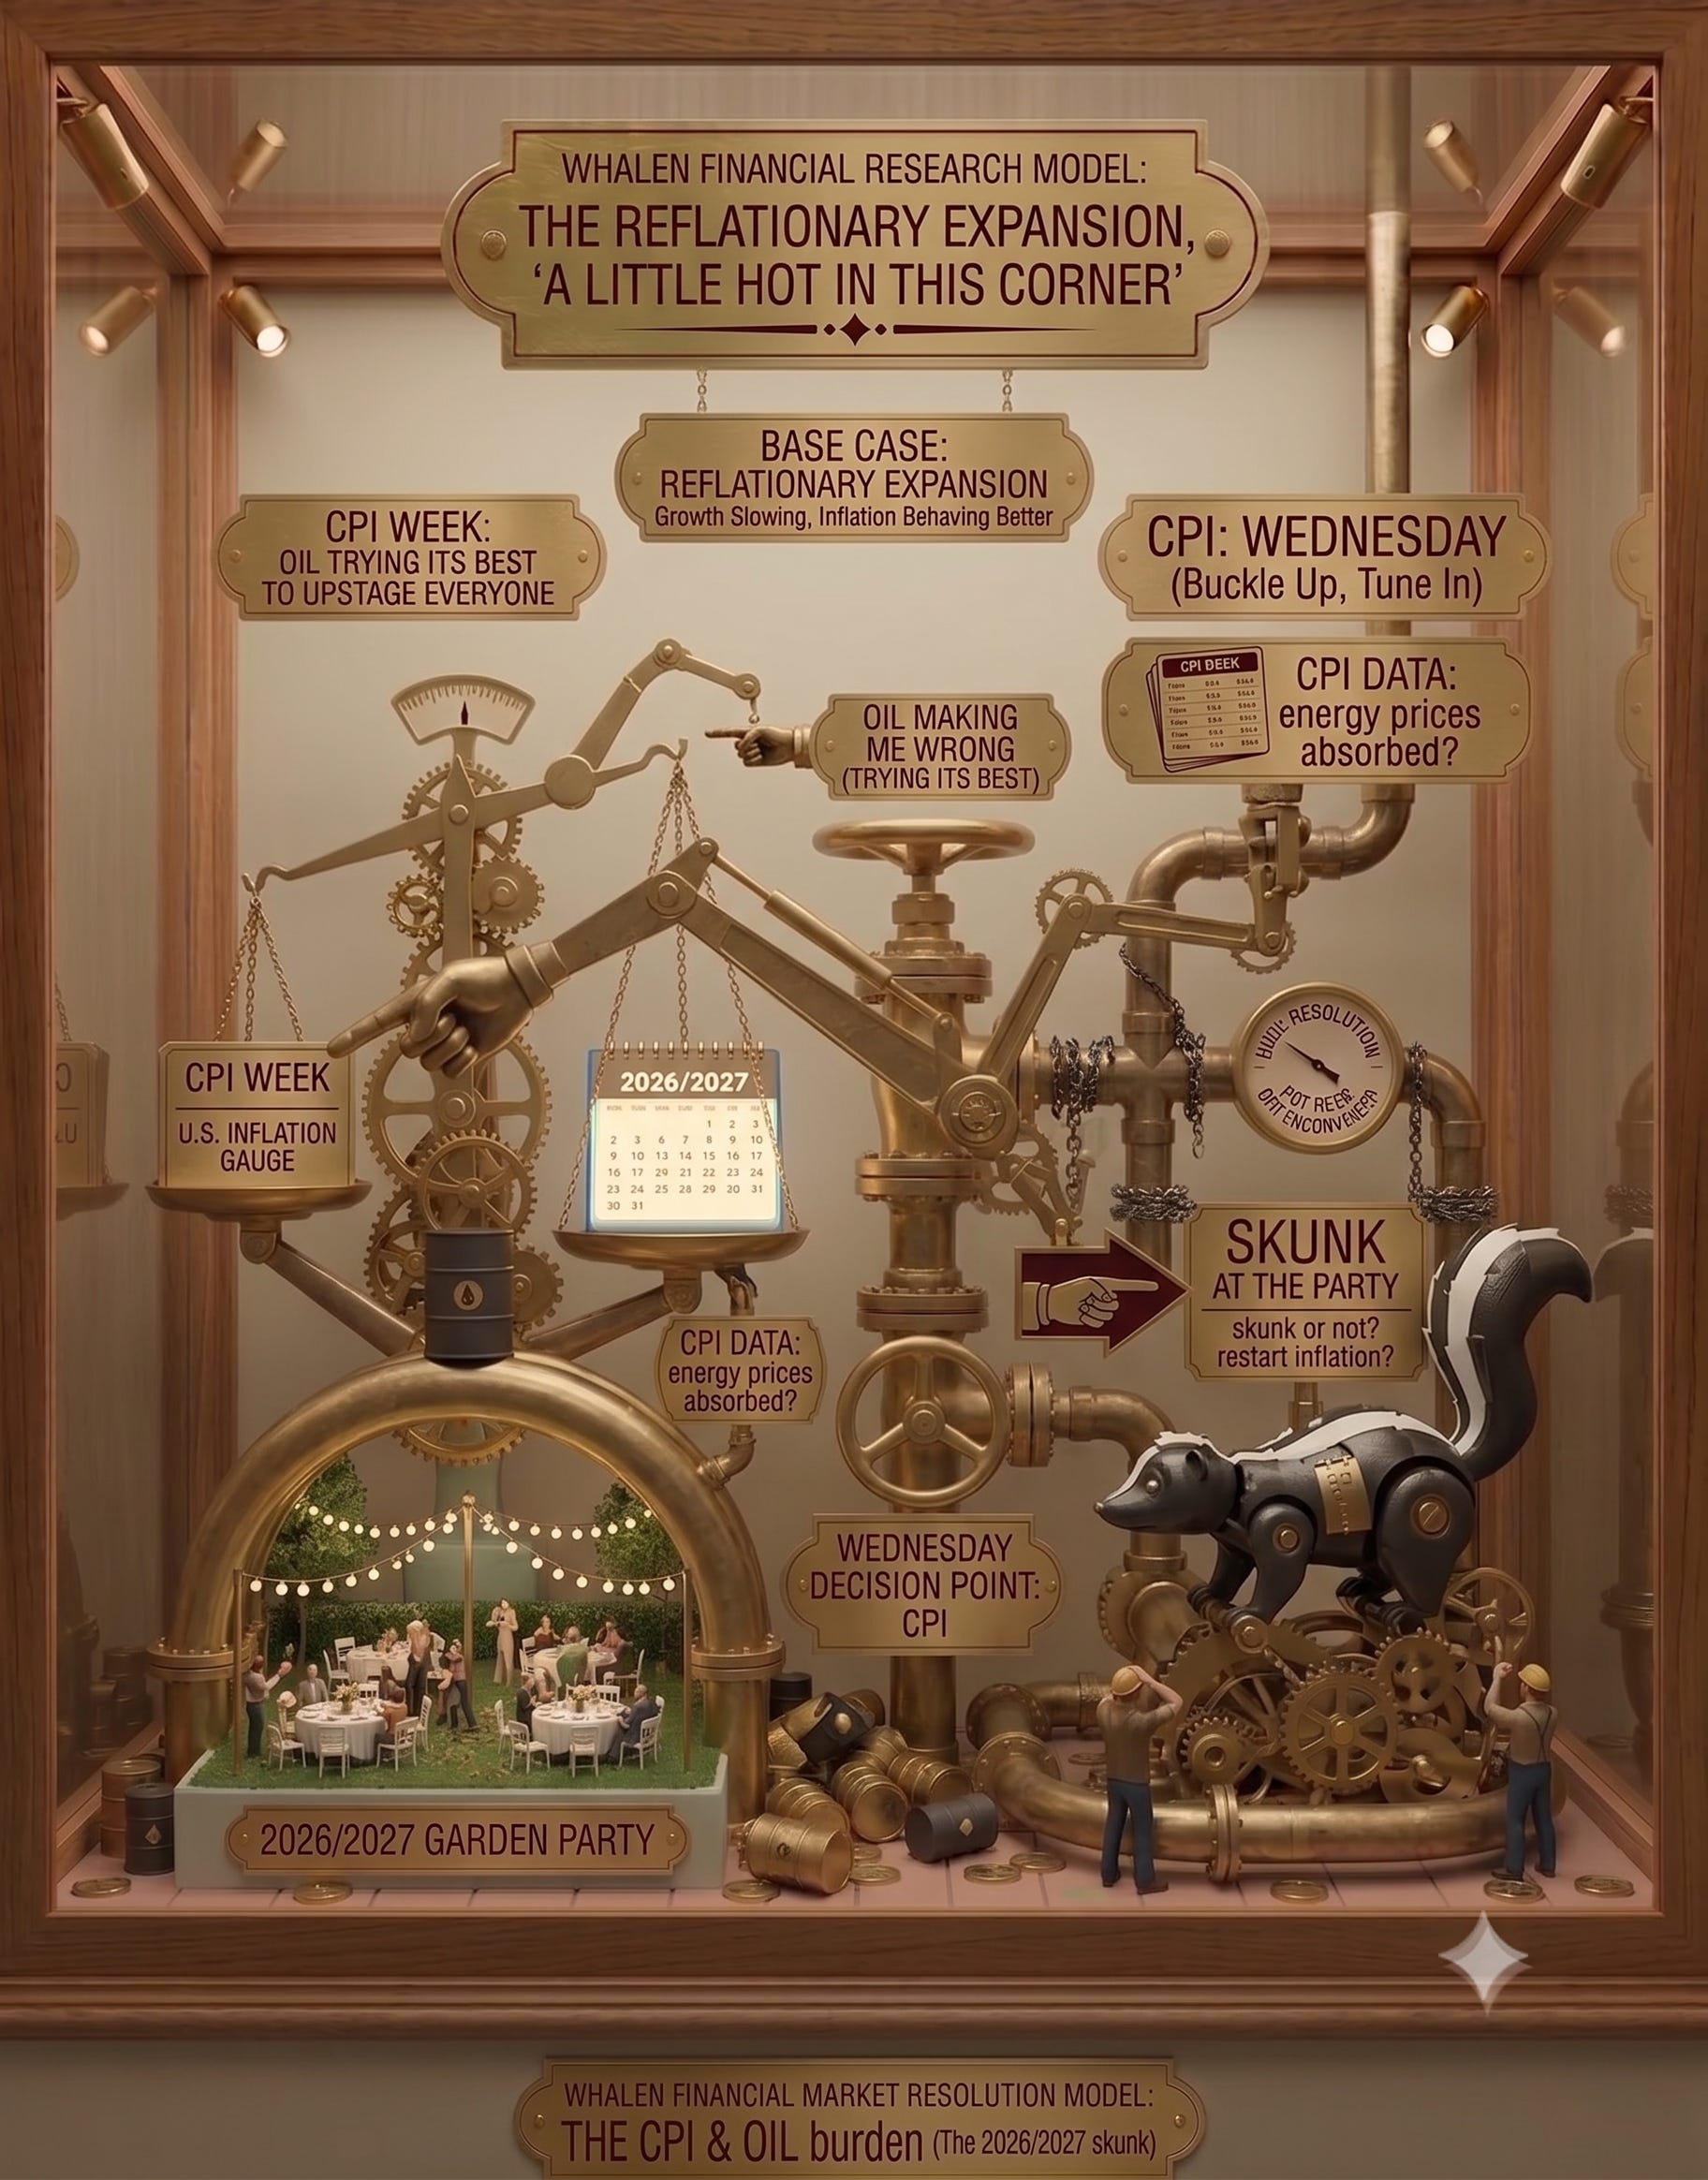
My base case remains a reflationary expansion, but it’s getting a little hot in this corner.
Growth is slowing, inflation has been behaving better, but oil is trying its best to make me wrong.
So buckle up and tune in Wednesday. CPI should give us a much better idea of whether the economy has absorbed higher energy prices without restarting the inflation problem, or whether oil is about to become the skunk at our 2026/2027 garden party.
Luke Perry
Portfolio Manager, Whalen Financial