


Weekend Recap
Happy Monday everyone! I don’t know about you, but I love it when the pieces of a puzzle start falling into place and you can finally begin to see the picture. Two things happened over the weekend that helped a few more pieces click into place for my outlook.
First, the AI capex cycle may have found an answer to one of its biggest questions: who finances all of this?
Nvidia stepped up and is backing OpenAI’s enormous Ohio data-center project through a structure that includes up to $105 billion of guarantees supporting the project and a $1.5 billion investment in developer SB Energy. OpenAI gets the compute capacity, SB Energy gets a far more financeable project, and Nvidia becomes the exclusive chip supplier for the initial build. Nvidia is using its balance sheet to help create the financing mechanism that allows its customers to keep buying Nvidia chips. Anyone say circular financing?
That matters even more following recent SEC staff guidance making certain data-center securitizations easier to finance by determining that qualifying structures fall outside traditional Exchange Act asset-backed-security rules. In plain English, the AI buildout is starting to develop its own capital-markets architecture.
There’s still a bear case here. Capital intensity is enormous, circular-financing concerns are legitimate, and eventually somebody has to earn an adequate return on all this infrastructure. But demand indicators continue to argue against the idea that capacity is simply being built into a vacuum. Memory remains extraordinarily tight, and Micron has previously said its 2026 HBM capacity is effectively sold out.
So the burden of proof is shifting toward the AI-infrastructure bears. The question is becoming less whether the spending happens and more who captures the economics as the spending moves downstream.
The second story is geopolitical.
So this isn’t the diplomatic clock running out, it’s an active war that a ceasefire keeps failing to hold. The conflict began in February with U.S. and Israeli strikes that killed Iran’s Supreme Leader, and Washington has maintained a naval blockade of Iran since. The June memorandum of understanding gave both sides 60 days to reach a comprehensive deal. Trump had already called the truce “over” on July 7, and Monday marked the formal expiration of that window without one.
Trump’s response today wasn’t just rhetorical escalation as he told Iran to “put up the white flag of surrender,” and separately threatened to bomb Oman, a U.S. ally, if it “gets in the way” of talks to reopen the Strait of Hormuz.
It’s also not contained to the Gulf as we’ve got Houthi pressure on Red Sea shipping intensifying, while the Israel-Hezbollah ceasefire remains fragile. This is increasingly a multi-front regional conflict, and the Hormuz premium needs to be priced against that broader backdrop.
That puts the Hormuz premium firmly back in play. WTI is sitting in the low $80s, shipping routes remain disrupted, and the market still is still handicapping the difference between political theater and an actual deterioration in Gulf shipping conditions.
Copper deserves separate attention as well. U.S. imports have surged while LME inventories have tightened dramatically, creating an increasingly distorted physical market. So this can look like booming demand, but part of what we’re really seeing is tariff front-running, inventory relocation and a scramble for immediately deliverable metal.
That’s why I’m watching LME backwardation, not just the copper price. I still like the structural copper thesis, but after a physical squeeze like this, entry price matters.
The Week Ahead
Remember what we talked about a week or two ago? I still have a very hard time seeing Warsh hike rates in September. After softer employment, inflation and retail data, investors have sharply reduced expectations for another near-term hike.
The probability of a September increase is now roughly 31%, down considerably from just a week ago. A Reuters survey released Monday found most economists expect the Fed to remain at 3.50%–3.75% through year-end. I’m still a little more dovish than consensus as I think there’s a decent chance we get 25–50 basis points of cuts before year-end if the recent softening in employment, inflation and consumption continues and we get some sort of resolution with Iran.
And that is what will make Wednesday interesting..
The July FOMC vote was 9–3, with three policymakers preferring a hike. The question now is whether those three represented an isolated hawkish flank or whether the minutes reveal broader discomfort with holding rates where they are.
The bond market should tell us first. TLT is trading around $81.39 today. If we get a clean break below $80, I’m paying attention as the bond market may be telling us the Fed debate is more hawkish than equities appreciate.
If they reveal a larger hawkish bloc, September gets repriced and equities may not be happy about it.
Key Events to Watch
Housing Starts & Building Permits — Tuesday, Aug. 18
The exact monthly print matters less to me than permits. Housing remains trapped between structural undersupply and brutal affordability. Builder sentiment ticked higher in August but remains historically weak, with mortgage rates still near 6.8%.
If permits deteriorate materially, the Housing Reacceleration thesis needs to be pushed farther out. If permits hold while starts wobble, I’m less concerned.
Industrial Production — Tuesday, Aug. 18
This is one of the better checks against our Growth pillar, currently sitting at 64 but rolling over. I’d like to see industrial activity confirm that the manufacturing and automation cycle is stabilizing. A weak number alongside softer consumption would strengthen the argument that we’re later in the cycle than the risk markets currently imply.
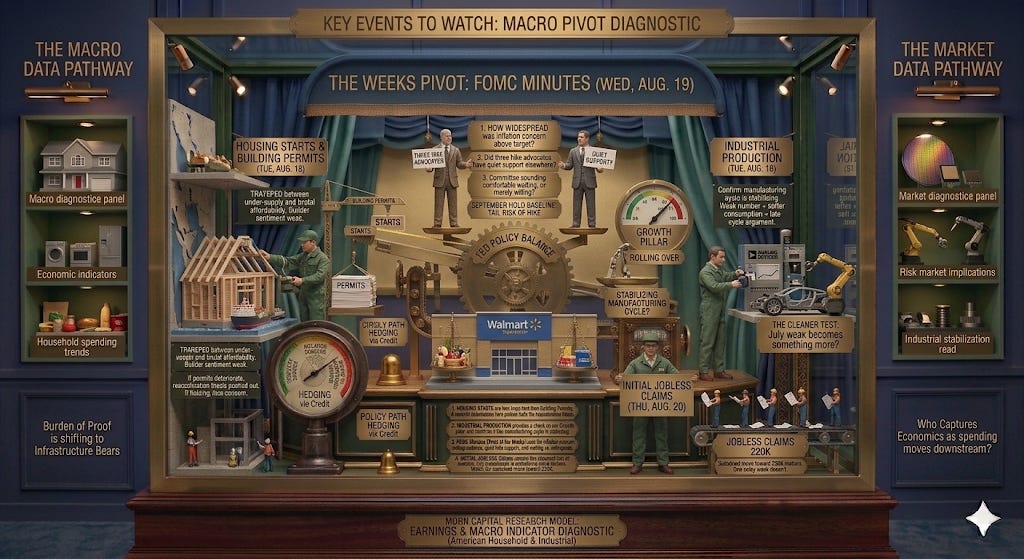
FOMC Minutes — Wednesday, Aug. 19
This is the week’s pivot.
I’m looking for three things:
How widespread was the concern about inflation remaining above target?
Did the three hike advocates have quiet support elsewhere in the committee?
Does the committee sound comfortable waiting, or merely willing to wait one more meeting?
September hold is now the baseline and the tail risk is the market realizing that another hike is still very much on the table.
Initial Jobless Claims — Thursday, Aug. 20
Claims remain one of the cleaner tests of whether July’s employment weakness is becoming something more serious. Now one noisy week doesn’t matter, but a sustained move toward or through the 220K area would.
Earnings This Week
Home Depot — Tuesday
Housing and contractor demand.
I care more about comparable sales, big-ticket transactions and management’s view of the second half than whether EPS beats consensus by six cents. Home Depot reports Tuesday.
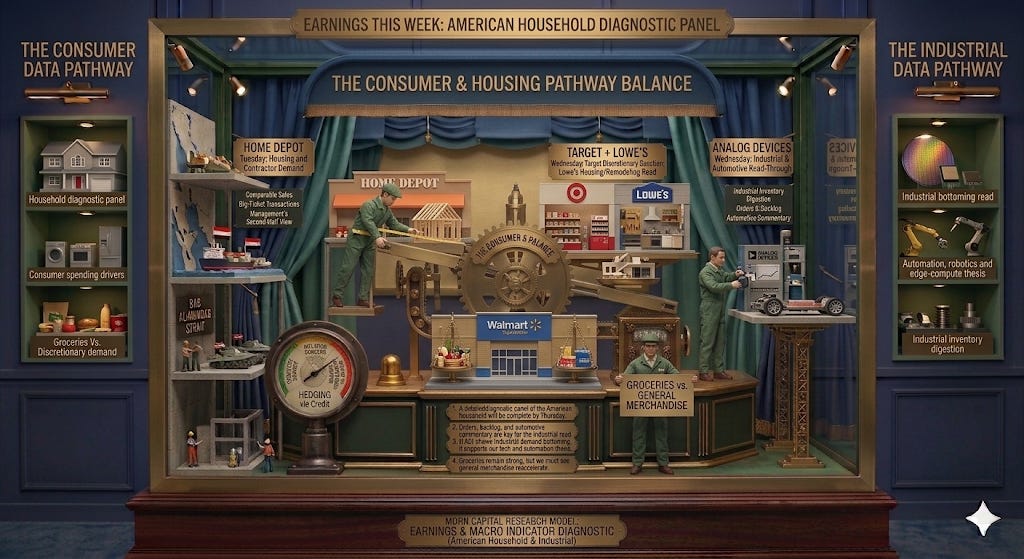
Target + Lowe’s — Wednesday
Target helps answer the discretionary-consumer question. Lowe’s gives us another housing/remodeling read. Between HD, LOW, TGT and WMT, we’ll have a pretty good diagnostic panel on the American household by Thursday.
Analog Devices — Wednesday
This may be the most important portfolio read-through of the week.
ADI reports Wednesday, and I’m listening for evidence that industrial inventory digestion has finally run its course. Orders, backlog, automotive and industrial commentary matter more than the headline EPS number.
If industrial demand is genuinely bottoming, that matters well beyond ADI. It would support our automation, robotics and edge-compute thesis.
Walmart — Thursday
The real consumer health check. I want general merchandise more than groceries. If groceries remain strong while discretionary categories weaken that’s not exactly consumer reacceleration yet.
Global Macro
Japan is becoming increasingly important. Q2 growth disappointed today, but Japanese bond markets largely shrugged it off. Ten-year JGB yields pushed toward three-decade highs as markets increasingly focus on inflation and the possibility of another BOJ hike.
That makes the yen one of the most important cross-asset signals on my screen because the danger isn’t simply that USD/JPY moves. It’s that a meaningful yen appreciation begins unwinding leveraged positions financed in cheap yen. We’ve seen this story and it’s not pretty for anyone.
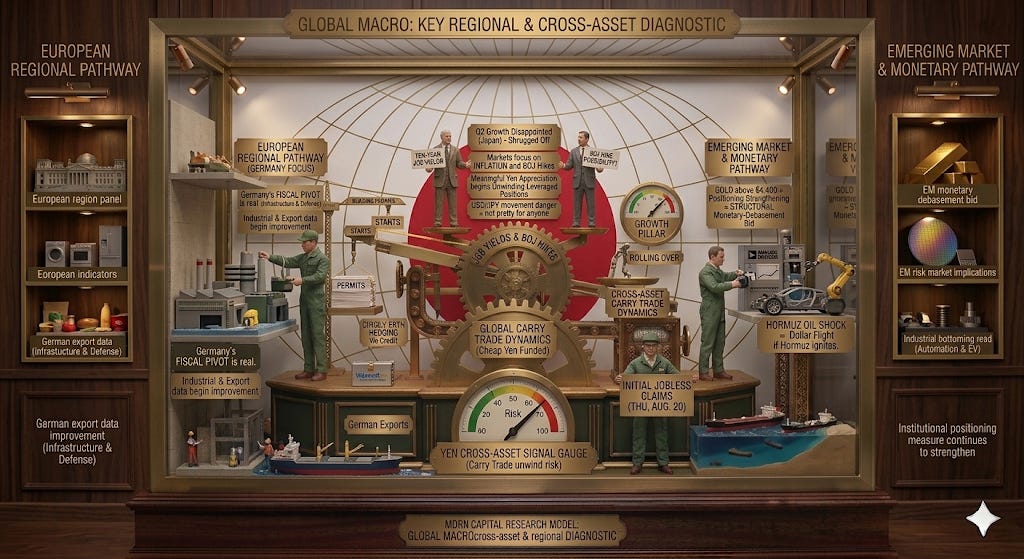
Europe meanwhile remains more interesting than many believe. Germany’s fiscal pivot toward infrastructure and defense is real, and recent German industrial and export data have begun showing improvement.
On emerging markets, gold above $4,400, together with our institutional-positioning measure continuing to strengthen, tells me the monetary-debasement bid has become more structural than tactical.
Dollar softness continues to help EM, but Hormuz creates the obvious risk. An oil shock that generates another flight into dollars could shut that window quickly.
So Where Does That Leave Us?
I would not call this clean Goldilocks, but how about “late-cycle resilience with a narrowing path to Goldilocks”?
Growth is slowing but hasn’t broken, while inflation is improving but remains too high for comfort. The Fed appears increasingly likely to sit still in September, but July’s three hawkish dissents remind us that the next move isn’t automatically lower. Japan is tightening, oil remains above $80, and the AI investment cycle continues to truck along with no obvious end in sight. Not yet, anyway.
All-in-all, that doesn’t tell me to get defensive. It tells me to become more selective about what kind of risk we own.
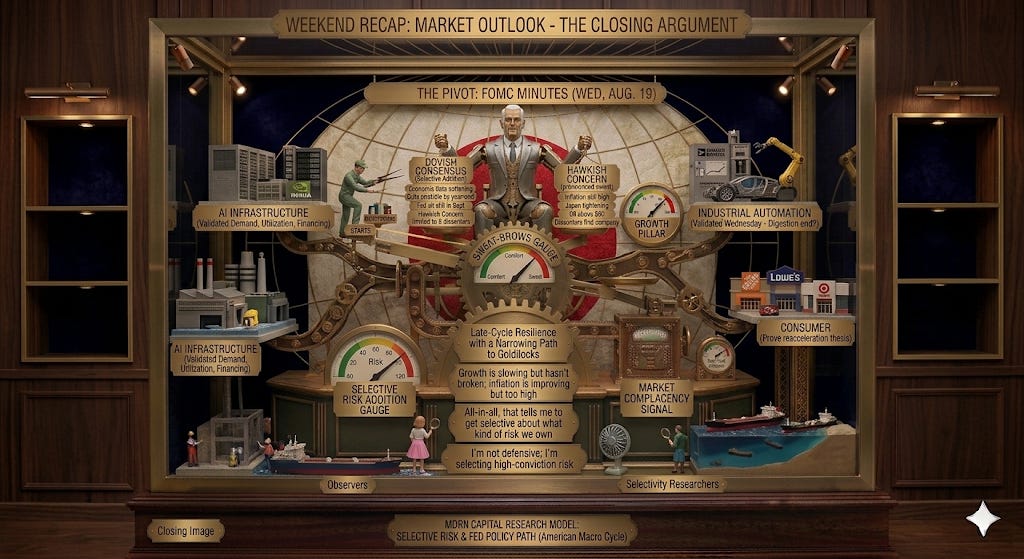
AI infrastructure remains high conviction, particularly where demand is being validated by actual contracts, utilization and financing. Industrial automation gets another test Wednesday with ADI. And the consumer has to prove the reacceleration thesis through HD, LOW, TGT and WMT.
If the FOMC minutes confirm that the hawkish concern doesn’t extend much beyond the three July dissenters, I’m more comfortable adding selectively to rate-sensitive risk. However, if the minutes reveal that the hawks have company, I don’t change my projections, but the sweat above my brow becomes a little more pronounced.
Luke Perry
Portfolio Manager, Whalen Financial