


Happy Monday, everyone! Can you smell it? Seasons are changin, the kids are back in school, and it’s almost the official get yourself back to work season. So with renewed excitement, lets get rolling!
Ok, so we’ve spent the past couple of weeks talking about Kevin Warsh, sticky inflation, the possibility of another Fed hike, and whether the economy is actually strong enough to absorb one. Now we get to stop guessing for a few days, because the labor market is about to give us a pretty good look under the hood.
At the same time, Brent is back above $90, the 10-year Treasury is hovering around 4.75%, and the Middle East is still a mess, much to my dismay. Throw in Broadcom, Dell and Palo Alto Networks reporting earnings, and there’s plenty to keep us busy before everyone disappears for Labor Day weekend.
Macro
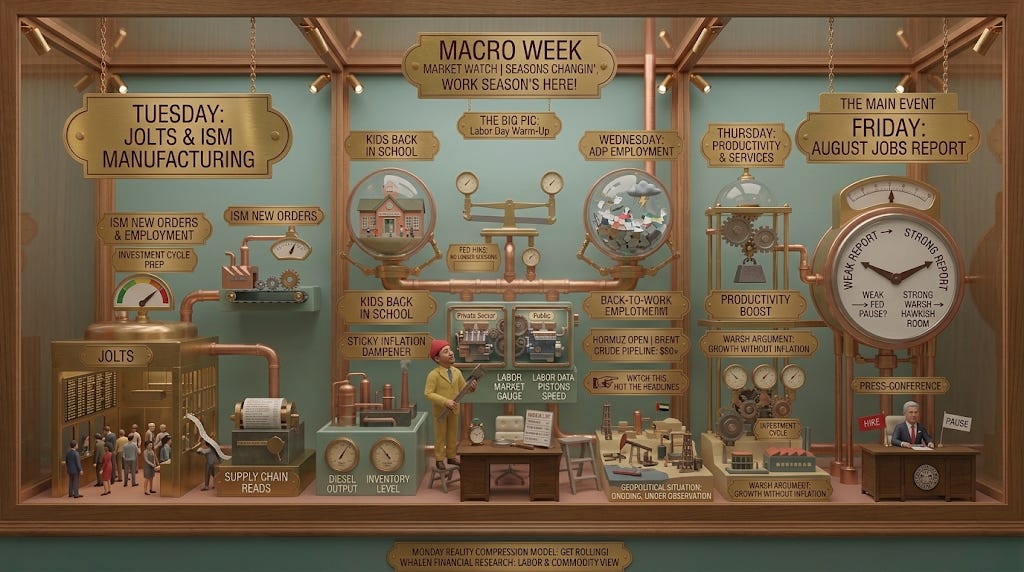
Tuesday brings JOLTS and ISM Manufacturing, which should give us our first decent read on whether the labor market is simply slowing or actually starting to crack. I’m less interested in a couple tenths on the headline than in new orders and employment, especially after Warsh spent today talking about a new investment cycle. If companies are really preparing to spend, eventually we should see evidence they’re willing to hire too.
Wednesday gives us ADP, and while this can always be an adventure, after July’s weak employment report, I don’t think the market is going to ignore much this week.
Thursday brings productivity, unit labor costs and ISM Services, which may be more interesting than they sound. Productivity sits right in the middle of Warsh’s argument that stronger investment could let the economy grow faster without the same inflation pressure. Let’s see if there is an indication of this.
Friday brings the August jobs report, and this is the main event. Another seriously weak number would make it much harder for the Fed to justify hiking in September, while a strong report would give Warsh more room to keep talking tough.
The Fed and Rates
Warsh has pretty clearly changed the conversation. The market isn’t debating when the next cut arrives anymore, it’s debating whether the Fed could actually hike again. You know my thoughts on this and if you don’t then its an I don’t think so.
That makes this week’s labor data especially important, because the Fed can talk tough all it wants, but if hiring keeps deteriorating, the bond market is going to start asking how much room they really have.
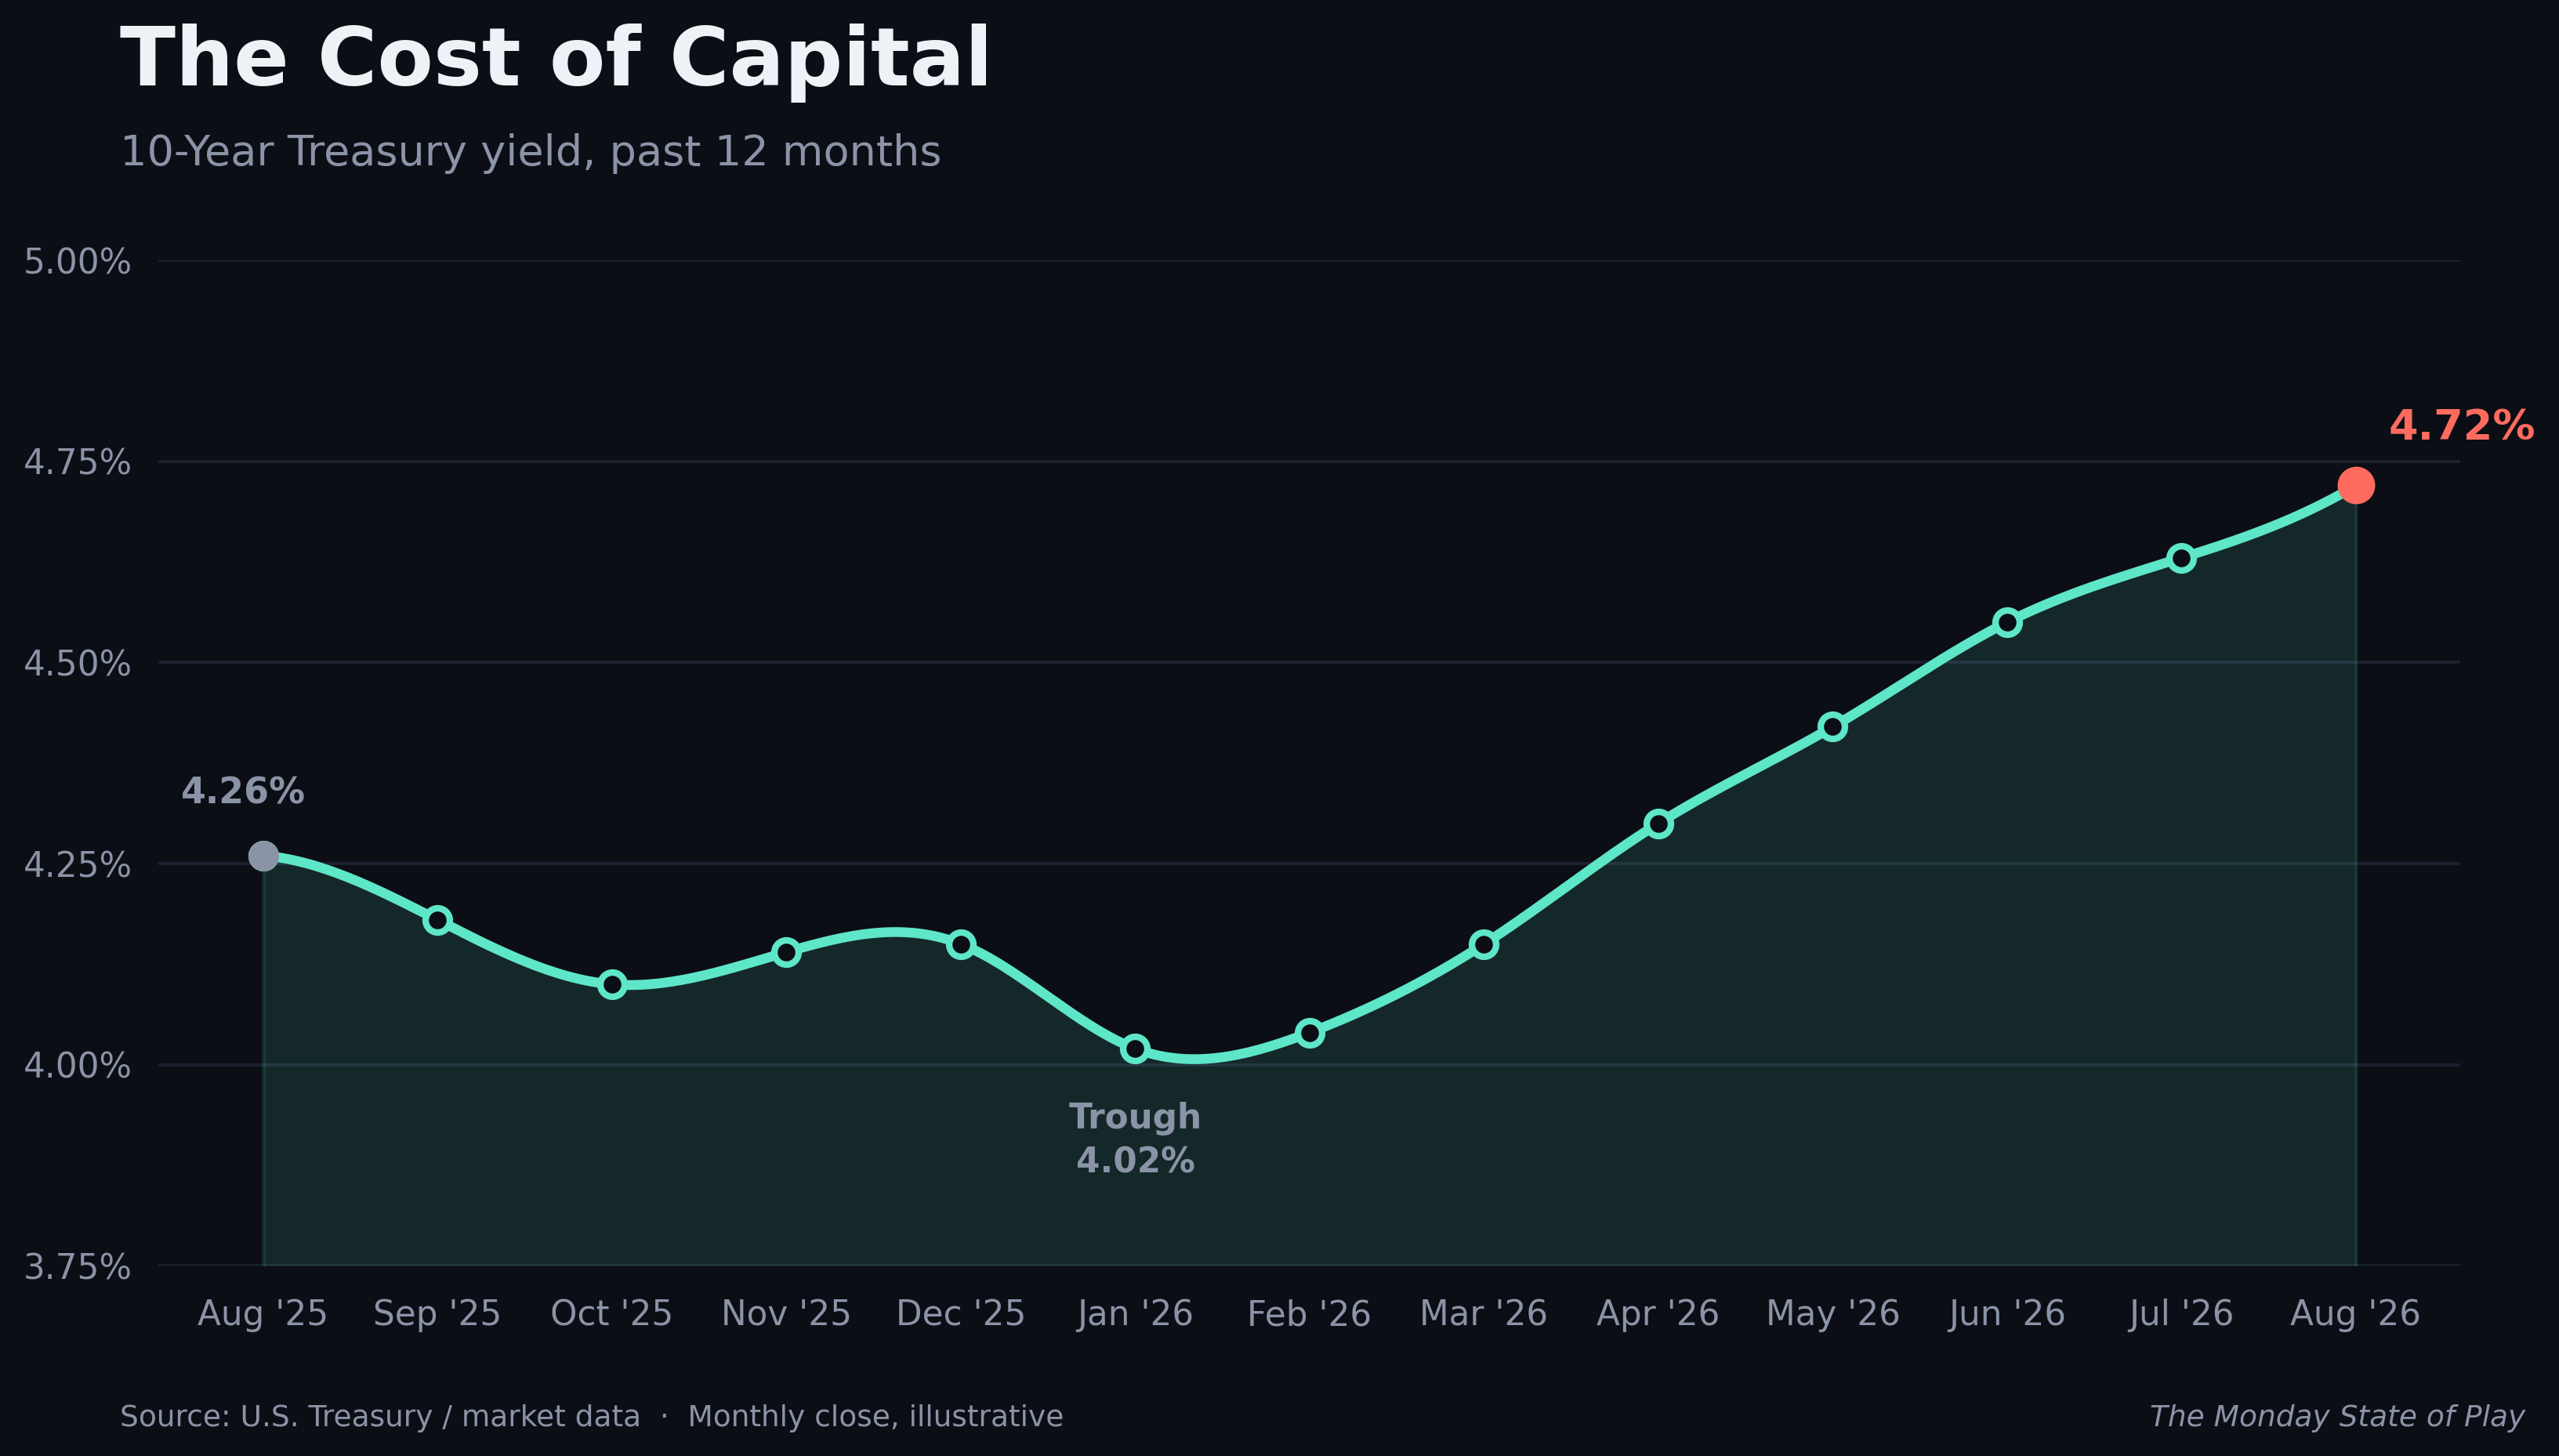
The 10-year near 4.75% matters too. We’re getting close to the point where higher rates stop being an interesting macro story and start being a problem for equities, housing, and anything else that needs cheaper financing.
Earnings
We’re well past the busiest part of earnings season, but this week’s reports line up nicely with something we’ve been saying for months: the AI trade isn’t disappearing, it’s moving through the stack.
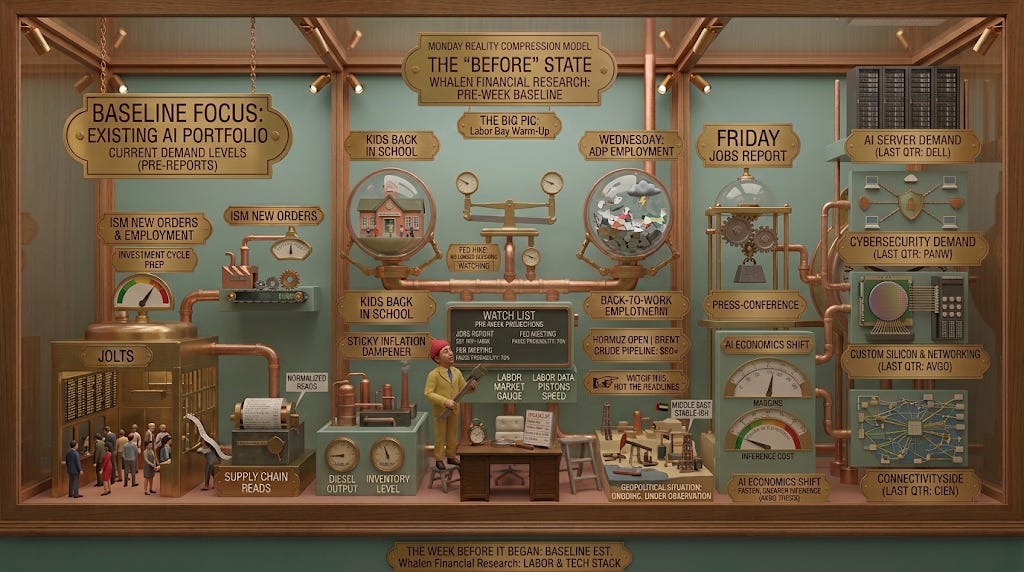
Dell Technologies (DELL) reports Tuesday. I’ll be watching AI server demand, backlog and margins. We know the spending is enormous. The more important question is who actually makes money from it.
Palo Alto Networks (PANW) also reports Tuesday, giving us a look at cybersecurity demand as AI creates more data, infrastructure and attack surfaces that need protecting.
Broadcom (AVGO) reports Wednesday, probably the most important report of the week for us. Nvidia already showed demand remains strong; Broadcom gives us another look at custom silicon, networking and the push toward faster, cheaper inference. Our thesis isn’t that hardware spending disappears, it’s that the economics gradually shift toward the parts of the stack that let companies do more AI work for less money.
Ciena (CIEN) reports Thursday, giving us another look at the connectivity side of the buildout. More compute eventually means more data moving around, and all of that still has to get from point A to point B somehow.
Oil and the Middle East
Unfortunately, Hormuz has once again decided it would like a speaking role.
Brent is back around $90 while diplomatic progress moves at roughly the speed of cold molasses. That matters a lot more when the Fed is talking about hiking than it did when markets were still expecting cuts.
For now, keep watching $95 Brent. If we start moving through there and talking seriously about $100 again, the inflation conversation changes fast.
What I’m Watching
The market’s trying to thread a fairly small needle this week. We’d like a labor market that’s slowing without falling apart, enough activity to support earnings and investment, some evidence productivity is improving, and, preferably, oil moving the other way. That keeps the broader reflationary expansion thesis intact without forcing the Fed to slam on the brakes. Is that too much to ask for?
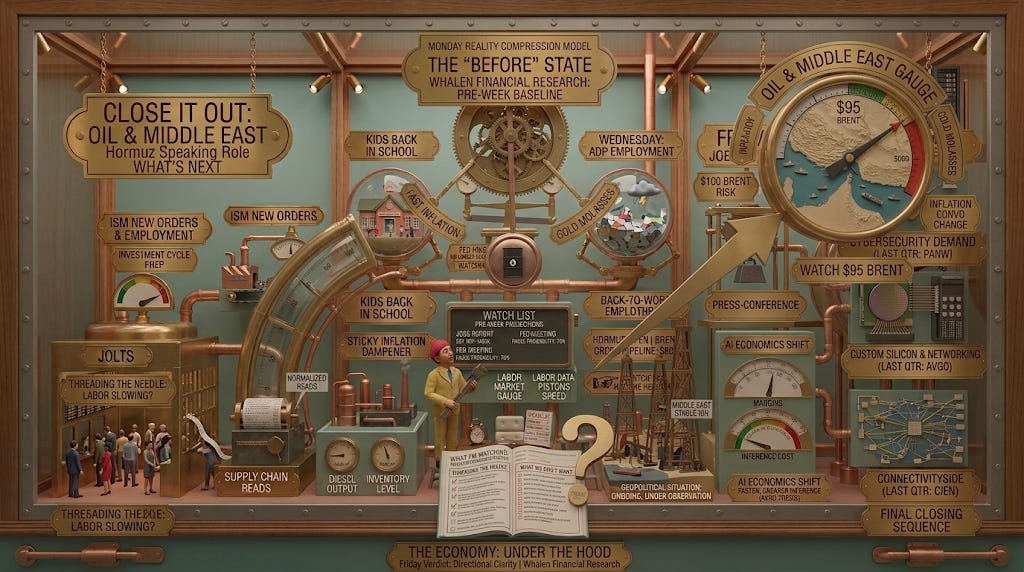
What we don’t want is weak employment sitting alongside $95 oil and rising Treasury yields, slower growth, stubborn inflation and tighter financial conditions, all at once.
By Friday afternoon, we should have a much better idea which direction we’re headed. The easy part of the calendar is behind us, and now we get to see what this economy is actually made of.
Luke Perry
Portfolio Manager, Whalen Financial