


Happy Monday, everyone! Now that’s how you get a Monday rolling!
The 10-year Treasury crossed 5% this morning, Brent is still above $100, and Kevin Warsh gets the microphone Wednesday with the market looking for 25 bips.
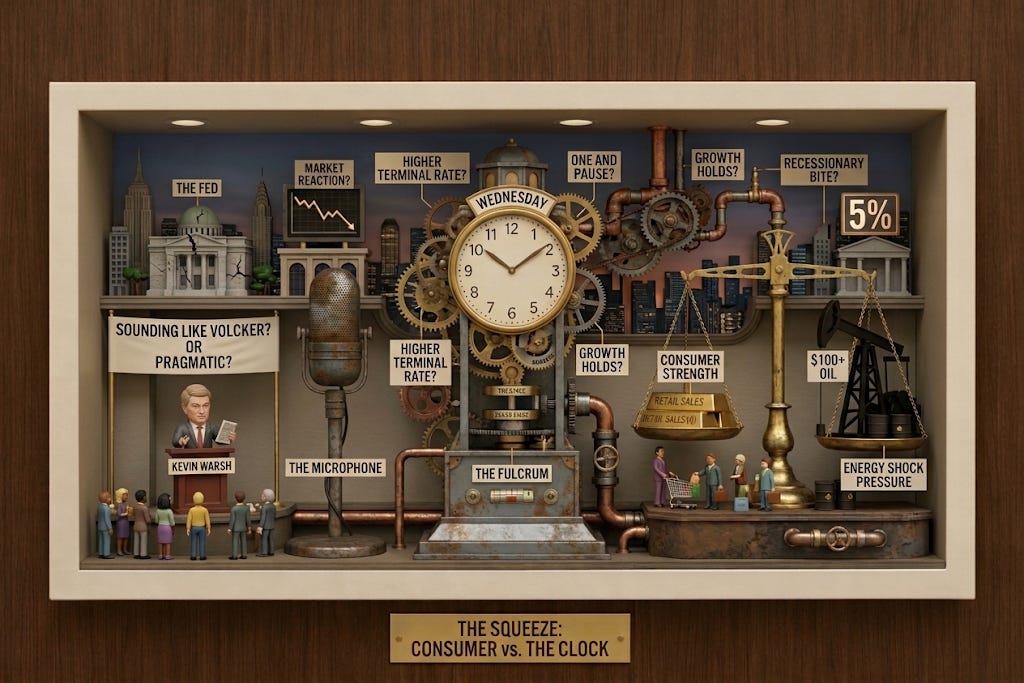
Now this got me thinking and I’ll ask you the same thing i’ve been asking myself:
What happens when the Fed raises rates into $100-plus oil while the 10-year is already sitting around 5%?
And to me, that’s really the State of Play this week.
Key Events
• Retail Sales, Wednesday: We’ll see whether consumers are finally feeling higher gasoline prices, higher borrowing costs and a softer labor market.
• FOMC Decision + Dot Plot, Wednesday: The hike matters less than what comes next. One and pause? Or a higher terminal rate?
• Initial Jobless Claims, Thursday: Still one of the cleaner reads on whether the labor market is actually starting to crack.
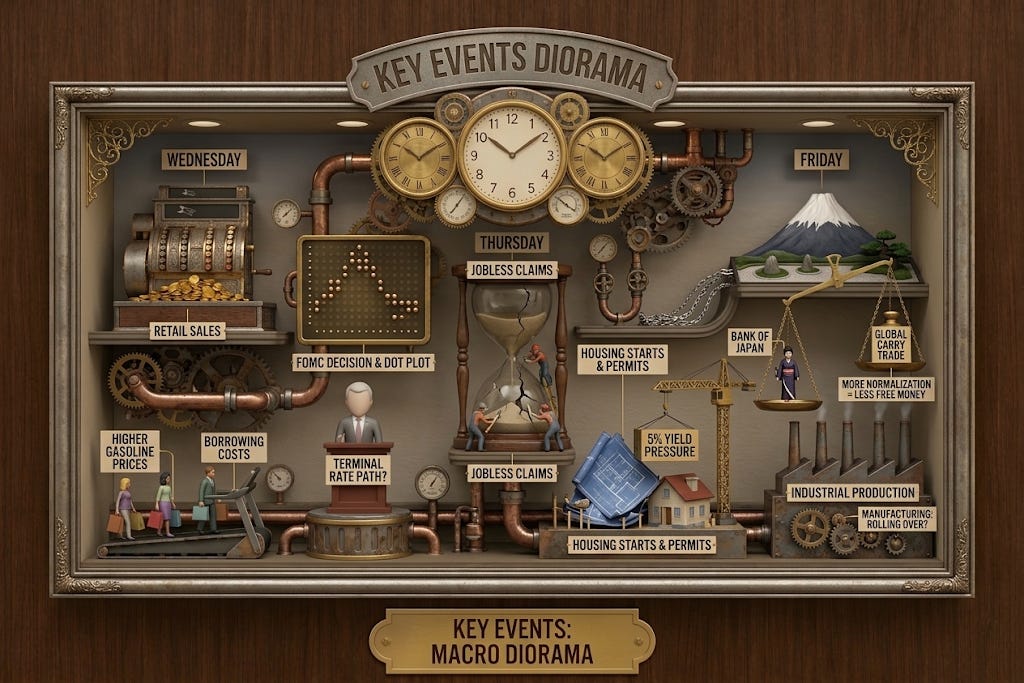
• Housing Starts + Permits, Thursday: Permits matter more to me here. If 5% Treasury yields are starting to bite, housing should tell us.
• Bank of Japan, Friday: More normalization means less free money from Japan and potentially more pressure on global carry trades.
• Industrial Production, Friday: Another useful check on whether manufacturing is rolling over or just muddling through.
Global Macro
• Europe: Lagarde is getting louder about Europe’s need to spend on AI capacity, power, defense and strategic infrastructure. That fits the broader theme we’ve been watching all year. Europe is slowly moving from austerity-minded policymaking toward a much more investment-heavy model.
• Japan: The Bank of Japan is back in focus Friday as it continues moving away from decades of ultra-easy policy. Another step toward normalization matters for the yen, Japanese financial conditions and the global carry trade.
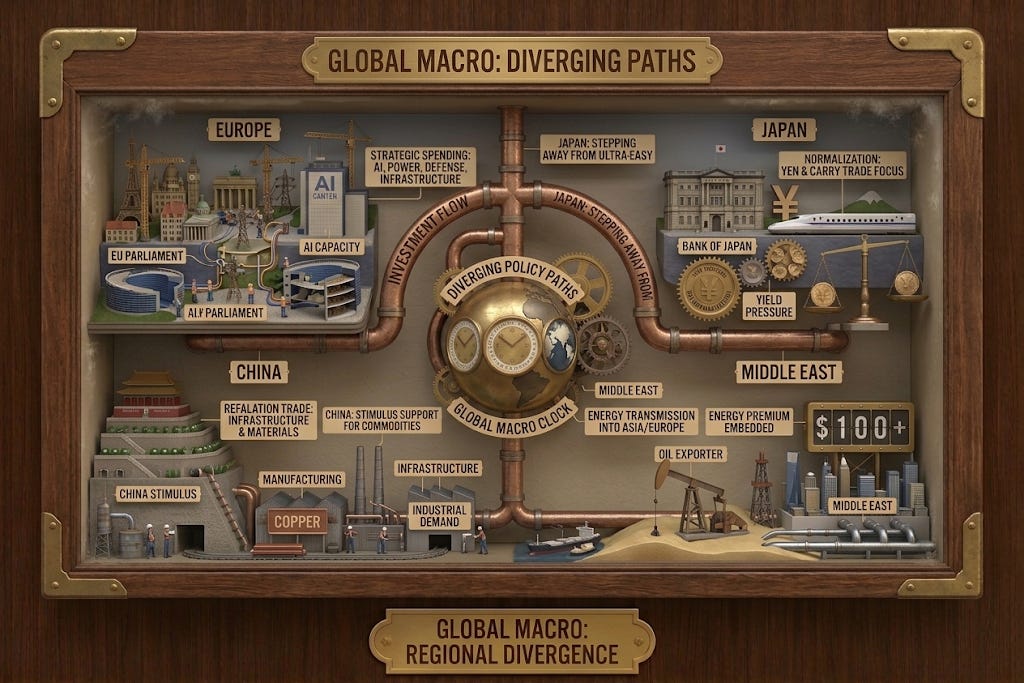
• China: Beijing remains important for the commodity side of the reflation trade. If Beijing leans harder into infrastructure and manufacturing support, that should keep support under copper, industrial demand and parts of the global materials complex.
• Middle East: Oil remains the obvious transmission mechanism into everything else. The longer crude stays above $100, the more pressure it puts on Europe, Asia and other large energy importers, while giving exporters a much different fiscal picture.
• The bigger picture: Outside the U.S., the story is increasingly one of diverging policy paths. Europe is leaning into strategic spending, Japan is normalizing, China is still trying to engineer growth, and the Middle East is keeping an energy premium embedded in the system.
So Where Does That Leave Us?
Like I said Friday, I’m not changing our 12 to 18 month outlook because the 10-year printed 5%. Doesn’t mean a forecast designed around fiscal dominance and hot growth isn’t going to be painful in the short run.
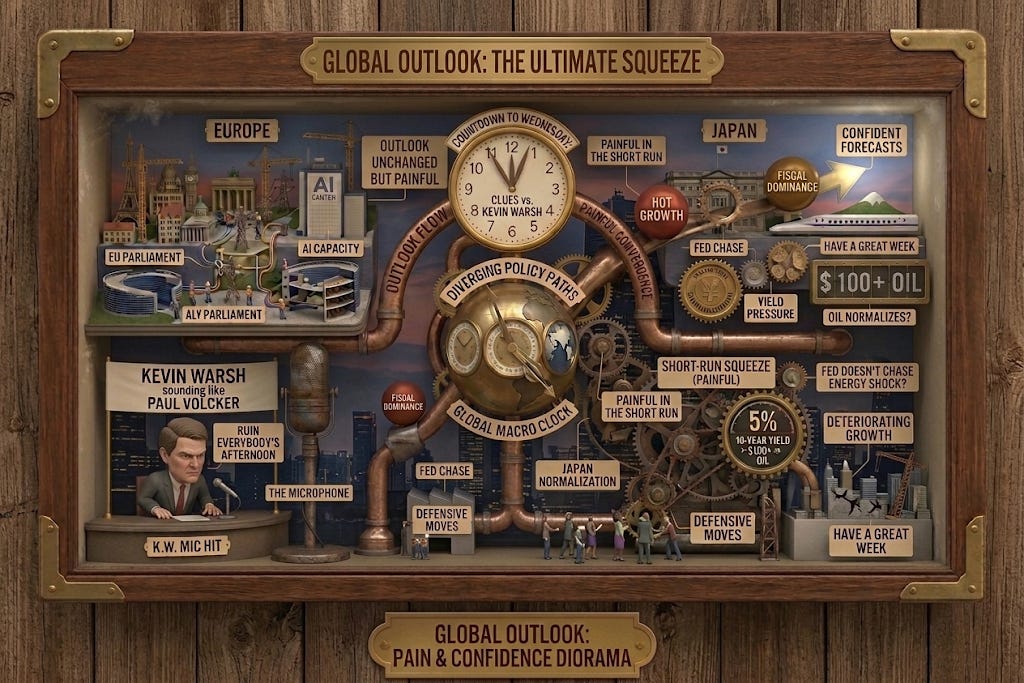
Our thesis still works if growth holds, oil eventually normalizes and the Fed doesn’t chase a temporary energy shock too far.
However, what i’m not looking for is 5% Treasury yields + $100 oil + more Fed tightening + deteriorating growth. It doesn’t necessarily change my long term forecast but it could force some defensive moves I was hoping I didn’t have to take.
But for now, we remain confident in our forecasts while we wait for Wednesday to give us more clues. Unless Kevin Warsh hits the mic sounding like Paul Volcker and ruins everybody’s afternoon.
Have a great week, everyone.